PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114638

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114638
Phenylketonuria Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the phenylketonuria treatment market size is expected to grow from USD 0.92 billion in 2025 to USD 1.01 billion in 2026 and is forecast to reach USD 1.66 billion by 2031 at 10.46% CAGR over 2026-2031.
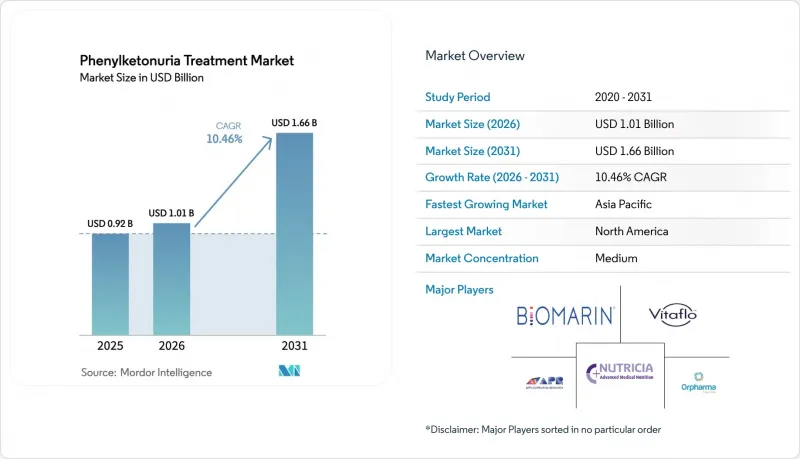
This report is Segmented by Drug Type (Sapropterin & Analogues, Pegvaliase, Gene Therapy Candidates, and More), Route of Administration (Oral, Parenteral/Injectable), PKU Severity (Classic PKU, and More), End User (Hospital Pharmacies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Phenylketonuria Treatment Market Trends and Insights
Mandatory Newborn-Screening Momentum
Universal screening programs in North America, Europe, Japan, and South Korea detect phenylketonuria within 2 days of birth, but China's 2024 expansion to 31 provincial capitals added 14,000 annual diagnoses previously missed. India's 2025 pilots in three large states screened 1.2 million babies and identified a prevalence of 1 in 18,000, underscoring the unmet demand for affordable medical foods and future access to enzymes. Early detection lessens cognitive-impairment risk yet exposes wide treatment inequities: high-income markets migrate to enzyme and gene platforms, whereas low-income regions struggle to finance even phenylalanine-free formula. Prevention-driven payback models increasingly influence payer calculus, because averting disability yields lifetime productivity gains that offset screening costs.
Regulatory Tailwinds for Orphan Drugs
The FDA's March 2024 breakthrough-therapy tag for sepiapterin compressed review to six months, enabling a July 2025 market debut in the United States. Orphan exclusivity through 2032 blocks generic entry, letting sponsors command premium pricing while mandating quarterly real-world phenylalanine reporting. The EMA waived parts of pegvaliase's pediatric program in July 2024, accelerating an adolescent label expected in early 2026. Faster pathways reduce clinical cost but heighten post-approval risk, because payers can claw back revenue if real-world metabolic control lags trial endpoints. Japan mirrored these incentives in 2025, giving rare-disease developers a harmonized tripolar market.
Specialty-Drug Pricing Pressure & Payer Step Edits
92% of U.S. pegvaliase claims required diet-failure documentation in 2025, generating a 4.3-month approval lag and 18% abandonment before the first dose. Germany's G-BA judged pegvaliase a "minor additional benefit," capping reimbursement at EUR 180,000 (USD 195,000) and requiring a 38% discount compared with the United States. Similar scrutiny in France and the United Kingdom sets a continental benchmark that lowers net revenue per patient and increases dependence on outcomes-based rebates.
Other drivers and restraints analyzed in the detailed report include:
- Diet-Liberalizing Enzyme Therapies Gain Adoption
- Oral Sepiapterin Approvals Broaden Treatable Genotypes
- Adult Adherence Drop-Off to Rigid Dietary Regimens
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pegvaliase secured 66.32% of phenylketonuria treatment market revenue in 2025 and underpins the largest single-product franchise in the space. However, gene-therapy candidates have the prospective 11.09% CAGR between 2026 and 2031, signaling an eventual reshuffle once one-time cures clear regulatory hurdles. Small-molecule and synthetic-biotic programs remain experimental and risk culling if Phase 2 data fail to demonstrate durable phenylalanine reduction.
Sapropterin generics, now price-eroded, stay relevant in health systems that favor step-therapy ladders, but sepiapterin's higher response rates and oral convenience will cannibalize this legacy niche. A biosimilar pegvaliase expected in Europe by 2028 could compress branded margins and force incumbents to compete on patient support services rather than price.
Parenteral formats retained 54.07% of 2025 turnover on the back of pegvaliase, yet oral therapies are on track for a 13.11% CAGR through 2031 as families gravitate toward pills over injections. The phenylketonuria treatment market share for oral drugs should exceed 45% by 2031 once sepiapterin approaches peak uptake and silk-film PAL secures at-scale manufacturing. Ambient-stable formats matter most in tropical regions and among highly mobile adult patients who face burdensome refrigeration requirements.
Even so, injectable supremacy persists in classic PKU cases that require higher enzyme activity than current oral bioavailability allows. Future market equilibrium will likely stratify: oral drugs for mild-to-moderate genotypes, injectables for severe phenotypes, and gene infusions for those eligible and antibody-negative.
Complete Report Scope:
- By Drug Type
- Sapropterin & Analogues
- Pegvaliase
- Gene Therapy Candidates
- Synthetic Biotics & Small-Molecule Transport Inhibitors
- Other Drug Type
- By Route of Administration
- Oral
- Parenteral / Injectable
- By PKU Severity
- Classic PKU
- Moderate / Variant PKU
- Mild PKU
- Hyperphenylalaninemia
- By End User
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 49.11% of global turnover in 2025, yet growth moderates as payers step in to cap therapy initiation, and patient penetration sits near 7% of the diagnosed population. The upcoming FDA adolescent approval for pegvaliase could add 1,500 U.S. patients, but widespread budget scrutiny tempers upside. Canada's single-payer model negotiates lower net pricing, further restraining revenue growth.
Europe ranks second in revenue but is highly price-sensitive; Germany's EUR 180,000 cap and France's similar ceiling anchor EU-wide negotiations. Registration-based patient tracking shows adult metabolic control well below guideline targets, a clinical unmet need that enzyme therapies can fix if payers relax step edits.
Asia-Pacific is forecast to grow at a 14.69% CAGR as China scales universal screening and Japan leverages its 2025 orphan-drug pathway to reimburse pegvaliase. India's pilots hint at untapped prevalence but lack national funding for specialty drugs. Australia and South Korea mirror Western Europe in both coverage and willingness to reimburse high-cost therapies, making them early adopters of gene infusions later in the decade.
Middle East & Africa and South America remain underpenetrated due to low screening rates and cold-chain gaps. Brazil's inclusion of PKU in its 2024 neonatal panel creates latent demand for medical foods but leaves enzyme access to private insurers. Ambient-stable oral enzymes could leapfrog injectables in these regions once late-stage data read out.
- Abbott Laboratories
- APR Applied Pharma Research (PKU GOLIKE)
- BASF
- Biomarin Pharmaceutical
- Cambrooke Therapeutics (Danone)
- Codexis
- Daiichi Sankyo Co. Ltd.
- Dr. Reddy's Laboratories
- Erytech Pharma
- Homology Medicines
- Jnana Therapeutics
- Nutricia Advanced Medical Nutrition
- Orpharma Pty Ltd
- Par Pharmaceutical (Endo)
- PTC Therapeutics
- SOM Innovation Biotech
- Synlogic
- Ultragenyx Pharmaceutical
- Vitaflo International (Nestle Health Science)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Mandatory Newborn-Screening Momentum
- 4.2.2 Regulatory Tailwinds for Orphan Drugs
- 4.2.3 Diet-Liberalizing Enzyme Therapies Gain Adoption
- 4.2.4 Oral Sepiapterin Approvals Broaden Treatable Genotypes
- 4.2.5 Gene-Transfer One-Time Cures Approach Late-Phase Trials
- 4.2.6 Silk-Film Oral PAL Technology Removes Cold-Chain Burden
- 4.3 Market Restraints
- 4.3.1 Specialty-Drug Pricing Pressure & Payer Step Edits
- 4.3.2 Adult Adherence Drop-Off to Rigid Dietary Regimens
- 4.3.3 Cold-Chain Logistics for Injectable Biologics in LMICs
- 4.3.4 Low BH4-Response Rates in High-Consanguinity Regions
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Drug Type
- 5.1.1 Sapropterin & Analogues
- 5.1.2 Pegvaliase
- 5.1.3 Gene Therapy Candidates
- 5.1.4 Synthetic Biotics & Small-Molecule Transport Inhibitors
- 5.1.5 Other Drug Type
- 5.2 By Route of Administration
- 5.2.1 Oral
- 5.2.2 Parenteral / Injectable
- 5.3 By PKU Severity
- 5.3.1 Classic PKU
- 5.3.2 Moderate / Variant PKU
- 5.3.3 Mild PKU
- 5.3.4 Hyperphenylalaninemia
- 5.4 By End User
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail Pharmacies
- 5.4.3 Online Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 APR Applied Pharma Research (PKU GOLIKE)
- 6.3.3 BASF SE
- 6.3.4 BioMarin Pharmaceutical Inc.
- 6.3.5 Cambrooke Therapeutics (Danone)
- 6.3.6 Codexis Inc.
- 6.3.7 Daiichi Sankyo Co. Ltd.
- 6.3.8 Dr. Reddy's Laboratories
- 6.3.9 Erytech Pharma SA
- 6.3.10 Homology Medicines Inc.
- 6.3.11 Jnana Therapeutics
- 6.3.12 Nutricia Advanced Medical Nutrition
- 6.3.13 Orpharma Pty Ltd
- 6.3.14 Par Pharmaceutical (Endo)
- 6.3.15 PTC Therapeutics Inc.
- 6.3.16 SOM Innovation Biotech SL
- 6.3.17 Synlogic Inc.
- 6.3.18 Ultragenyx Pharmaceutical
- 6.3.19 Vitaflo International (Nestle Health Science)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

