PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114663

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114663
Neurodiagnostics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, neurodiagnostics market size in 2026 is estimated at USD 9.79 billion, growing from 2025 value of USD 9.14 billion with 2031 projections showing USD 13.81 billion, growing at 7.12% CAGR over 2026-2031.
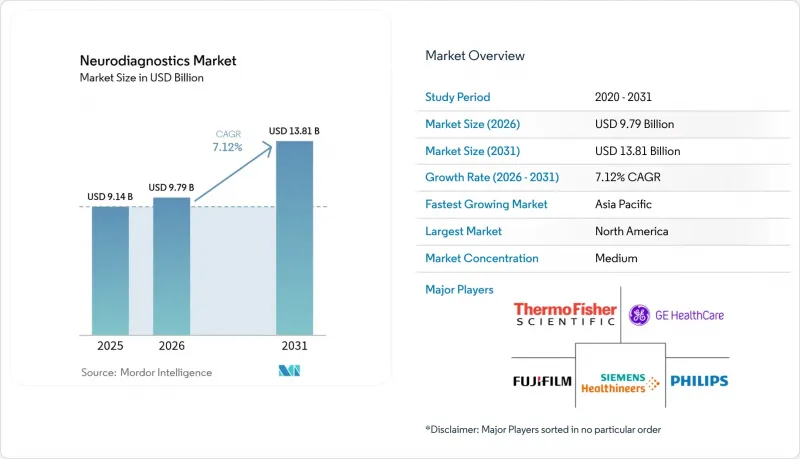
This report is Segmented by Product Type (Reagents & Consumables, and More), Technology (Neuroimaging Technologies, and More), Condition (Neurodegenerative Diseases, Cerebrovascular Disorders, and More), End-User (Hospitals & Surgical Centers, Diagnostic Laboratories & Imaging Centers, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Neurodiagnostics Market Trends and Insights
Growing Adoption of Novel Diagnostic Imaging Technologies
Artificial-intelligence-enabled scanners now shorten MRI sessions to under an hour while automating protocol selection, slice positioning and reconstruction, raising throughput without compromising image quality. Dual-engine reconstruction algorithms deliver noise-reduced, high-resolution neuro images that support quantitative tissue volume mapping and early lesion detection. Vendors are prioritizing helium-free magnets that require as little as 7 liters of coolant, cutting lifetime operating costs and easing procurement barriers in cash-strapped health systems. Competitive pressure intensifies as Canon Medical and United Imaging roll out comparable AI-ready platforms, forcing incumbents to accelerate upgrade cycles. For providers, these enhancements translate into higher scanner utilization, faster clinical decisions and improved patient satisfaction, all of which reinforce purchasing intent and embed AI workflows at the core of the Neurodiagnostics market.
Emergence of Blood-Based NFL and Other Neurological Biomarkers
Plasma assays targeting phosphorylated tau217, neurofilament-light chain and MTBR-tau243 are redefining neurological work-ups by offering non-invasive alternatives to lumbar puncture and PET imaging, with diagnostic accuracy above 85% in multi-center trials. Large diagnostic firms are partnering to co-develop high-throughput assays for automated immuno-analyzers, unlocking economies of scale and reducing per-test costs. The U.S. FDA's breakthrough-device pathway accelerates review cycles, yet payer hesitation persists; reimbursement rates for plasma-based Alzheimer's panels still lag behind legacy modalities. Despite pricing doubts, neurologists increasingly integrate biomarker panels into memory-clinic protocols, leading to earlier referrals, stratified trial enrollment and personalized therapeutics. As validation expands to Parkinson's, ALS and traumatic brain injuries, biomarker developers gain a multi-disease revenue stream that underpins the long-run expansion of the Neurodiagnostics market.
High Capital and Maintenance Costs of Advanced Neurodiagnostic Systems
Total ownership expenses for a helium-cooled 3-Tesla MRI can surpass USD 3 million when factoring installation, shielding and annual service contracts, an outlay that strains mid-size providers in Latin America and Southeast Asia. Although helium-free magnets cut running costs by 20-30%, the upfront premium still inhibits adoption. Multisite hospital systems therefore centralize high-end scanners, compelling peripheral clinics to refer patients and elongating care pathways. Laboratory automation promises long-term savings, yet "dark labs" require robotic track lines, AI middleware and redundant cybersecurity layers, with deployment estimates ranging between USD 10 million and USD 15 million for a 500-test-per-hour facility. Without subsidized financing or risk-sharing contracts, many regional providers postpone modernization, slowing the penetration curve of premium modalities within the Neurodiagnostics market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Geriatric Population and Longevity
- Rapid Expansion of Point-of-Care EEG Wearables in Emerging Markets
- Shortage of Trained Neurotechnologists & Neuroradiologists
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reagents & consumables produced recurrent cash flows equal to 51.02% of 2025 revenue as clinicians increasingly order serial blood-based panels for neurofilament-light chain, phosphorylated tau and GFAP monitoring. Instrument vendors strategically bundle proprietary cartridges with middleware analytics, cementing laboratory stickiness and smoothing quarterly revenue visibility in the Neurodiagnostics market. Clinical testing instruments-chiefly portable EEG systems, handheld transcranial Doppler units and point-of-care biomarker analyzers-form the second-largest contributor, propelled by hospital attempts to shorten emergency-department dwell times. Diagnostic imaging systems remain mission-critical, yet ASP pressure intensifies as capital budgets shift toward software subscriptions, cloud storage and cybersecurity upgrades.
Gene-therapy-linked diagnostics, though representing a small base, are scaling at a 9.28% CAGR through 2031 on the back of brain-computer-interface trials and CRISPR-mediated interventions for inherited ataxias. Neurodiagnostics market size for gene-therapy-companion tests is forecast to surpass USD 1.07 billion by 2031, supported by the need to genotype patients, monitor vector biodistribution and verify on-target protein restoration. Vendors such as Beckman Coulter offer RUO panels covering p-Tau217 and GFAP, creating de-facto standards for biomarker endpoints in clinical trials. As regulatory agencies finalize guidelines on surrogate markers and long-term safety monitoring, the consumables franchise will deepen, reinforcing the product-portfolio diversity vital for sustainable Neurodiagnostics market growth.
Neuroimaging technologies preserved a commanding 68.10% revenue share in 2025, underpinned by a global installed base exceeding 45,000 MRI and CT scanners dedicated to neurological applications. Generative reconstruction algorithms now deliver sub-millimeter isotropic resolution, enhancing lesion detectability and surgical-planning precision. Vendor-neutral analytic suites integrate DICOM-level segmentation with cognitive-decline prediction, further extending scanner reach into preventive neurology.
Neuroinformatics & AI analytics platforms, although starting from a smaller revenue base, are expanding at 11.45% CAGR and are projected to account for a double-digit share of the Neurodiagnostics market size by 2031. Cloud-deployed seizure-prediction engines achieve area-under-curve scores of 0.97, facilitating risk-stratified care pathways. Multilingual natural-language-processing modules mine electronic health-records for subtle cognitive changes, prompting earlier imaging referrals. As GE Healthcare layers AWS native-services into its Edison platform, competition pivots from hardware specifications to algorithmic performance, cybersecurity credentials and clinical-trial validation data sets, fundamentally re-ranking supplier differentiation in the Neurodiagnostics market.
Complete Report Scope:
- By Product
- Reagents & Consumables
- Clinical Testing Instruments
- Diagnostic & Imaging Systems
- By Technology
- Neuroimaging Technologies
- In-Vitro Diagnostics
- Neuroinformatics & AI Analytics Platforms
- By Condition
- Neurodegenerative Diseases
- Cerebrovascular Disorders
- Epilepsy & Seizure Disorders
- Sleep Disorders
- Headache & Migraine
- Others (TBI, CNS Infections, Tumors)
- By End User
- Hospitals & Surgical Centers
- Diagnostic Laboratories & Imaging Centers
- Ambulatory Care & Emergency Settings
- Research & Academic Institutes
- Specialized Neurology Centers
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America remained the revenue leader with 36.00% share in 2025, propelled by NIH BRAIN Initiative grants totaling USD 321 million in 2025 that cushion academic-industry collaboration pipelines. U.S. payers continue to reimburse MRI and bio-assay bundles under value-based-care pilots, encouraging integrated diagnostic algorithms within accountable-care organizations. Canada, through Pan-Canadian AI strategy funds, supports provincial tele-neurology portals, while Mexico's private hospitals import portable EEG headsets to close specialist gaps.
Europe sustains high adoption due to robust universal healthcare financing and stringent but predictable CE-mark pathways. Germany refits radiology departments with helium-free scanners to align with sustainability targets, and its aging demographic keeps demand for neurodegenerative screening elevated. The U.K.'s Advanced Research and Invention Agency awarded USD 69 million to precision neurotechnology projects, sparking venture activity in Oxford and Cambridge clusters. Mediterranean markets improve access to plasmapheresis-based biomarker assays through EU solidarity funds, yet workforce shortages slow implementation, tempering Neurodiagnostics market penetration in rural areas.
Asia-Pacific, registering the fastest pace at 9.28% CAGR, benefits from China's 28% medtech expansion and a strategic pivot toward high-end imaging and AI platforms led by United Imaging and Mindray. Japan's healthcare-2035 roadmap embeds neuro-preventive screening into annual wellness checks, driving bulk procurement of EEG wearables for municipal clinics. India's National Digital Health Mission subsidizes cloud PACS and tele-EEG gateways, unlocking tier-II city demand. South Korea aligns reimbursement with AI-augmented imaging policy, whereas Australia's Medicare funds home-sleep studies, accelerating sleep-disorder diagnostics adoption. Collectively, these policy levers make the region the principal incremental volume contributor to the global Neurodiagnostics market.
- Siemens Healthineers
- GE Healthcare
- Koninklijke Philips
- Canon
- FUJIFILM
- Thermo Fisher Scientific
- Roche
- Natus Medical
- Nihon Kohden
- Lifelines Neuro Company
- Advanced Brain Monitoring
- Mitsar Co. Ltd.
- Medtronic
- Abbott Laboratories
- Boston Scientific
- Cadwell
- Compumedics
- Electrical Geodesics Inc.
- Neurosoft
- Masimo
- Quanterix Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Incidence Of Neurological Disorders
- 4.2.2 Growing Adoption Of Novel Diagnostic Imaging Technologies
- 4.2.3 Rising Geriatric Population And Longevity
- 4.2.4 Emergence Of Blood-Based NfL And Other Neurological Biomarkers
- 4.2.5 Rapid Expansion Of Point-Of-Care EEG Wearables In Emerging Markets
- 4.2.6 Government Neurotech Moonshot Funding & Public-Private Consortia
- 4.3 Market Restraints
- 4.3.1 High Capital And Maintenance Costs Of Advanced Neurodiagnostic Systems
- 4.3.2 Shortage Of Trained Neurotechnologists & Neuroradiologists
- 4.3.3 Reimbursement Uncertainty For Novel Biomarker And AI-Based Tests
- 4.3.4 Data Privacy & Cybersecurity Concerns With Cloud-Connected Brain Data
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Reagents & Consumables
- 5.1.2 Clinical Testing Instruments
- 5.1.3 Diagnostic & Imaging Systems
- 5.2 By Technology
- 5.2.1 Neuroimaging Technologies
- 5.2.2 In-Vitro Diagnostics
- 5.2.3 Neuroinformatics & AI Analytics Platforms
- 5.3 By Condition
- 5.3.1 Neurodegenerative Diseases
- 5.3.2 Cerebrovascular Disorders
- 5.3.3 Epilepsy & Seizure Disorders
- 5.3.4 Sleep Disorders
- 5.3.5 Headache & Migraine
- 5.3.6 Others (TBI, CNS Infections, Tumors)
- 5.4 By End User
- 5.4.1 Hospitals & Surgical Centers
- 5.4.2 Diagnostic Laboratories & Imaging Centers
- 5.4.3 Ambulatory Care & Emergency Settings
- 5.4.4 Research & Academic Institutes
- 5.4.5 Specialized Neurology Centers
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Siemens Healthineers
- 6.3.2 GE Healthcare
- 6.3.3 Koninklijke Philips N.V.
- 6.3.4 Canon Medical Systems Corporation
- 6.3.5 Fujifilm Holdings Corporation
- 6.3.6 Thermo Fisher Scientific Inc.
- 6.3.7 Hoffmann-La Roche Ltd.
- 6.3.8 Natus Medical Incorporated
- 6.3.9 Nihon Kohden Corporation
- 6.3.10 Lifelines Neuro Company
- 6.3.11 Advanced Brain Monitoring Inc.
- 6.3.12 Mitsar Co. Ltd.
- 6.3.13 Medtronic Plc
- 6.3.14 Abbott Laboratories
- 6.3.15 Boston Scientific Corporation
- 6.3.16 Cadwell Industries Inc.
- 6.3.17 Compumedics Limited
- 6.3.18 Electrical Geodesics Inc.
- 6.3.19 Neurosoft
- 6.3.20 Masimo Corporation
- 6.3.21 Quanterix Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

