PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114738

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114738
Medical Imaging Phantoms - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the medical imaging phantoms market size is expected to grow from USD 206.06 million in 2025 to USD 215.32 million in 2026 and is forecast to reach USD 268.02 million by 2031 at 4.49% CAGR over 2026-2031.
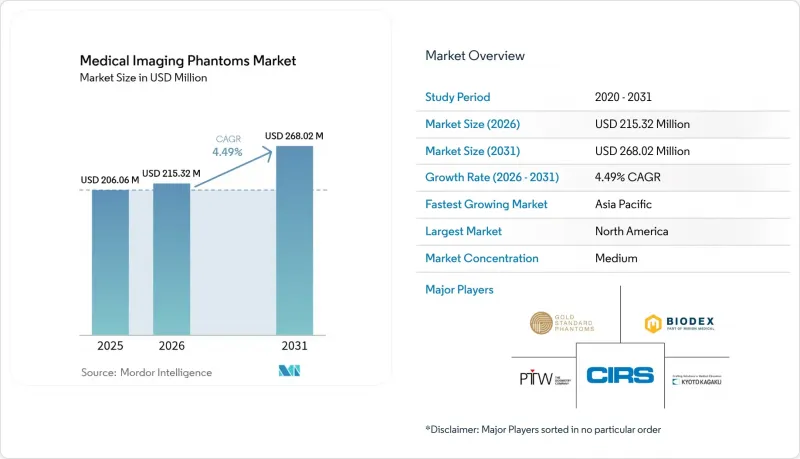
This report is Segmented by Product Type (X-Ray Phantoms, CT Phantoms, Ultrasound Phantoms, MRI Phantoms, Nuclear Imaging Phantoms, and Others), Material (Stimulating Devices, False Organs (Anthropomorphic) and Other Materials), End User (Hospitals, Diagnostic Imaging Centers, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Imaging Phantoms Market Trends and Insights
Escalating QA-Stringency of Value-Based Reimbursement Programs
Mandatory CT phantom assessments that the Centers for Medicare & Medicaid Services will enforce from 2027 convert test objects from best-practice accessories into core compliance tools. The American College of Radiology ARCH-AI framework further embeds standardized phantom runs into AI validation workflows, tying algorithm reliability to phantom-verified metrics. Health systems now regard phantom purchases as revenue-protection spend, not discretionary outlays, anchoring the medical imaging phantoms market. Quality-based bonus pools in Medicare Advantage plans intensify uptake by rewarding documented imaging consistency.
Surging Adoption of 3-D Printed, Modality-Agnostic Phantoms
Additive manufacturing delivers patient-specific replicas within 0.1 mm geometric tolerance, while new PLA-PCL blends maintain CT, MRI, and ultrasound contrast in a single build. NIH support for an Industry-University Cooperative Research Center focused on optical imaging phantoms signals sustained federal backing. Production of complex anthropomorphic units now costs under USD 250 and finishes in days instead of months. Hybrid PET/MR and photoacoustic systems that need multi-energy calibration spur developers to design modality-agnostic phantoms, broadening the global medical imaging phantoms market footprint. The lower entry price of desktop stereolithography printers also empowers mid-tier radiology groups to fabricate on-site, shortening procurement cycles.
Capital-Intensive Custom Phantom Prototyping
Developing a patient-specific anthropomorphic phantom can exceed USD 50,000 due to imaging, segmentation, multi-material printing, and validation costs. Small suppliers find it difficult to recoup expenses in niche modalities, leading to consolidation and slower innovation. Academic teams often improvise do-it-yourself kits that vary in performance, undermining cross-site comparability. This capital barrier curbs the medical imaging phantoms market expansion in subspecialty domains.
Other drivers and restraints analyzed in the detailed report include:
- Rising Installation of Hybrid PET/CT & PET/MR Scanners
- AI-Enabled Auto-QA Workflows Cutting Test-Cycle Time
- Scarcity of Elastography-Grade Tissue-Mimicking Polymers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
X-ray phantoms held 38.72% of the medical imaging phantoms market in 2025, a testament to mammography regulations that mandate routine test object scanning. Demand remains stable because the global installed base of digital radiography rooms vastly exceeds that of other modalities. The CT segment is picking up at a 6.14% CAGR as new dose-monitoring rules take effect, reflecting how evolving regulatory frameworks continuously reshape the medical imaging phantoms market size for slice-based imaging.
Manufacturers innovate with combination phantoms that house X-ray and CT inserts in one shell, lowering inventory requirements for smaller clinics. Ultrasound phantom makers focus on elastography features to match clinical expansion into liver, thyroid, and musculoskeletal assessments. MRI phantom demand remains uneven as helium supply challenges stall scanner installations, although quantitative imaging biomarkers spur interest in diffusion and T1/T2 calibration sets. Nuclear medicine phantoms chart steady orders tied to theranostic growth, where precise dosimetry becomes standard of care.
Complete Report Scope:
- By Product Type
- X-ray Phantoms
- CT Phantoms
- Ultrasound Phantoms
- MRI Phantoms
- Nuclear Imaging Phantoms
- Others
- By Material
- Stimulating Devices
- False Organs (Anthropomorphic)
- Other Materials
- By End User
- Hospitals
- Diagnostic Imaging Centers
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America dominated with 36.74% of the medical imaging phantoms market in 2025, reflecting stringent FDA equipment performance rules and a dense imaging center network that completes frequent QA cycles. Hospitals invest in AI-linked phantoms to align with the ARCH-AI program, anchoring replacement demand. Government quality incentives compensate for higher labor costs, preserving healthy margins for suppliers.
Asia Pacific is the fastest-growing region at a 6.05% CAGR, supported by large-scale hospital build-outs and the transition of provincial centers to digital imaging. China funds hybrid PET/MR rollouts that need complex multimodality phantoms, while India's National Accreditation Board for Testing mandates documented QA before licensure. Local manufacturing clusters in Shenzhen and Osaka lower import duties, yet premium inserts still rely on U.S. and European sources, sustaining international trade flows in the medical imaging phantoms market.
Europe posts steady gains as the Medical Device Regulation enforces traceability for QA accessories. Germany and the United Kingdom lead R&D partnerships that develop bio-resorbable phantom materials, while Scandinavian clinics pioneer remote phantom monitoring linked to centralized physics hubs. Middle East and Africa register emerging demand as Gulf hospitals position themselves as regional medical tourism centers, raising imaging quality benchmarks. South America grows more slowly due to fiscal constraints, although niche orders rise in Brazil's private oncology sector.
- Bartec Technologies
- Biodex Medical Systems
- Carville
- Computerized Imaging Reference Systems (CIRS)
- Gold Standard Phantoms
- Kyoto Kagaku
- Leeds Test Objects
- Modus Medical Devices
- PTW Freiburg
- Pure Imaging Phantoms
- QUART
- True Phantom Solutions
- Dielectric Corporation
- The Phantom Laboratory
- QRM GmbH
- Capintec
- Radcal
- PhantomX
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating QA-stringency of value-based reimbursement programs
- 4.2.2 Surging adoption of 3-D printed, modality-agnostic phantoms
- 4.2.3 Rising installation of hybrid PET/CT & PET/MR scanners
- 4.2.4 Expanding radiology capacity in ambulatory imaging centers
- 4.2.5 AI-enabled auto-QA workflows cutting test-cycle time
- 4.2.6 Growing grant funding for photo-acoustic tomography validation
- 4.3 Market Restraints
- 4.3.1 Capital-intensive custom phantom prototyping
- 4.3.2 Scarcity of elastography-grade tissue-mimicking polymers
- 4.3.3 Limited physicist bandwidth for advanced QA protocols
- 4.3.4 Supply-chain volatility for high-purity radioactive gels
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 X-ray Phantoms
- 5.1.2 CT Phantoms
- 5.1.3 Ultrasound Phantoms
- 5.1.4 MRI Phantoms
- 5.1.5 Nuclear Imaging Phantoms
- 5.1.6 Others
- 5.2 By Material
- 5.2.1 Stimulating Devices
- 5.2.2 False Organs (Anthropomorphic)
- 5.2.3 Other Materials
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Diagnostic Imaging Centers
- 5.3.3 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Bartec Technologies
- 6.3.2 Biodex Medical Systems
- 6.3.3 Carville
- 6.3.4 Computerized Imaging Reference Systems (CIRS)
- 6.3.5 Gold Standard Phantoms
- 6.3.6 Kyoto Kagaku
- 6.3.7 Leeds Test Objects
- 6.3.8 Modus Medical Devices
- 6.3.9 PTW Freiburg
- 6.3.10 Pure Imaging Phantoms
- 6.3.11 QUART GmbH
- 6.3.12 True Phantom Solutions
- 6.3.13 Dielectric Corporation
- 6.3.14 The Phantom Laboratory
- 6.3.15 QRM GmbH
- 6.3.16 Capintec
- 6.3.17 Radcal
- 6.3.18 PhantomX
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

