PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114752

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114752
Photocatalyst - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the photocatalyst market size is expected to grow from USD 2.96 billion in 2025 to USD 3.22 billion in 2026 and is forecast to reach USD 4.87 billion by 2031 at 8.66% CAGR over 2026-2031.
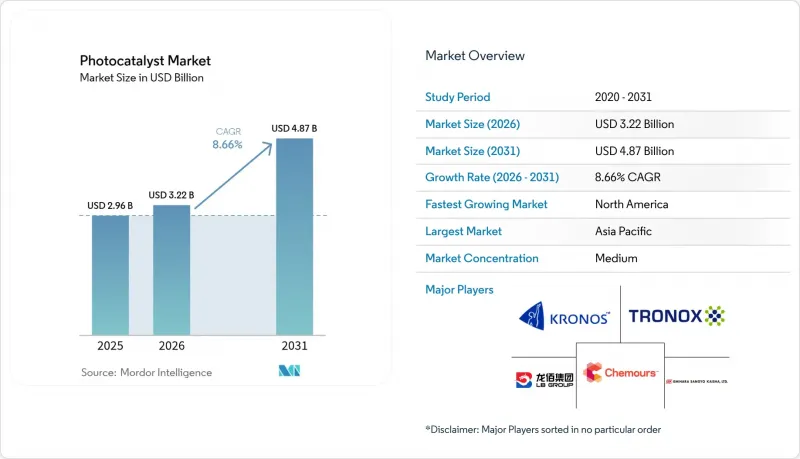
This report is Segmented by Type (Titanium Dioxide, Zinc Oxide, and Other Types), Application (Self-Cleaning, Air Purification, Water Treatment, Anti-Fogging, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Report Offers Market Size and Forecast for Photocatalyst in Value (USD Million) for all the Above Segments.
Global Photocatalyst Market Trends and Insights
Surging Demand for TiO2 Photocatalysts in Self-Cleaning Construction Materials
Building owners now specify nano-textured TiO2 coatings that cut facade washing expenses by as much as 40% across a building's life. Recent formulations achieve 95% optical transmittance, meeting the aesthetic needs of high-profile glass architecture. Photocatalytic surfaces also remove 63% of airborne toluene under daylight, easing urban air-quality concerns. High-rise projects adopt these coatings because rope-access cleaning is expensive and disruptive, while novel Bi@Bi4Ti3O12/TiO2 films extend the benefit to visible light, broadening design freedom for shaded elevations.
Rising Adoption in Municipal Water & Wastewater Treatment Plants
Utilities turn to solar-driven photocatalytic tertiary treatment to tackle pesticides such as 2,4-D, MCPP and dicamba, achieving up to 99.8% degradation without external power. Photocatalytic membrane reactors gain traction for their precise effluent quality control and resilience to contaminant peaks. Additive-manufactured composite structures push costs down by customizing surface area and light-distribution geometry, making remote installations viable where grid electricity is scarce.
High Capital Expenditure for Industrial-Scale Photocatalytic Reactors
Economic modeling shows treatment costs spike when reaction rate constants fall below 0.1 min-1, pushing developers to cut catalyst price rather than over-engineer reactors. UV-lamp arrays, precision flow control and fouling mitigation further inflate capex, often pushing projects 3-5 times above initial budgets. Modular units and hybrid photo-bioreactors emerge as workable answers, spreading investment over time and keeping payback within acceptable 5-15 year windows where energy prices and water-quality mandates align.
Other drivers and restraints analyzed in the detailed report include:
- Stricter Indoor-Air VOC Regulations Boosting Photocatalytic Air Purifiers
- Visible-Light Plasmonic Nanocomposites Enabling Indoor Consumer-Electronics Coatings
- Catalyst Deactivation from Surface Fouling & Electron-Hole Recombination
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, TiO2 held 61.45% of photocatalyst market share owing to mature production scale and decades of formulation know-how. Concurrent advances such as Ti3+ self-doping via triethanolamine routes widen its visible-light window, reinforcing performance leadership even as antidumping duties change supply logistics. ZnO meanwhile posts the fastest 9.55% CAGR because its surface reaction pathway favors hydrogen generation, an area receiving generous green-fuel funding across Asia-Pacific and North America.
Momentum is nonetheless shifting toward multi-component systems. Bismuth-oxides, graphene composites and MOF-derived structures demonstrate quantum yields above 10%, targeting CO2 conversion and specialty chemical synthesis. Market selection is expected to tilt on application specificity more than on universal metrics, suggesting TiO2 might relinquish some high-margin niches even while retaining overall volume leadership in the photocatalyst market.
Complete Report Scope:
- By Photocatalyst Type
- Titanium Dioxide
- Zinc Oxide
- Other Types
- By Application
- Self-Cleaning
- Air Purification
- Water Treatment
- Anti-Fogging
- Other Applications
- By End-Use Industry
- Construction and Infrastructure
- Automotive and Transportation
- Consumer Electronics and Appliances
- Energy and Utilities (Solar, Hydrogen)
- Other End-user Industries (Healthcare and Hygiene, Agriculture and Aquaculture)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific maintained 66.15% share in 2025 as Japan's research leadership and China's low-cost TiO2 output anchor a vertically integrated cluster from laboratory to factory floor. Post-Fukushima R&D grants propel visible-light innovation, and China's scale-2.65 million tons TiO2 via the sulphate route in 2017-supports price competitiveness even amid tightening environmental rules. Rapid urbanisation and seasonal smog further drive municipal demand for photocatalytic air-scrubbed facades and subway stations.
North America expands fastest at a 9.62% CAGR thanks to EPA VOC limits that accelerate HVAC retrofits and automotive fuel-vapor controls. Municipal utilities implement passive solar tertiary treatment to meet trace-contaminant discharge permits, while federal clean-hydrogen credits stimulate ZnO-based water-splitting demonstrations. Canadian green building codes and Mexico's expanding industrial base add regional volume beyond the United States.
Europe benefits from the Green Deal's circular-economy clauses, channelling subsidies into sustainable construction and agrivoltaic pilots that pair photocatalytic glazing with transparent PV. Antidumping tariffs on Chinese TiO2 galvanise local pigment makers to diversify into higher-margin catalyst grades, thereby shortening supply chains. South America and Middle East & Africa represent early-stage arenas where point-of-use water treatment and solar-panel coatings can leapfrog conventional solutions, especially in remote agriculture and mining camps.
- BASF
- Daicel Miraizu Ltd.
- Green Millennium, Inc.
- ISHIHARA SANGYO KAISHA, LTD.
- KRONOS Worldwide Inc.
- LB Group
- Nanoptek Corp.
- NIPPON SODA CO., LTD.
- Resonac Holdings Corporation
- TAYCA Co., Ltd.
- The Chemours Company
- TitanPE Technologies, Inc.
- Tronox Holdings PLC
- Venator Materials PLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for titanium dioxide photocatalysts in self-cleaning construction materials
- 4.2.2 Rising adoption in municipal water & wastewater treatment plants
- 4.2.3 Stricter indoor-air VOC regulations boosting photocatalytic air purifiers
- 4.2.4 Visible-light plasmonic nanocomposites enabling indoor consumer-electronics coatings
- 4.2.5 Photocatalytic coatings for agrivoltaic glass reducing bio-fouling
- 4.3 Market Restraints
- 4.3.1 High capital expenditure for industrial-scale photocatalytic reactors
- 4.3.2 Catalyst deactivation from surface fouling & electron-hole recombination
- 4.3.3 Regulatory uncertainty on nanoparticle release & disposal
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Photocatalyst Type
- 5.1.1 Titanium Dioxide
- 5.1.2 Zinc Oxide
- 5.1.3 Other Types
- 5.2 By Application
- 5.2.1 Self-Cleaning
- 5.2.2 Air Purification
- 5.2.3 Water Treatment
- 5.2.4 Anti-Fogging
- 5.2.5 Other Applications
- 5.3 By End-Use Industry
- 5.3.1 Construction and Infrastructure
- 5.3.2 Automotive and Transportation
- 5.3.3 Consumer Electronics and Appliances
- 5.3.4 Energy and Utilities (Solar, Hydrogen)
- 5.3.5 Other End-user Industries (Healthcare and Hygiene, Agriculture and Aquaculture)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 BASF
- 6.4.2 Daicel Miraizu Ltd.
- 6.4.3 Green Millennium, Inc.
- 6.4.4 ISHIHARA SANGYO KAISHA, LTD.
- 6.4.5 KRONOS Worldwide Inc.
- 6.4.6 LB Group
- 6.4.7 Nanoptek Corp.
- 6.4.8 NIPPON SODA CO., LTD.
- 6.4.9 Resonac Holdings Corporation
- 6.4.10 TAYCA Co., Ltd.
- 6.4.11 The Chemours Company
- 6.4.12 TitanPE Technologies, Inc.
- 6.4.13 Tronox Holdings PLC
- 6.4.14 Venator Materials PLC
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

