PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114753

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114753
Spiral Membrane - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the spiral membrane market size was valued at USD 7.45 billion in 2025 and estimated to grow from USD 8.3 billion in 2026 to reach USD 14.28 billion by 2031, at a CAGR of 11.48% during the forecast period (2026-2031).
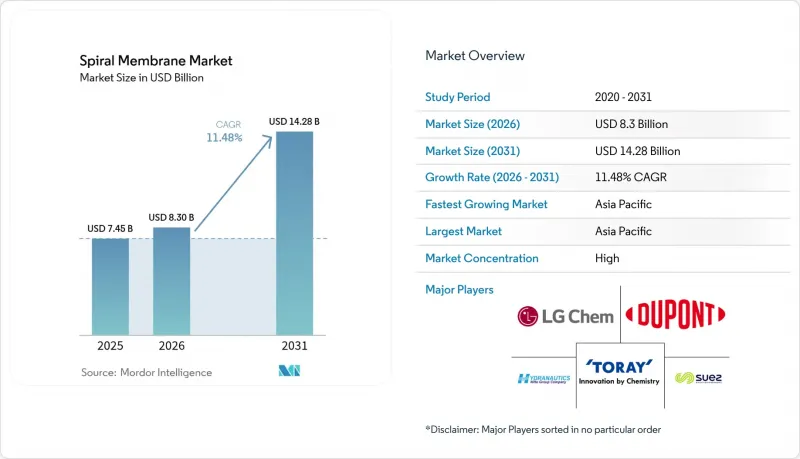
This report is Segmented by Polymer Material (Polyamide (TFC), Polyethersulfone (PES), and More), Separation Technique (Microfiltration, Ultrafiltration, and More), End-User Industry (Municipal Water Treatment, Food and Beverage, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Spiral Membrane Market Trends and Insights
Expanding Food and Beverage Protein-Fractionation Needs
Dairy processors and juice bottlers are migrating from thermal concentration to membrane fractionation so they can produce value-added protein isolates that sell at 40-60% price premiums. Modern spiral-wound microfiltration lines separate whey proteins with 99% efficiency while preserving functional properties, allowing manufacturers to serve sports-nutrition, medical-nutrition, and infant-formula channels. Recent spacer redesigns lift cross-flow velocity, which suppresses fouling and stretches run times between cleanings. Plant managers also appreciate the smaller footprint; spiral modules pack two to three times more surface area than equivalent hollow-fiber units, lowering civil-work costs.
Shift from Hollow-Fiber to High-Flux Spiral-Wound Modules
Industrial water operators notice that spiral-wound designs deliver up to three-fold higher packing density than hollow-fiber counterparts, enabling smaller skids and lower replacement costs. Cleaning protocols also improve: new feed-spacer geometries enhance turbulence, reducing chemical use. These benefits are decisive in viscous streams such as dairy, sugar, and gelatin, where hollow-fiber membranes foul rapidly.
Membrane Fouling and Cleaning-Chemical Costs
Across Dutch desalination plants, cleaning accounts for 24% of RO operating expenses. Biofouling shortens membrane life, especially in polyamide elements that cannot tolerate free chlorine. Developers are coating surfaces with zwitterionic polymers and leveraging pulsed-flow cleaning to cut chemical use in half. Until these tools mature, elevated cleaning and downtime costs will temper adoption in heavily bio-active streams.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Hot-Sanitizable Spiral Membranes in Bioprocessing
- Stricter Industrial and Municipal Wastewater Discharge Norms
- High Energy/Pressure Demand for RO Operations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyamide thin-film composites retained a 42.58% spiral membrane market share in 2025, propelled by decades of performance optimization in desalination where 99.5% salt rejection is routine. PES holds niche utility in bioprocessing because it withstands repeated steam cycles. Fluoropolymers such as PVDF and PTFE, though only a small slice today, are on track to grow 12.34% annually, capturing opportunities in lithium brine, semiconductor, and aggressive-solvent streams. These chemistries tolerate pH 0-14 and temperatures to 120 °C, features that justify premium pricing. Surface-activation techniques-plasma etching, UV grafting-now overcome their intrinsic hydrophobicity, pushing water flux toward polyamide territory.
The polyamide segment draws strength from mature supply chains and competitive pricing, but its chlorine sensitivity restricts reuse after fouling events, nudging operators toward fluoropolymer retrofits. Ceramic and composite designs populate extreme environments such as produced-water clean-up, where uptime outweighs capital intensity. They represent a small yet strategic fragment of the spiral membrane market size for specialty chemicals and mining services.
Complete Report Scope:
- By Polymer Material
- Polyamide (TFC)
- Polyethersulfone (PES)
- Fluoropolymers (PTFE, PVDF)
- Others (Cellulose Acetate, Ceramic, Composite)
- By Separation Technique
- Microfiltration (MF)
- Ultrafiltration (UF)
- Nanofiltration (NF)
- Reverse Osmosis (RO)
- By End-user Industry
- Municipal Water Treatment
- Food and Beverage
- Healthcare
- Oil and Gas
- Others (Chemicals, Pulp and Paper, Mining, Power, Textiles)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia and New Zealand
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia Pacific commands the largest slice of spiral membrane market share at 33.74% in 2025, and its 12.63% CAGR through 2031 outpaces all other regions. Environmental enforcement now compels Chinese factories to install advanced membranes, while India funnels public funds into municipal upgrades under schemes such as the Jal Jeevan Mission. Semiconductor fabs in Taiwan, Japan, and South Korea require ultra-pure water below 5 ppt total organic carbon, pushing demand for high-selectivity RO and UF stacks. Australia leans on spiral-wound RO to secure potable water for cities facing protracted drought.
North America is the second-largest consumer as the Infrastructure Investment and Jobs Act channels USD 55 billion into water-system modernization. Aging RO trains from the early-2000s are being swapped for high-permeability designs that cut energy 20-25%. Market activity centers on upgrading PFAS removal and industrial reuse. Mexico's automotive corridor invests in zero-liquid-discharge, boosting local spiral membrane imports.
Europe maintains strict effluent norms under the Water Framework Directive, spurring retrofits across food, beverage, and pharmaceutical plants. Scandinavian utilities pilot PFAS-targeted nanofiltration, while southern states deploy seawater desalination to offset prolonged drought. Suppliers see healthy aftermarket sales as operators adhere to energy-efficiency and circular-economy targets.
Latin American demand concentrates in mining hubs. Chile and Argentina fit spiral nanofiltration for lithium salars, extracting battery-grade feedstock while recycling brine. Brazil's pulp-and-paper mills adopt RO for closed-loop bleaching circuits, trimming chemical oxygen demand discharges by 85%. The Middle East and North Africa emphasize megascale RO plants where state utilities explore energy-recovery devices to offset power constraints. Sub-Saharan Africa's uptake remains low but climbs as multilateral lenders finance sewage-reuse projects in water-scarce cities.
- Alfa Laval
- Asahi Kasei Corporation
- AXEON Water
- DuPont
- Hydranautics (Nitto)
- IDE Technologies
- Koch Separation Solutions
- Lanxess
- LG Chem
- MANN+HUMMEL
- Membranium (JSC RM Nanotech)
- Merck KgaA
- Pall Corporation
- Pentair PLC
- Synder Filtration, Inc
- SUEZ
- Toray Industries Inc
- Toyobo Co., Ltd
- Veolia
- Xylem
- ZwitterCo.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding food and beverage protein-fractionation needs
- 4.2.2 Stricter industrial and municipal wastewater discharge norms
- 4.2.3 Shift from hollow-fiber to high-flux spiral-wound modules
- 4.2.4 Adoption of hot-sanitizable spiral membranes in bioprocessing
- 4.2.5 Lithium-brine concentration via spiral Nano Filtration in battery supply chain
- 4.3 Market Restraints
- 4.3.1 Membrane fouling and cleaning-chemical costs
- 4.3.2 High energy/pressure demand for RO operations
- 4.3.3 Volatile pricing of ultra-pure polyamide casting films
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Polymer Material
- 5.1.1 Polyamide (TFC)
- 5.1.2 Polyethersulfone (PES)
- 5.1.3 Fluoropolymers (PTFE, PVDF)
- 5.1.4 Others (Cellulose Acetate, Ceramic, Composite)
- 5.2 By Separation Technique
- 5.2.1 Microfiltration (MF)
- 5.2.2 Ultrafiltration (UF)
- 5.2.3 Nanofiltration (NF)
- 5.2.4 Reverse Osmosis (RO)
- 5.3 By End-user Industry
- 5.3.1 Municipal Water Treatment
- 5.3.2 Food and Beverage
- 5.3.3 Healthcare
- 5.3.4 Oil and Gas
- 5.3.5 Others (Chemicals, Pulp and Paper, Mining, Power, Textiles)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN
- 5.4.1.6 Australia and New Zealand
- 5.4.1.7 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Alfa Laval
- 6.4.2 Asahi Kasei Corporation
- 6.4.3 AXEON Water
- 6.4.4 DuPont
- 6.4.5 Hydranautics (Nitto)
- 6.4.6 IDE Technologies
- 6.4.7 Koch Separation Solutions
- 6.4.8 Lanxess
- 6.4.9 LG Chem
- 6.4.10 MANN+HUMMEL
- 6.4.11 Membranium (JSC RM Nanotech)
- 6.4.12 Merck KgaA
- 6.4.13 Pall Corporation
- 6.4.14 Pentair PLC
- 6.4.15 Synder Filtration, Inc
- 6.4.16 SUEZ
- 6.4.17 Toray Industries Inc
- 6.4.18 Toyobo Co., Ltd
- 6.4.19 Veolia
- 6.4.20 Xylem
- 6.4.21 ZwitterCo.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

