PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114777

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114777
Global Surgical Clips - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the surgical clips market size is expected to grow from USD 604.73 million in 2025 to USD 636.23 million in 2026 and is forecast to reach USD 820.69 million by 2031 at 5.21% CAGR over 2026-2031.
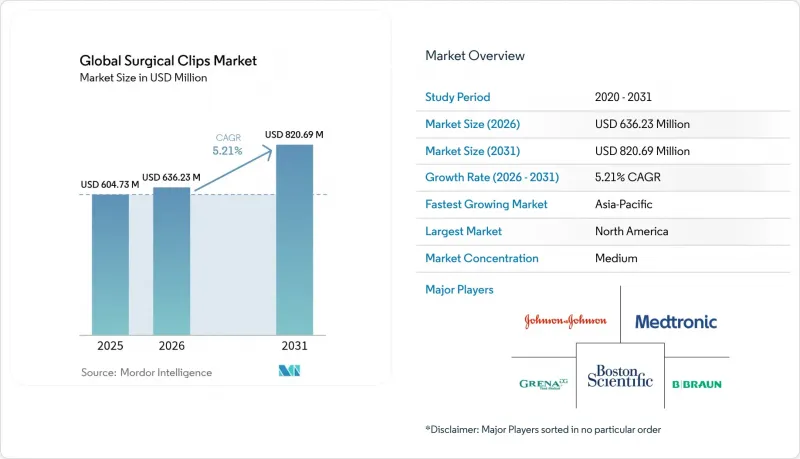
This report is Segmented by Device Type (Ligating Clips, Aneurysm Clips, and Other Types), Material (Titanium, Polymer, and Other Materials), Surgery Type (Automated Surgery Clips and Manual Surgery Clips), End-User (Hospitals and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Surgical Clips Market Trends and Insights
Increase in surgical procedures worldwide
Steady growth in hernia, orthopedic, and bariatric interventions lifts procedural volume and directly drives the surgical clips market. Hernia repairs alone are expected to rise 19.7% by 2050 to 1.72 million new cases every year. Ambulatory settings report double-digit gains in hip and knee work that depend on quick, reliable vessel ligation. Robotics adoption reinforces demand as the da Vinci 5 platform applies 43% less tissue force, allowing finer clip placement for fragile structures. Growing BMI profiles and wider antithrombotic therapy amplify the need for sturdy yet atraumatic devices across specialties. The combined effect channels recurring unit sales and encourages broader clip portfolios.
Surge in global geriatric population
Median surgical age moved from 55.5 years in 2008 to 58.5 years in 2020 and is on track for 61.5 years by 2030. Older candidates present comorbid diabetes and vascular fragility that heighten bleeding risk, making secure clipping essential. Titanium remains a staple, yet polymer lines gain acceptance because they avoid metal allergies and reduce postoperative imaging artifacts. Providers also adopt applicators with low-profile jaws that suit calcified or delicate tissue common in older adults. As payers tie reimbursement to complication rates, dependable clip performance in geriatric cohorts becomes a purchasing priority and sustains momentum for the surgical clips market.
Clip migration and bile-duct or vascular complications
More than 100 documented cases link delayed cholecystectomy clip migration to serious biliary events that sometimes surface decades after surgery. Hem-o-lok polymer variants and legacy metals alike appear in reports, signaling a design-agnostic risk. Average migration occurs 26 months post-procedure, leading to costly ERCP retrievals and feeding both surgeon caution and regulatory vigilance. Awareness forces clinicians to limit clip counts, explore alternative sealants, and demand better applicator precision, temporarily tempering growth in the surgical clips market.
Other drivers and restraints analyzed in the detailed report include:
- Rising healthcare expenditure and access to MIS
- Shift toward MRI-compatible polymer or absorbable clips
- Adoption of robotic staplers and energy sealing devices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ligating devices generated the largest contribution to the surgical clips market in 2025, reflecting their 64.33% share in routine laparoscopic and open work. Unit demand remains high for cholecystectomy, colorectal, and general abdominal procedures that rely on quick vessel closure. Uptake persists in lower-resource settings, ensuring stable baseline volumes and reinforcing market resilience.
Aneurysm clips, although smaller in revenue today, grow fastest at 5.88% CAGR as neurovascular caseloads climb with an aging population. Silicon-nitride and zirconia ceramics demonstrate superior closing force without jaw crossing, giving neurosurgeons MRI-safe options for complex locations. Manufacturers bundle these clips with micro-applicators that fit narrow surgical windows, creating premium niches inside the wider surgical clips market. Continuous R&D into jaw geometry and spring metallurgy improves long-term patency and supports broader adoption.
Titanium held 67.55% of segment revenue in 2025 thanks to decades of clinical proof and surgeon familiarity. Its strength-to-weight ratio and inert surface limit tissue reaction, providing dependable performance for diverse procedures. Hospitals continue large-scale buying due to streamlined sterilization and bulk pricing arrangements.
Polymer lines register 5.54% CAGR through 2031 as clinicians pursue MRI clarity and avoid metal allergies. Studies record USD 75 savings per case when switching from metal to polymer clips while maintaining comparable complication profiles. Biodegradable magnesium-titanium hybrids emerge in research pipelines and could remove post-healing foreign bodies altogether. As imaging protocols tighten and patient allergy testing rises, polymer and hybrid shares will likely advance, diversifying the surgical clips market.
Complete Report Scope:
- By Device Type
- Ligating Clips
- Aneurysm Clips
- Other Types
- By Material
- Titanium
- Polymer
- Other Materials
- By Technology
- Automated Surgery Clips
- Manual Surgery Clips
- By End-User
- Hospitals
- Ambulatory Surgery Centers
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 41.21% of the surgical clips market share in 2025, sustained by high procedure counts, broad insurance coverage, and rapid adoption of MRI-compatible lines. Surgical spending is set to hit 7.3% of GDP by 2025, supporting premium procurement and keeping the surgical clips market vibrant in the region. FDA quality-system reforms, effective in 2026, further encourage manufacturers to invest in advanced materials.
Asia-Pacific is the fastest-expanding region for the surgical clips market, with a 5.98% CAGR. Rising incomes and health-insurance penetration in China, India, and Southeast Asia push higher elective surgery counts. Domestic makers supply cost-advantaged titanium options, while high-tier urban centers import polymer and automated systems. Government investments in surgical robotics and hospital infrastructure strengthen regional demand through the forecast period.
Europe posts a 4.91% CAGR on the back of aging demographics and rigorous device oversight. Hospitals in Germany, France, and the Nordics value traceability and imaging safety, helping polymer and biodegradable lines gain traction. Group purchasing across national systems steers consistent adoption, while local innovators refine ceramic aneurysm clips that meet stringent MRI guidelines. The Middle East and Africa grow 5.73% as Gulf states channel oil revenue into state-of-the-art surgical suites that prefer premium polymer sets. Emerging sub-Saharan markets focus on affordable manual titanium solutions yet still post rising volumes thanks to expanding urban hospitals. South America advances 5.37% under Brazil and Argentina's public-private partnerships that enhance access to MIS.
- Ackermann Instrumente
- Applied Medical Resources
- B. Braun
- Boston Scientific
- Conmed
- Cook Group
- Edward Lifesciences
- Grena Limited
- Hangzhou Boer Medical
- Johnson & Johnson
- Kangji Medical
- LeMaitre Vascular
- Medtronic
- Meril Life Sciences
- Olympus
- Scanlan International
- Stapleline Medizintechnik
- Stryker
- Teleflex
- XNY Medical Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increase in surgical procedures worldwide
- 4.2.2 Surge in global geriatric population
- 4.2.3 Rising healthcare expenditure & access to MIS
- 4.2.4 Shift toward MRI-compatible polymer/absorbable clips
- 4.2.5 Regulatory push for single-use sterile ligation devices
- 4.2.6 Proliferation of hybrid operating rooms
- 4.3 Market Restraints
- 4.3.1 Clip migration & bile-duct/vascular complications
- 4.3.2 Adoption of robotic staplers & energy sealing devices
- 4.3.3 Titanium allergy & slippage safety alerts (ECRI)
- 4.3.4 Limited demand in under-developed countries
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Device Type
- 5.1.1 Ligating Clips
- 5.1.2 Aneurysm Clips
- 5.1.3 Other Types
- 5.2 By Material
- 5.2.1 Titanium
- 5.2.2 Polymer
- 5.2.3 Other Materials
- 5.3 By Technology
- 5.3.1 Automated Surgery Clips
- 5.3.2 Manual Surgery Clips
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgery Centers
- 5.4.3 Other End-Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Competitive Benchmarking
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Ackermann Medical GmbH & Co.
- 6.4.2 Applied Medical Resources
- 6.4.3 B. Braun Melsungen AG
- 6.4.4 Boston Scientific Corporation
- 6.4.5 ConMed Corporation
- 6.4.6 Cook Medical
- 6.4.7 Edwards Lifesciences Corporation
- 6.4.8 Grena Limited
- 6.4.9 Hangzhou Boer Medical
- 6.4.10 Johnson & Johnson Services, Inc.
- 6.4.11 Kangji Medical
- 6.4.12 Lemaitre Vascular Inc.
- 6.4.13 Medtronic plc
- 6.4.14 Meril Life Sciences
- 6.4.15 Olympus Corporation
- 6.4.16 Scanlan International
- 6.4.17 Stapleline Medizintechnik GmbH
- 6.4.18 Stryker Corporation
- 6.4.19 Teleflex Incorporated
- 6.4.20 XNY Medical Technology
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

