PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114788

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114788
Spinal Muscular Atrophy Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, spinal muscular atrophy treatment market size in 2026 is estimated at USD 6.06 billion, growing from 2025 value of USD 5.17 billion with 2031 projections showing USD 13.48 billion, growing at 17.33% CAGR over 2026-2031.
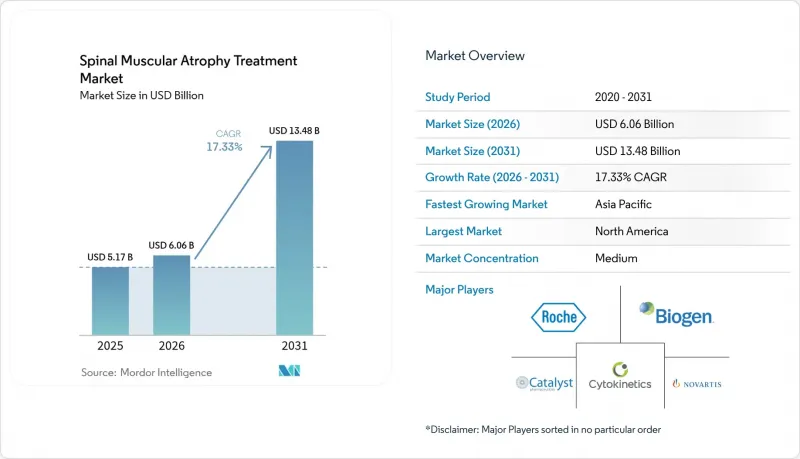
This report is Segmented by Type (Type I, Type II, Type III, and Type IV), Procedure (Gene Replacement Therapy and Drug Therapy), Route of Administration (Oral and Intrathecal), and Geography (North America, Europe, Asia-Pacific, Middle-East and Africa, and South America). The Report Offers the Value (in USD Million) for the Above Segments.
Global Spinal Muscular Atrophy Treatment Market Trends and Insights
Newborn Screening Mandates Expand Treatable Patient Pool
Nationwide screening now active across all US states since January 2024 identifies SMA at a presymptomatic stage, enabling optimal timing for high-impact therapies. Taiwan, Hungary, and Serbia followed similar rollouts and collectively screened more than 650,000 infants, highlighting scalability across varied health systems . Screening detects roughly 1 in 14,694 newborns, generating a predictable annual cohort that sustains therapy demand. Early detection translates into markedly improved motor outcomes, reinforcing payer willingness to reimburse expensive treatments. The practice also supplies essential epidemiological data that refine capacity planning for infusion centers and specialty pharmacies.
Rapid Uptake of SMN-Targeting Gene Therapies in High-Income Markets
SMN-targeting therapeutics now span antisense oligonucleotides, gene replacement vectors, and small-molecule splicing modifiers, offering clinicians multiple paths to restore SMN protein levels. Nusinersen dose-escalation showed a 94% reduction in plasma neurofilament light chain, supporting the clinical rationale for higher loading doses. Roche's February 2025 tablet approval further lowers treatment burden without compromising exposure. Novartis achieved a 2.39-point HFMSE gain in older children using intrathecal onasemnogene abeparvovec, broadening gene-therapy eligibility. Together, these advances shorten the adoption curve and amplify the revenue base of the spinal muscular atrophy treatment market.
Million-Dollar Price Tags and Uncertain Long-Term Reimbursement
Zolgensma's multi-million-dollar cost and a lifetime efficacy horizon strain payer budgets, especially in middle-income countries. Incremental cost-effectiveness ratios remain above traditional thresholds, prompting risk-sharing arrangements that delay uptake. Where coverage is approved, reimbursement often includes outcomes-based milestones, adding administrative complexity and revenue deferral for manufacturers. This drag limits penetration potential despite compelling clinical benefit.
Other drivers and restraints analyzed in the detailed report include:
- Global Payer Acceptance of High-Value Rare-Disease Drugs
- Rising Advocacy-Group Funding for Early-Stage Trials
- Intrathecal Delivery Complexities and Capacity Constraints at Infusion Centers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Type 1 SMA retained 48.05% share of the spinal muscular atrophy treatment market in 2025. Its life-threatening nature prompts immediate therapy initiation and supports premium pricing. Universal newborn screening has shifted diagnoses into the presymptomatic stage, improving ventilatory-free survival and reinforcing clinical consensus for early gene therapy use. Type 0, historically excluded from trials, now logs an 18.02% CAGR as regulatory guidance broadens eligibility criteria and compassionate-use precedents confirm safety. Types 2 and 3 generate steady, recurring revenue because lifelong maintenance dosing remains standard practice. Type 4 adult-onset cases remain a niche today but grow as awareness climbs.
Presymptomatic treatment markedly improves motor milestones for Type 1 patients, evidenced by Taiwanese screen-and-treat cohorts achieving independent sitting in 100% of gene-therapy recipients. Later-onset groups experience slower but durable gains, supporting chronic therapy continuation. Variations in disease severity influence modality choice: gene replacement is favored in Type 1, while SMN2 splicing modifiers and antisense oligonucleotides dominate Types 2-4 due to flexible dosing and straightforward logistics.
SMN2 splicing modifiers commanded 42.35% of the spinal muscular atrophy treatment market share in 2025. Competitive advantages include pan-phenotype eligibility, oral or intrathecal options, and favorable safety records. Gene-replacement therapy shows the fastest 18.41% CAGR as manufacturing yields improve and intrathecal formulations remove weight caps for older children. Antisense oligonucleotides hold steady with dose-escalation protocols, boosting neurofilament clearance metrics.
Muscle-directed agents such as apitegromab promise synergistic benefits when layered onto SMN-restoring backbones. Supportive therapies-ventilation aids, nutritional support, orthopedics-still feature in multidisciplinary care but shrink in revenue share as disease-modifying agents delay or prevent complications. An emerging pipeline of RNA-editing tools could eventually converge with existing modalities, sustaining innovation depth for the spinal muscular atrophy treatment market.
Complete Report Scope:
- By Disease Type
- Type 0
- Type 1
- Type 2
- Type 3
- Type 4
- By Treatment Modality
- Gene Replacement Therapy
- SMN2 Splicing Modifiers
- Antisense-Oligonucleotide Therapy
- Muscle-Directed / Myostatin Inhibitors
- Supportive & Assistive Therapies
- By Route of Administration
- Oral
- Intrathecal
- Intravenous
- By Age Group
- Neonates (0-6 mo)
- Pediatrics (6 mo-12 y)
- Adolescents (12-18 y)
- Adults (>18 y)
- By Distribution Channel
- Hospital Pharmacies
- Specialty Clinics
- Online & Retail Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 42.30% of global revenue in 2025, underpinned by exhaustive newborn screening coverage, dense neuromuscular-specialist networks, and mature payer mechanisms that accommodate six- to seven-figure price tags. The US CMS infant-screening mandate guarantees near-universal early detection, while private insurers and Medicaid programs negotiate milestone-based contracts that secure wide access. Canada's single-payer system funds risdiplam and nusinersen nationwide, yet gene-therapy reimbursement remains provincial in scope, leading to cross-border treatment outflow from western provinces to US centers. Europe shows steady incremental gains as EMA centralized approvals streamline label harmonization, but individual country negotiators stagger market entry times. Germany and France implement compulsory sickness-fund coverage for all approved SMA therapies, preserving high uptake. Conversely, Italy and Spain apply age or weight caps to gene-therapy funding, directing older children toward splicing modifiers instead. Eastern Europe accelerates newborn-screening adoption, with Serbia screening 54,000 infants within twelve months of program launch .
Asia-Pacific records the fastest 18.96% CAGR through 2031 thanks to rising health-insurance penetration, expanding molecular-diagnostics capacity, and government rare-disease lists that waive import tariffs. Japan leads on per-capita spend, screening every newborn since 2023 and funding all three SMN-targeted classes. China approved nusinersen in 2024 and included it in the NRDL formulary at a negotiated discount that accelerates provincial uptake. India's Union Health Ministry pilots state-funded screening in Kerala and Maharashtra, laying groundwork for broader scale. Australia and South Korea complete the region's high-income cluster, leveraging robust genomic labs and telehealth to reach rural patients. Collectively, these expansions add tens of thousands of eligible patients to the spinal muscular atrophy treatment market each year.
- Biogen
- Roche Holding AG (Genentech)
- Novartis
- Ionis Pharmaceuticals
- PTC Therapeutics
- Scholar Rock Inc.
- Cytokinetics
- Sarepta Therapeutics
- NMD Pharma A/S
- Astellas Pharma
- Pfizer
- Chugai Pharmaceutical
- Sanofi S.A. (Genzyme)
- Catalyst Pharmaceuticals
- Regenxbio Inc.
- Biohaven Pharmaceutical Holding Co.
- Audentes Therapeutics (Astellas Gene Therapies)
- BridgeBio Pharma Inc.
- Shionogi & Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Newborn-Screening Mandates Expand Treatable Patient Pool
- 4.2.2 Rapid Uptake Of Smn-Targeting Gene Therapies In High-Income Markets
- 4.2.3 Global Payer Acceptance Of High-Value Rare-Disease Drugs
- 4.2.4 Rising Advocacy-Group Funding For Early-Stage Trials
- 4.2.5 Pipeline Combination Regimens Targeting Smn & Myostatin
- 4.2.6 Home-Based Digital Adherence Platforms Boost Chronic Dosing
- 4.3 Market Restraints
- 4.3.1 Million-Dollar Price Tags And Uncertain Long-Term Reimbursement
- 4.3.2 Intrathecal Delivery Complexities & Capacity Constraints At Infusion Centers
- 4.3.3 Shortage Of Pediatric Neuromuscular Specialists In Emerging Economies
- 4.3.4 Viral-Vector Manufacturing Bottlenecks For Aav Supplies
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Disease Type
- 5.1.1 Type 0
- 5.1.2 Type 1
- 5.1.3 Type 2
- 5.1.4 Type 3
- 5.1.5 Type 4
- 5.2 By Treatment Modality
- 5.2.1 Gene Replacement Therapy
- 5.2.2 SMN2 Splicing Modifiers
- 5.2.3 Antisense-Oligonucleotide Therapy
- 5.2.4 Muscle-Directed / Myostatin Inhibitors
- 5.2.5 Supportive & Assistive Therapies
- 5.3 By Route of Administration
- 5.3.1 Oral
- 5.3.2 Intrathecal
- 5.3.3 Intravenous
- 5.4 By Age Group
- 5.4.1 Neonates (0-6 mo)
- 5.4.2 Pediatrics (6 mo-12 y)
- 5.4.3 Adolescents (12-18 y)
- 5.4.4 Adults (>18 y)
- 5.5 By Distribution Channel
- 5.5.1 Hospital Pharmacies
- 5.5.2 Specialty Clinics
- 5.5.3 Online & Retail Pharmacies
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Biogen Inc.
- 6.3.2 Roche Holding AG (Genentech)
- 6.3.3 Novartis International AG
- 6.3.4 Ionis Pharmaceuticals Inc.
- 6.3.5 PTC Therapeutics Inc.
- 6.3.6 Scholar Rock Inc.
- 6.3.7 Cytokinetics Inc.
- 6.3.8 Sarepta Therapeutics Inc.
- 6.3.9 NMD Pharma A/S
- 6.3.10 Astellas Pharma Inc.
- 6.3.11 Pfizer Inc.
- 6.3.12 Chugai Pharmaceutical Co., Ltd.
- 6.3.13 Sanofi S.A. (Genzyme)
- 6.3.14 Catalyst Pharmaceuticals
- 6.3.15 Regenxbio Inc.
- 6.3.16 Biohaven Pharmaceutical Holding Co.
- 6.3.17 Audentes Therapeutics (Astellas Gene Therapies)
- 6.3.18 BridgeBio Pharma Inc.
- 6.3.19 Shionogi & Co., Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

