PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114844

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114844
Hyaluronic Acid Raw Material - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the hyaluronic acid raw material market size was valued at USD 7.41 billion in 2025 and estimated to grow from USD 7.79 billion in 2026 to reach USD 10.01 billion by 2031, at a CAGR of 5.15% during the forecast period (2026-2031).
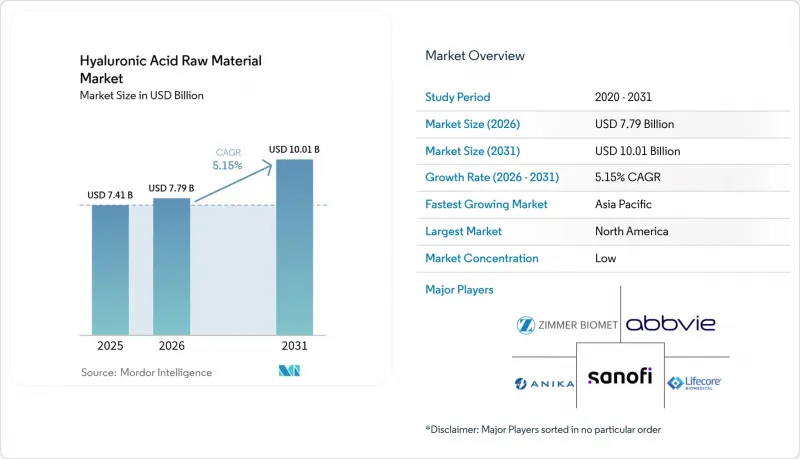
This report is Segmented by Application (Orthopedics, Ophthalmology, Drug Delivery, Dermatology/Dermal Fillers, Other Applications), End User (Hospitals, Cosmetic Clinics, Other End Users), Source (Animal-Derived, Microbial Fermentation), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Hyaluronic Acid Raw Material Market Trends and Insights
Rising Demand for Anti-Ageing and Minimally-Invasive Aesthetic Solutions
Preventative aesthetics have reshaped consumption patterns, with patients aged 25-35 accounting for one-third of new filler procedures in 2024, nearly double the 2019 level . Broader anatomical approvals such as temple augmentation with JUVEDERM VOLUMA XC increase treatment zones and elevate annual filler volumes per patient . Advanced cross-linking prolongs product residence time, permitting premium pricing that offsets reduced visit frequency. Social-media normalization of subtle refinements reduces stigma and drives procedural uptake among professionals in finance, technology, and healthcare. The net effect is a younger, recurring client base that lessens seasonal revenue swings, reinforcing a predictable growth foundation for the hyaluronic acid raw material market.
Rapid Growth of Viscosupplementation in Knee-Osteoarthritis Therapy
Viscosupplementation now serves as a cost-saving bridge delaying total knee arthroplasty by roughly 12 months, thereby lowering healthcare expenditures. Single high-molecular-weight injections have demonstrated non-inferiority to multiple low-dose regimens, cutting visit burden and boosting adherence. Expanded insurance coverage makes therapy accessible to seniors on fixed incomes, particularly in Asia-Pacific where aging demographics lift osteoarthritis prevalence. Novel formulations that combine hyaluronic acid with polynucleotides or niacinamide deliver superior pain relief, signaling a premium shift from commodity viscosupplements. Widespread adoption of ultrasound-guided protocols enhances placement precision and safety, enabling general orthopedists and rheumatologists to offer injections without referral to specialized centers.
High Product Cost and Price Volatility of Pharmaceutical-Grade HA
Medical-grade hyaluronic acid commands raw-material prices ranging from USD 2,000 to USD 60,000 per kg, depending on molecular weight and endotoxin limits. Limited fermentation capacity for ultra-high-molecular-weight streams leads to supply-demand imbalances and spot price spikes exceeding 25% within a quarter. Quality-assurance testing-including endotoxin, protein, and nucleic-acid assays-adds 15-20% to production expenses relative to cosmetic grades. Dual sourcing from animal tissues remains necessary for certain therapies, but premium pricing elevates input cost for manufacturers that must maintain redundant supply chains. Small-to-mid-size firms often lack the purchasing power to secure long-term contracts, amplifying exposure to price swings that compress margins and inhibit R&D investment.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Ophthalmic Applications
- Shift Toward Fermentation-Based, Vegan-Certified Production
- Emergence of Cross-Linked Dry-Powder HA for Improved Shelf-Life
- Adverse Reactions and Regulatory Scrutiny on Injectable Fillers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Drug-delivery systems generated the fastest 5.72% CAGR through 2031 as formulators exploit CD44 receptor targeting to enhance chemotherapeutic payload concentration. This momentum steers the hyaluronic acid raw material market toward specialized therapeutics with longer product-development cycles and higher regulatory barriers. Dermatology and dermal fillers retained 37.12% of 2025 revenue, demonstrating the segment's resilience amid broadening anatomic indications and safety upgrades.
Dermatology remains central to consumer awareness; however, sustained investments in oncologic, orthopedic, and ophthalmic indications diversify the revenue mix. Orthopedic viscosupplementation shifts toward single-injection formats, illustrating demand for convenience and reduced clinic visits. Ophthalmic pipelines add structural treatments that command premium reimbursement. Cross-therapeutic synergies-from drug-eluting gels to regenerative scaffolds-support pricing power and lengthen product life cycles, enabling manufacturers to amortize R&D costs across multiple indications.
Complete Report Scope:
- By Application
- Orthopedics (Viscosupplements)
- Ophthalmology
- Drug Delivery
- Dermatology / Dermal Fillers
- Other Applications
- By End User
- Hospitals
- Cosmetic Clinics
- Other End Users
- By Source
- Animal-derived
- Microbial Fermentation
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 43.10% revenue in 2025, supported by entrenched reimbursement frameworks for viscosupplementation and high adoption of premium fillers. Favorable FDA pathways encourage quick scaling of novel ophthalmic and orthopedic devices.
Asia-Pacific will post the fastest 6.28% CAGR through 2031 as regulators harmonize standards and middle-class consumers embrace minimally invasive aesthetics. China's NMPA approval of the Algeness VL filler in 2024 illustrates regulatory openness to differentiated formulations . Japan's universal healthcare coverage of viscosupplementation further enlarges the therapeutic base.
Europe remains a sustainability vanguard, rewarding vegan-certified and solvent-free manufacturing. Strict MDR regimes favor incumbents with mature quality systems, reinforcing competitive moats. South America shows upticks linked to economic stabilization, while Middle Eastern markets leverage medical tourism. Africa's nascent demand gains momentum as urban clinics adopt cost-effective dry-powder fillers that circumvent cold-chain gaps.
- Bloomage Biotechnology Corp. Ltd.
- Kewpie Corporation
- FocusChem Biotech Co. Ltd.
- Contipro a.s.
- Seikagaku
- Abbvie
- Anika Therapeutics
- Sanofi
- Roche
- Bausch Health
- Zimmer Biomet
- Smiths Group
- Galderma
- Lifecore Biomedical
- LG Life Sciences
- Fidia Farmaceutici
- Huaxi Biotech
- Alcon
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Table of Contents - Global Hyaluronic Acid Raw Material Market
2 Introduction
- 2.1 Study Assumptions & Market Definition
- 2.2 Scope of the Study
3 Research Methodology
4 Executive Summary
5 Market Landscape
- 5.1 Market Overview
- 5.2 Market Drivers
- 5.2.1 Rising Demand For Anti-Ageing & Minimally-Invasive Aesthetic Solutions
- 5.2.2 Rapid Growth Of Viscosupplementation In Knee-Osteoarthritis Therapy
- 5.2.3 Expanding Ophthalmic Applications
- 5.2.4 Shift Toward Fermentation-Based, Vegan-Certified Production
- 5.2.5 Emergence Of Cross-Linked Dry-Powder HA For Improved Shelf-Life
- 5.2.6 Use Of HA As Bio-Scaffold In 3-D Bioprinting & Tissue Engineering
- 5.3 Market Restraints
- 5.3.1 High Product Cost & Price Volatility Of Pharmaceutical-Grade HA
- 5.3.2 Adverse Reactions And Regulatory Scrutiny On Injectable Fillers
- 5.3.3 Supply-Chain Risk From Limited Fermentation Capacity In China
- 5.3.4 Environmental Concerns Over Solvent-Intensive Cross-Linking Processes
- 5.4 Value / Supply-Chain Analysis
- 5.5 Regulatory Landscape
- 5.6 Technological Outlook
- 5.7 Porter's Five Forces
- 5.7.1 Threat of New Entrants
- 5.7.2 Bargaining Power of Buyers
- 5.7.3 Bargaining Power of Suppliers
- 5.7.4 Threat of Substitutes
- 5.7.5 Intensity of Competitive Rivalry
6 Market Size & Growth Forecasts (Value)
- 6.1 By Application
- 6.1.1 Orthopedics (Viscosupplements)
- 6.1.2 Ophthalmology
- 6.1.3 Drug Delivery
- 6.1.4 Dermatology / Dermal Fillers
- 6.1.5 Other Applications
- 6.2 By End User
- 6.2.1 Hospitals
- 6.2.2 Cosmetic Clinics
- 6.2.3 Other End Users
- 6.3 By Source
- 6.3.1 Animal-derived
- 6.3.2 Microbial Fermentation
- 6.4 By Geography
- 6.4.1 North America
- 6.4.1.1 United States
- 6.4.1.2 Canada
- 6.4.1.3 Mexico
- 6.4.2 Europe
- 6.4.2.1 Germany
- 6.4.2.2 United Kingdom
- 6.4.2.3 France
- 6.4.2.4 Italy
- 6.4.2.5 Spain
- 6.4.2.6 Rest of Europe
- 6.4.3 Asia-Pacific
- 6.4.3.1 China
- 6.4.3.2 Japan
- 6.4.3.3 India
- 6.4.3.4 Australia
- 6.4.3.5 South Korea
- 6.4.3.6 Rest of Asia-Pacific
- 6.4.4 Middle East & Africa
- 6.4.4.1 GCC
- 6.4.4.2 South Africa
- 6.4.4.3 Rest of Middle East & Africa
- 6.4.5 South America
- 6.4.5.1 Brazil
- 6.4.5.2 Argentina
- 6.4.5.3 Rest of South America
- 6.4.1 North America
7 Competitive Landscape
- 7.1 Market Concentration
- 7.2 Market Share Analysis
- 7.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 7.3.1 Bloomage Biotechnology Corp. Ltd.
- 7.3.2 Kewpie Corporation
- 7.3.3 FocusChem Biotech Co. Ltd.
- 7.3.4 Contipro a.s.
- 7.3.5 Seikagaku Corporation
- 7.3.6 AbbVie Inc. (Allergan)
- 7.3.7 Anika Therapeutics Inc.
- 7.3.8 Sanofi (Genzyme)
- 7.3.9 F. Hoffmann-La Roche Ltd.
- 7.3.10 Bausch Health Companies Inc.
- 7.3.11 Zimmer Biomet
- 7.3.12 Smith & Nephew PLC
- 7.3.13 Galderma SA
- 7.3.14 Lifecore Biomedical LLC
- 7.3.15 LG Life Sciences
- 7.3.16 Fidia Farmaceutici S.p.A.
- 7.3.17 Huaxi Biotech
- 7.3.18 Alcon Inc.
8 Market Opportunities & Future Outlook
- 8.1 White-space & Unmet-Need Assessment

