PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114864

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114864
Enterprise Manufacturing Intelligence - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the enterprise manufacturing intelligence market size was valued at USD 4.1 billion in 2025 and estimated to grow from USD 5.03 billion in 2026 to reach USD 13.92 billion by 2031, at a CAGR of 22.6% during the forecast period (2026-2031).
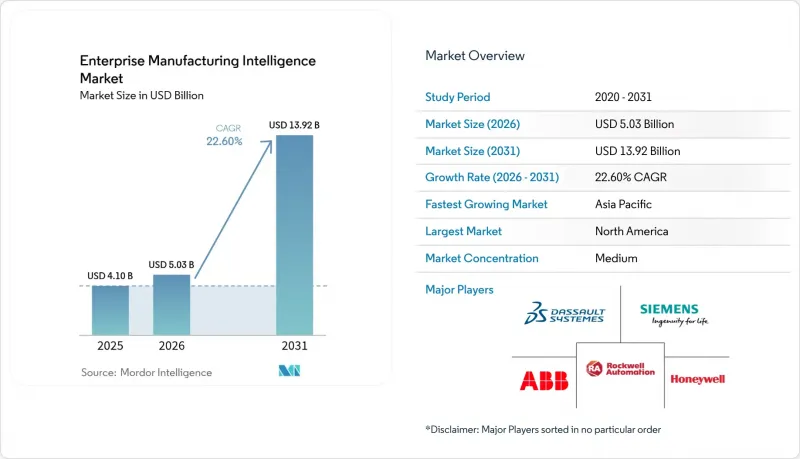
This report is Segmented by Application (Data Integration, Analytics & Analysis and More), End-User Industry (Automotive, Aerospace & Defense and More), Deployment Mode (On-Premise, Hybrid (Edge + Cloud) and Cloud-Native), Component and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Enterprise Manufacturing Intelligence Market Trends and Insights
Shift-left Analytics Enables Real-time Quality-by-design
Real-time analytics embedded into production detect deviations at origin and have lowered scrap by as much as 30% at facilities such as Samsung Biologics, where computational fluid-dynamics models run inline to adjust biopharma parameters instantly. Machine-learning algorithms now forecast quality outcomes from upstream signals, closing the gap between design intent and manufacturing reality. Regulated industries gain added value because early defect detection prevents recalls and regulatory penalties. When integrated with execution platforms, AI-powered control loops keep processes within specification while maximizing throughput. These outcomes strengthen executive support for scaled deployments across multi-site networks.
Digital Thread Requirements in Smart Factories
End-to-end digital threads connect design, production, and service data, letting manufacturers trace issues back to specific process settings and material lots. Aerospace supplier Safran Aero Boosters uses PTC ThingWorx to link engineering models with shop-floor execution, enabling predictive maintenance and continuous improvement. The concept is expanding to suppliers through blockchain-backed traceability that ensures data integrity for audit readiness. Seamless connectivity also lets global plants adopt best practices in real time, accelerating product launches and shortening change-management cycles.
Pay-back Hesitation in Brown-field Retrofits
Legacy plants struggle to justify sensor retrofits and integration work that interrupt production and stretch pay-back periods. Managers favour projects with immediate savings, delaying holistic intelligence rollouts. The risk of disrupting long-lifecycle assets, alongside capex freezes in cyclical sectors, pushes many firms to pilot limited scopes rather than commit to enterprise-wide deployments.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Industrial 5G and Edge AI
- Economies' Green-deal Subsidies Linked to OEE KPIs
- Persistent Data Ownership Uncertainty in Multi-tier Supply Chains
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Analytics and Analysis held a 40.62% slice of 2025 revenue, confirming that insight generation underpins every deployment of the Enterprise Manufacturing Intelligence market. Workflow and KPI Management, forecast at a 27.09% CAGR, reflects the pivot from static reports to real-time, closed-loop performance control. Visualization tools and data-integration layers round out typical stacks but spend concentrates where algorithms deliver measurable throughput gains.
Enterprises now tie operator workflows to machine learning outputs that guide decision steps, creating self-adjusting lines. Honeywell's explainable-AI modules exemplify how contextual guidance slashes downtime and training overhead. As generative interfaces mature, query-by-voice dashboards let frontline staff interrogate live plant metrics, shrinking the barrier between domain experts and shop-floor data.
Automotive producers accounted for 23.52% revenue in 2025 through extensive platform rollouts for body-shop robotics and final-assembly sequencing. Pharmaceuticals and biotechnology will post the fastest 25.54% CAGR as regulators mandate continuous process verification and digital twins. The Enterprise Manufacturing Intelligence market size for drug makers is forecast to expand fastest because batch genealogy and sterile conditions require granular, time-stamped datasets.
GlaxoSmithKline's digital twin vaccines project reports tangible yield increases after virtual validation of recipe changes. Aerospace and defense firms concentrate on digital-thread traceability to meet export-control audits, while semiconductor fabs exploit inline analytics for sub-micron defect detection. Food processors also climb the adoption curve due to stringent safety protocols.
Complete Report Scope:
- By Application
- Data Integration
- Analytics & Analysis
- Visualization / Dashboards
- Workflow & KPI management
- By End-user Industry
- Automotive
- Aerospace & Defense
- Electronics & Semiconductors
- Food & Beverage
- Chemicals & Materials
- Pharmaceuticals & Biotech
- By Deployment Mode
- On-premise
- Hybrid (Edge + Cloud)
- Cloud-native
- By Component
- Platforms / Software
- Services
- Embedded Analytics Hardware
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Europe
- Italy
- France
- United Kingdom
- Germany
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Africa
- Nigeria
- South Africa
- Kenya
- North America
Geography Analysis
North America controlled 37.71% of 2025 global revenue as early adopters such as Procter and Gamble embedded hybrid cloud execution systems that unify more than 100 plants. Federal reshoring incentives and partnerships with hyperscalers reinforce momentum by funding lighthouse sites that showcase OEE boosts. An extensive ecosystem of system integrators supplies talent pipelines that de-risk rollouts for mid-sized manufacturers.
Asia-Pacific will post the fastest 26.41% CAGR through 2031. China, Japan, and South Korea funnel state grants into Industry 4.0 pilots, while Singapore's nation-wide digital-factory roadmap prescribes baseline connectivity standards. Electronics and battery producers lead adoption to offset tight labour markets and meet export quality thresholds. Regional cloud providers now operate local availability zones to satisfy data-residency regulations, widening access for tier-2 suppliers. Europe leverages regulatory levers such as the Clean Industrial Deal, steering capital towards platforms that document emissions alongside OEE. German automotive clusters pilot blockchain provenance to certify recycled steel, and Italian food-processing lines deploy AI to cut energy use. Brexit-triggered supply-chain shocks elevate the need for inventory visibility from Midlands aerospace plants to mainland tier-1 suppliers, cementing Enterprise Manufacturing Intelligence adoption as a resilience strategy.
- ABB Ltd.
- Aspen Technology Inc.
- AVEVA Group plc
- Dassault Systmes SE
- Emerson Electric Co.
- General Electric Co.
- Hexagon AB
- Honeywell International Inc.
- Mitsubishi Electric Corp.
- Rockwell Automation Inc.
- SAP SE
- Schneider Electric SE
- Siemens AG
- Yokogawa Electric Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift-left analytics enables real-time quality-by-design
- 4.2.2 Digital thread requirements in smart factories
- 4.2.3 Integration of industrial 5G & edge AI
- 4.2.4 Economies green-deal subsidies linked to OEE KPIs
- 4.2.5 Rising use of low-code composable apps by operators
- 4.3 Market Restraints
- 4.3.1 Pay-back hesitation in brown-field retrofits
- 4.3.2 Persistent data ownership uncertainty in multi-tier supply chains
- 4.3.3 Talent shortage in IT-OT data engineering
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Data Integration
- 5.1.2 Analytics & Analysis
- 5.1.3 Visualization / Dashboards
- 5.1.4 Workflow & KPI management
- 5.2 By End-user Industry
- 5.2.1 Automotive
- 5.2.2 Aerospace & Defense
- 5.2.3 Electronics & Semiconductors
- 5.2.4 Food & Beverage
- 5.2.5 Chemicals & Materials
- 5.2.6 Pharmaceuticals & Biotech
- 5.3 By Deployment Mode
- 5.3.1 On-premise
- 5.3.2 Hybrid (Edge + Cloud)
- 5.3.3 Cloud-native
- 5.4 By Component
- 5.4.1 Platforms / Software
- 5.4.2 Services
- 5.4.3 Embedded Analytics Hardware
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.3 Europe
- 5.5.3.1 Italy
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Germany
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.6 Africa
- 5.5.6.1 Nigeria
- 5.5.6.2 South Africa
- 5.5.6.3 Kenya
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Aspen Technology Inc.
- 6.4.3 AVEVA Group plc
- 6.4.4 Dassault Systmes SE
- 6.4.5 Emerson Electric Co.
- 6.4.6 General Electric Co.
- 6.4.7 Hexagon AB
- 6.4.8 Honeywell International Inc.
- 6.4.9 Mitsubishi Electric Corp.
- 6.4.10 Rockwell Automation Inc.
- 6.4.11 SAP SE
- 6.4.12 Schneider Electric SE
- 6.4.13 Siemens AG
- 6.4.14 Yokogawa Electric Corp.
- 6.5 Investment Analysis
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space & Unmet-need assessment

