PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114930

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114930
Glacial Acetic Acid - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
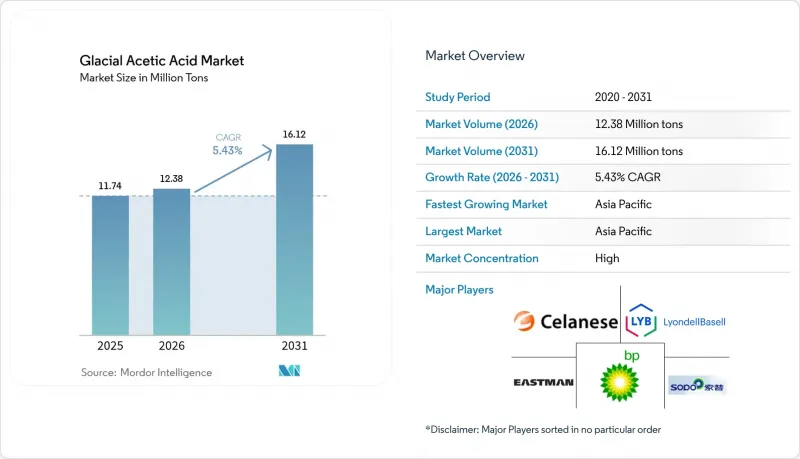
According to Mordor Intelligence, the glacial acetic acid market size is expected to grow from 11.74 Million tons in 2025 to 12.38 Million tons in 2026 and is forecast to reach 16.12 Million tons by 2031 at 5.43% CAGR over 2026-2031.
This report Segments the Industry by Grade (Food Grade, Industrial Grade, and Pharmaceutical Grade), Application (Vinyl Acetate Monomer, Ester Production, Acetic Anhydride, Solvent, Food Additive, and More), End-Use Industry (Chemicals and Petrochemicals, Food and Beverage, Pharmaceuticals, and More) and Geography (Asia-Pacific, North America, Europe, and Rest of the World).
Global Glacial Acetic Acid Market Trends and Insights
Expanding Production Capacity in Asia-Pacific to Serve Vinyl Acetate Monomer Demand
Key Highlights
- Asia-Pacific producers are adding large-scale acetic acid units to secure VAM feedstock. Jiangsu Sopo's 450 kt expansion and GNFC's planned 200 kt unit illustrate the region's push toward self-sufficiency. This capacity wave is tilting global trade balances and nudging North American and European suppliers toward higher-value derivatives. As VAM demand in adhesives, paints, and flexible packaging climbs, integrated producers in China, India, and Japan are locking in scale advantages. Downstream converters benefit from shorter supply chains and reduced freight costs, adding momentum to regional manufacturing.
Increasing Adoption of Bio-based Feedstock in Acetic Acid Manufacturing
Commercialization of carbon-capture and biomass-based routes is lowering life-cycle emissions. Again's flue-gas-to-acetic-acid process reduces reliance on methanol and attracts sustainability-driven buyers, while New Iridium's photochemical route targets cellulosic waste streams. Producer interest in these pathways is also a hedge against methanol volatility and tightening carbon regulations. Long-term offtake agreements with consumer-goods companies seeking low-carbon ingredients further underpin investment cases.
Volatility in Methanol Feedstock Prices
Methanol spot prices swung sharply during 2024, compressing producer margins and complicating capacity planning. Unintegrated plants were hardest hit, prompting renewed interest in hedging tools and alternative feedstocks. Completion of Methanex's acquisition of OCI's methanol assets is expected to shift global bargaining power toward integrated giants.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand from Pharmaceutical Excipients in Emerging Economies
- Growth of Solvent Applications in Adhesives and Sealants
- Stringent Occupational-Safety Norms Limiting Handling and Storage
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial Grade dominated the glacial acetic acid market with a 72.60% share in 2025 as bulk producers supplied VAM plants and downstream chemical syntheses. The segment's scale delivers cost leadership, yet profit sensitivity to methanol prices remains. Pharmaceutical Grade, though smaller, is on track for a 6.82% CAGR, reflecting stricter impurity limits in API synthesis and injectable formulations. Recent capacity additions in India's Gujarat region illustrate producer moves to capture this higher-margin pool.
Demand for ultra-high-purity material in semiconductor wet processes is emerging as a lucrative niche. Linewidth reduction in advanced nodes heightens sensitivity to metallic contaminants, so producers able to deliver parts-per-billion impurity levels can command significant premiums. These offerings create a two-tier pricing environment in which standard pharmaceutical grade supports volume while electronics grade secures profitability. The opportunity aligns with national strategies in Japan and South Korea to safeguard chip-supply sovereignty, offering suppliers stable offtake commitments.
Complete Report Scope:
- By Grade
- Food Grade
- Industrial Grade
- Pharmaceutical Grade
- By Application
- Vinyl Acetate Monomer
- Ester Production
- Acetic Anhydride
- Solvent
- Food Additive
- Textile
- Other Applications
- By End-Use Industry
- Chemicals and Petrochemicals
- Food and Beverage
- Pharmaceuticals
- Textiles and Leather
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Rest of the World
- Middle East and Africa
- South America
- Asia-Pacific
Geography Analysis
Asia-Pacific held 62.60% of the glacial acetic acid market in 2025 and is advancing at a 6.72% CAGR through 2031. China holds a significant share of the global methanol capacity, supported by state-linked financing and integrated methanol sourcing. India is scaling domestic output, and joint-venture discussions such as INEOS Acetyls with GNFC underline the nation's import-replacement agenda. Japan and South Korea concentrate on high-purity niches for electronics and pharmaceuticals, fetching premium pricing.
North America ranks second by volume, anchored in the chemical and food industries. Department of Energy grants for bio-based acetic acid projects enable technology pilots that could lower carbon intensity and partially insulate the region from methanol swings. Trade policy uncertainty adds a cautionary tone, as tariff shifts may affect downstream polymer exports.
Europe shows mature demand with a tilt toward specialty grades and climate-aligned processes. Fit for 55 legislation spurs investment in low-carbon acetyls, while competitive pressure from Asian imports suppresses commodity-grade margins. Germany and the United Kingdom remain the largest European consumers, leveraging strong pharmaceutical and food sectors. The Middle East benefits from low-cost feedstocks and rising construction activity, especially under Saudi Arabia's Vision 2030, whereas South America progresses more modestly with incremental growth in Brazil and Argentina.
- Akshar Enterprises
- Ashok Alco-Chem Ltd.
- BP p.l.c.
- Celanese Corporation
- Daicel Corporation
- Eastman Chemical Company
- Gujarat Narmada Valley Fertilizers & Chemicals Limited
- INEOS
- ITW Reagents Division
- Jiangsu Sopo (Group) Co., Ltd.
- KH Chemicals
- LyondellBasell Industries Holdings B.V.
- Merck KGaA
- PCCA
- SABIC
- Shanghai Wujing Chemical Co., Ltd.
- Spectrum Chemical
- Tan Hung Phu Chemical Co. Ltd.
- Thana Acid & Chemical Co.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding Production Capacity in Asia-Pacific to Serve Vinyl Acetae Momomer( VAM) Demand
- 4.2.2 Increasing Adoption of Bio-based Feedstock in Acetic Acid Manufacturing
- 4.2.3 Rising Demand from Pharmaceutical Excipients in Emerging Economies
- 4.2.4 Growth of Solvent Applications in Adhesives and Sealants
- 4.2.5 Textile Industry Revival in Southeast Asia Boosting Acetic Acid Dyeing Agents
- 4.3 Market Restraints
- 4.3.1 Volatility in Methanol Feed-stock Prices
- 4.3.2 Stringent Occupational-Safety Norms Limiting Handling and Storage
- 4.3.3 Supply-Demand Imbalances Causing Price Suppression
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts ( Volume)
- 5.1 By Grade
- 5.1.1 Food Grade
- 5.1.2 Industrial Grade
- 5.1.3 Pharmaceutical Grade
- 5.2 By Application
- 5.2.1 Vinyl Acetate Monomer
- 5.2.2 Ester Production
- 5.2.3 Acetic Anhydride
- 5.2.4 Solvent
- 5.2.5 Food Additive
- 5.2.6 Textile
- 5.2.7 Other Applications
- 5.3 By End-Use Industry
- 5.3.1 Chemicals and Petrochemicals
- 5.3.2 Food and Beverage
- 5.3.3 Pharmaceuticals
- 5.3.4 Textiles and Leather
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 Rest of the World
- 5.4.4.1 Middle East and Africa
- 5.4.4.2 South America
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Akshar Enterprises
- 6.4.2 Ashok Alco-Chem Ltd.
- 6.4.3 BP p.l.c.
- 6.4.4 Celanese Corporation
- 6.4.5 Daicel Corporation
- 6.4.6 Eastman Chemical Company
- 6.4.7 Gujarat Narmada Valley Fertilizers & Chemicals Limited
- 6.4.8 INEOS
- 6.4.9 ITW Reagents Division
- 6.4.10 Jiangsu Sopo (Group) Co., Ltd.
- 6.4.11 KH Chemicals
- 6.4.12 LyondellBasell Industries Holdings B.V.
- 6.4.13 Merck KGaA
- 6.4.14 PCCA
- 6.4.15 SABIC
- 6.4.16 Shanghai Wujing Chemical Co., Ltd.
- 6.4.17 Spectrum Chemical
- 6.4.18 Tan Hung Phu Chemical Co. Ltd.
- 6.4.19 Thana Acid & Chemical Co.
- 6.4.20 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 High-Purity Acetic Acid for Semiconductor Wet-Chemistry

