PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115064

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115064
Europe Electric Motors For Electric Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
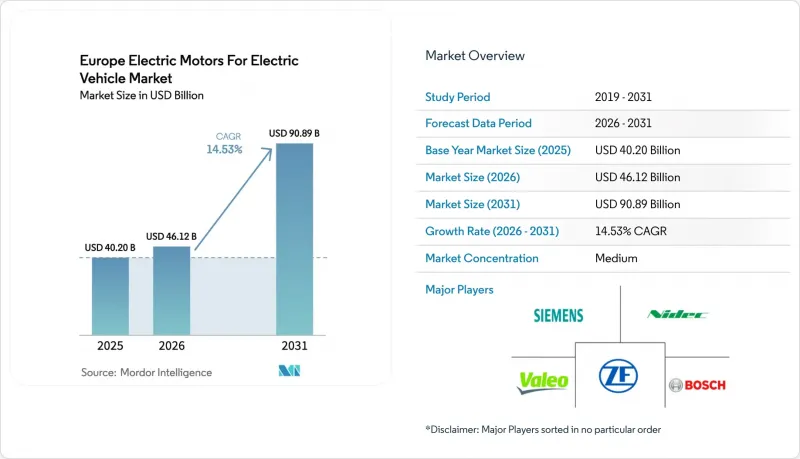
According to Mordor Intelligence, the European electric motors for the electric vehicle market are expected to grow from USD 40.20 billion in 2025 to USD 46.12 billion in 2026 and are forecast to reach USD 90.89 billion by 2031, advancing at a 14.53% CAGR during the forecast period (2026-2031).
This report is Segmented by Motor Type (DC Brushed, DC Brushless, and More), Vehicle Type (BEV, HEV, and More), Application (Two-Wheeler and More), Power Output (Less Than 50 KW and More), Cooling Method (Air-Cooled and Liquid-Cooled), and Country (Germany, United Kingdom, France, and More). Market Forecasts are Provided in Terms of Both Value (USD) and Volume (Units).
Europe Electric Motors For Electric Vehicle Market Trends and Insights
Stricter EU CO2 Fleet-Average Targets for 2025 and 2030
The European Union's Regulation 2025/1214 lowered the 2025 fleet-average limit to 93.6 g CO2/km till 2029 and set a 49.5 g CO2/km ceiling for 2034, pairing steep non-compliance fines with the expiration of the super-credit mechanism at the end of 2025. Automakers now accelerate BEV launches, irrespective of short-term profitability, because every percentage-point gap in the electric-vehicle mix can trigger hundreds of millions of euros in penalties. Platform production is therefore being front-loaded at factories in Zwickau, Emden, and Tychy, with suppliers scaling hairpin stator and rotor lines accordingly. The regulation effectively ties motor demand to statutory ceilings rather than consumer preference, pushing European electric motors for the electric vehicle market onto a policy-driven growth path.
Rapid Decline in Battery USD/kWh Enabling Affordable BEVs
Average pack prices slid from USD 153/kWh in 2022 to USD 111/kWh in 2024 and are on track to fall below USD 80/kWh by 2026. Crossing this threshold enables B- and C-segment BEVs to reach purchase-price parity with internal-combustion cars without subsidies, thereby expanding the potential motor customer base by tens of millions of vehicles. Renault's 2025 R5 E-Tech launch at EUR 25,000 illustrates how lower battery costs free pricing headroom to specify higher-efficiency, 110 kW permanent-magnet motors. Component suppliers, meanwhile, have trimmed assembly labor per motor by nearly one-third, thanks to copper hairpin winding and integrated inverters. Yet the shift toward lithium-iron-phosphate batteries-with their lower energy density-requires motors to deliver better efficiency across a broader torque band, highlighting the delicate balance between cost, range, and rare-earth demand.
Rare-Earth Magnet Price Volatility and Supply-Chain Risk
Neodymium-praseodymium oxide peaked near USD 68,000 per metric ton in early 2025 before sliding to USD 54,000 by year-end, a 26% swing that destabilized quarterly gross margins for many Tier 1 suppliers. Forward contracts can cushion some volatility but carry hefty premiums, further squeezing profit. Substituting ferrite magnets reduces power density by up to 20%, necessitating design changes that few OEMs are willing to accept for mainstream passenger cars. Recycling initiatives in Saxony aim to recover 2,000 metric tons annually by 2028; however, this covers less than 5% of the projected European demand. Until domestic extraction or large-scale recycling becomes a viable option, magnet pricing remains a structural headwind.
Other drivers and restraints analyzed in the detailed report include:
- OEM Electrification Road-Maps and Platform Shifts
- Spain's 2024 PERTE VEC 2 Program Anchoring New E-Drive Supply Chains
- High CAPEX for Advanced Hair-Pin Winding and Liquid-Cooling Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Permanent Magnet Synchronous Motors (PMSMs) commanded 58.71% of the European electric motors for the electric vehicle market share in 2025, as their power density allows automakers to meet interior-space targets without resizing vehicle subframes. Induction motors are often used in dual-motor all-wheel-drive configurations, where their lower cost offsets the penalties associated with partial-load efficiency. BLDC units maintained a foothold in two- and three-wheelers due to their simplicity and compatibility with air cooling. At the same time, brushed DC motors have largely been replaced by BLDC units in mainstream automotive use. SRM volume is rising quickly-forecasted to increase at a 16.97% CAGR through 2031, because magnet-free designs hedge against rare-earth volatility.
SRM gains come with engineering trade-offs: higher torque ripple and acoustic noise demand sophisticated control algorithms that in turn require costlier silicon-carbide inverters. Nevertheless, suppliers unveiled 150 kW SRM prototypes that achieve over 90% rated-load efficiency, significantly narrowing the gap with PMSM. Induction motor adoption remains steady where battery packs exceed 75 kWh, as the impact on range is less severe. Overall, technology mix shifts will continue, yet PMSM remains the anchor of the European electric motors for the electric vehicle market through 2031.
BEVs absorbed 72.88% of the market share in 2025 on the strength of Volkswagen ID models, Stellantis platforms, and Tesla's sustained Model Y sales. FCEVs are expanding at a 19.81% CAGR through 2031, driven by hydrogen-refueling corridors that now span 250 stations across Germany, France, and the Netherlands. The PHEV share is eroding under stricter real-world CO2 testing, prompting OEMs to reallocate their R&D budgets toward full-electric architectures. HEVs still serve regions with patchy charging networks but generate lower motor revenue because power ratings often stay below 50 kW.
In heavy-duty trucks, dual 180 kW liquid-cooled PMSMs in FCEVs are designed to offset the fuel-cell response lag, marking a departure from BEV standards. While BEVs dominate in volume, the growth of FCEVs not only offers an incremental boost but also diversifies the demand landscape for European electric motors for the electric vehicle market.
Complete Report Scope:
- By Motor Type
- DC Brushed Motors
- DC Brushless Motors (BLDC)
- Induction Motors (AC)
- Permanent Magnet Synchronous Motors (PMSM)
- Switched Reluctance Motors (SRM)
- By Vehicle Type
- Battery Electric Vehicles (BEVs)
- Hybrid Electric Vehicles (HEVs)
- Plug-in Hybrid Electric Vehicles (PHEVs)
- Fuel Cell Electric Vehicles (FCEVs)
- By Application
- Two-Wheelers
- Three-Wheelers
- Passenger Cars
- Commercial Vehicles
- Off-Road / Industrial EVs
- By Power Output
- Less than 50 kW
- 51 to 100 kW
- 101 to 200 kW
- 201 to 400 kW
- Above 400 kW
- By Cooling Method
- Air-Cooled Motors
- Liquid-Cooled Motors
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Robert Bosch GmbH
- Siemens AG
- ZF Friedrichshafen AG
- Valeo SA
- Continental AG
- Schaeffler AG
- Nidec Corporation
- BorgWarner Inc.
- MAHLE GmbH
- ABB Ltd.
- NSK Ltd.
- NTN Corporation
- YASA Limited
- GKN Automotive
- Inovance Automotive
- Parker Hannifin
- Dana Inc.
- Hitachi Astemo
- Vitesco Technologies
- Rheinmetall AG
- Traktionssysteme Austria GmbH
- Skoda Electric
- Elaphe Propulsion Technologies
- Protean Electric
- Johnson Electric Holdings
- Tesla Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter EU CO2 Fleet-Average Targets for 2026 and 2030
- 4.2.2 Rapid Decline in Battery USD/kWh Enabling Affordable BEVs
- 4.2.3 OEM Electrification Road-Maps and Platform Shifts (MEB, STLA-Medium, etc.)
- 4.2.4 Spain's 2024 PERTE VEC 2 Program Anchoring New E-Drive Supply Chains
- 4.2.5 Surging Demand from Retrofit E-Powertrains for Urban Delivery Vans
- 4.2.6 AI-Driven Motor-Inverter Co-Design Cutting Motor Rare-Earth Content
- 4.3 Market Restraints
- 4.3.1 Rare-Earth Magnet Price Volatility and Supply-Chain Risk
- 4.3.2 High CAPEX for Advanced Hair-Pin Winding and Liquid-Cooling Lines
- 4.3.3 Grid Connection Queues Delaying E-Bus Depot Roll-Outs
- 4.3.4 Talent Shortage in SiC/GaN Power-Electronics Packaging
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Motor Type
- 5.1.1 DC Brushed Motors
- 5.1.2 DC Brushless Motors (BLDC)
- 5.1.3 Induction Motors (AC)
- 5.1.4 Permanent Magnet Synchronous Motors (PMSM)
- 5.1.5 Switched Reluctance Motors (SRM)
- 5.2 By Vehicle Type
- 5.2.1 Battery Electric Vehicles (BEVs)
- 5.2.2 Hybrid Electric Vehicles (HEVs)
- 5.2.3 Plug-in Hybrid Electric Vehicles (PHEVs)
- 5.2.4 Fuel Cell Electric Vehicles (FCEVs)
- 5.3 By Application
- 5.3.1 Two-Wheelers
- 5.3.2 Three-Wheelers
- 5.3.3 Passenger Cars
- 5.3.4 Commercial Vehicles
- 5.3.5 Off-Road / Industrial EVs
- 5.4 By Power Output
- 5.4.1 Less than 50 kW
- 5.4.2 51 to 100 kW
- 5.4.3 101 to 200 kW
- 5.4.4 201 to 400 kW
- 5.4.5 Above 400 kW
- 5.5 By Cooling Method
- 5.5.1 Air-Cooled Motors
- 5.5.2 Liquid-Cooled Motors
- 5.6 By Country
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Robert Bosch GmbH
- 6.4.2 Siemens AG
- 6.4.3 ZF Friedrichshafen AG
- 6.4.4 Valeo SA
- 6.4.5 Continental AG
- 6.4.6 Schaeffler AG
- 6.4.7 Nidec Corporation
- 6.4.8 BorgWarner Inc.
- 6.4.9 MAHLE GmbH
- 6.4.10 ABB Ltd.
- 6.4.11 NSK Ltd.
- 6.4.12 NTN Corporation
- 6.4.13 YASA Limited
- 6.4.14 GKN Automotive
- 6.4.15 Inovance Automotive
- 6.4.16 Parker Hannifin
- 6.4.17 Dana Inc.
- 6.4.18 Hitachi Astemo
- 6.4.19 Vitesco Technologies
- 6.4.20 Rheinmetall AG
- 6.4.21 Traktionssysteme Austria GmbH
- 6.4.22 Skoda Electric
- 6.4.23 Elaphe Propulsion Technologies
- 6.4.24 Protean Electric
- 6.4.25 Johnson Electric Holdings
- 6.4.26 Tesla Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

