PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115168

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115168
Lighting As A Service (LaaS) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, lighting as a service market size in 2026 is estimated at USD 1.01 billion, growing from 2025 value of USD 0.77 billion with 2031 projections showing USD 4.01 billion, growing at 31.64% CAGR over 2026-2031.
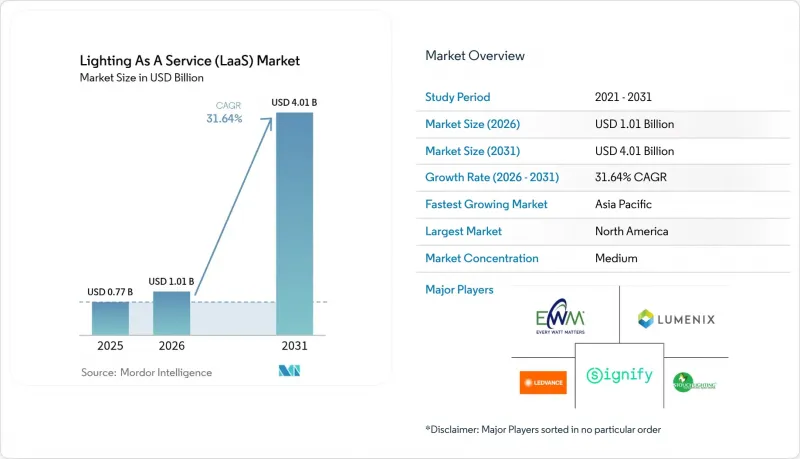
This report is Segmented by Installation Type (Indoor and Outdoor), Component (Luminaires and Controls, Software and Analytics, and Services), Contract Type (Retrofit Projects and New Installations), End User (Commercial, Municipal, Industrial, and Residential), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Lighting As A Service (LaaS) Market Trends and Insights
Government Energy-Efficiency Mandates
New rules, such as the U.S. Department of Energy's 120 lumens-per-watt standard, effective July 2028, trigger widespread fixture obsolescence, positioning service contracts as a compliance shortcut that avoids heavy upfront cap-ex. Municipal utilities in California invested USD 223 million in 2022 efficiency programs, with lighting accounting for 34% of the gross annual savings, underscoring the urgency of purchasing. Because service providers assume replacement and regulatory risk, cities and corporates pivot toward outcome-based agreements that guarantee standards alignment while delivering measurable carbon-cutting baselines.
Declining LED & Sensor Costs
LED package prices have fallen sharply, enabling service providers to offer subscriptions at prices below those of incumbent utilities while maintaining their margins. With LED units already accounting for 70% of global shipments in 2024 and projected to reach 87% by 2030, a secondary replacement demand of 5.8 billion lamps emerges, boosting recurring revenue prospects. Connected luminaires reduce energy consumption by up to 80% when sensor-guided dimming is combined with native LED efficiency, enhancing the service value proposition.
High Total Contract Cost vs. Cap-Ex Purchase
Monthly fees can appear burdensome when compared with spot purchases, despite LEDs consuming 75% less power and lasting 25 times longer than incandescent fixtures. Organisations possessing strong cash reserves often decide to self-finance equipment to capture full savings, especially in economies prone to currency swings that inflate service premiums. Providers need to emphasize guaranteed uptime, refresh cycles, and performance warranties to offset sticker shock.
Other drivers and restraints analyzed in the detailed report include:
- Corporate Net-Zero & ESG Targets
- IoT-Enabled Smart-Building Retrofits
- Utility Rebate Uncertainty
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Indoor projects accounted for 69.92% of the Lighting as a Service market in 2025, reflecting abundant demand in offices, logistics hubs, and manufacturing facilities where standardized ceiling grids reduce engineering variance and simplify service pricing. Providers bundle predictive maintenance and future technology upgrades into contracts, ensuring clients avoid stranded assets as control protocols evolve. Energy code tightening across North America and the EU intensifies the focus on indoor environments, while AI-driven occupancy analytics unlock new revenue opportunities per square foot. Outdoor implementations are scaling quickly at a 37.6% CAGR thanks to municipal smart-street programs; poles now support cameras, 5G small cells, and environmental sensors. Washington D.C.'s USD 309 million concession validates the economics by pairing 50% energy savings with revenue-sharing from data services, an example that is being mirrored in Miami-Dade's USD 211.7 million multi-sensor rollout. These projects demonstrate how lighting poles evolve into digital urban infrastructure, signaling a deeper level of municipal engagement for Lighting as a Service market teams.
Outdoor's expansion prompts vendors to refine ruggedized hardware, adaptive dimming algorithms, and financial structures, such as public-private partnerships, that align with 15-year debt amortization schedules. The segment's growth also stimulates ancillary markets for security analytics, parking management, and air-quality monitoring. As more cities re-tender legacy fixtures, providers with turnkey design-build-finance-maintain packages gain commercial leverage. Indoor environments will remain volume leaders, but the higher per-node revenue and public-sector tenures of outdoor solutions will balance overall portfolio risk for top vendors within the Lighting as a Service market.
Hardware still accounts for 59.10% of 2025 revenue, yet software and analytics are racing ahead at a 41.2% CAGR through 2031, transforming data insights into the new competitive frontier for the Lighting as a Service industry. Energy dashboards, predictive failure alerts, and integration APIs embed lighting networks inside broader building-management stacks. The Lighting as a Service market size tied to analytics unlocks performance-based billing, allowing providers to monetize kilowatt-hour savings and productivity improvements rather than billing strictly per luminaire. AI-enabled optimisation now delivers up to 26% incremental energy cut on top of LED gains across multi-tenant offices.
Service modules covering asset financing, preventive maintenance, and luminaire recycling continue to underpin vendor cash flows. However, margin expansion also arises from proprietary algorithms that refine light-level tuning based on time-of-day, occupancy, and daylight harvesting inputs. Platforms that maintain open-protocol interoperability outpace closed ecosystems by facilitating seamless integration of third-party sensors and HVAC systems. The differentiation shift forces legacy manufacturers to invest in software talent or acquire SaaS-native firms to protect their installed bases. Customers benefit through lifecycle cost transparency and feature extensibility, reinforcing stickiness inside the Lighting as a Service market.
Complete Report Scope:
- By Installation Type
- Indoor
- Outdoor
- By Component
- Luminaires and Controls
- Software and Analytics
- Services (Maintenance, Financing)
- By Contract Type
- Retrofit Projects
- New Installations
- By End User
- Commercial
- Municipal
- Industrial
- Residential
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held a 44.12% share in 2025, driven by mature public-private partnership frameworks and rebate portfolios that reduce payback horizons. Washington D.C.'s USD 309 million street-lighting overhaul illustrates how city governments achieve 50% energy cuts while upgrading poles for surveillance and 5G backhaul. Federal efficiency rules mandating 120 lumens per watt by 2028 inject urgency into school, airport, and roadway retrofits. Utility incentives such as Austin Energy's USD 420-per-kW credits further sweeten contract economics.
The Asia-Pacific region posts the fastest 43.9% CAGR, undergirded by high-density urbanization and state-engineered smart-city budgets. India's Street Lighting National Program already retrofitted 29.5 million fixtures, translating into 39.30 million tonnes of annual CO2 abatement. China's multi-city digital-twin demonstrations and projects, such as the PHP 2.105 billion Bacolod Super City initiative, amplify the regional appetite for large-scale Lighting as a Service market convergence, Including Lighting, connectivity, and e-governance.
Europe's market follows a stable replacement rhythm anchored to stringent climate legislation and aging sodium-vapor networks. Copenhagen switched 18,800 streetlights to LED, saving 55% of energy and eliminating 3,200 tons of CO2 each year, while installing a remote-monitoring platform that future-proofs the poles for environmental sensors. Providers compete primarily on service-level adherence and cybersecurity credentials, as EU directives focus on data protection. Emerging regions in the Middle East, Africa, and South America display uneven but rising interest, where multilateral lenders and export-credit agencies bridge financing gaps, lighting the way for nascent Lighting as a Service market penetration.
- Signify Holding
- GE Current, a Daintree company
- Acuity Brands
- Zumtobel Group
- Enlighted Inc (Siemens)
- LEDVANCE GmbH
- Ameresco Inc.
- Orion Energy Systems
- Lumenix
- Stouch Lighting
- LumenServe Inc.
- Lime Energy (now Willdan)
- RAB Lighting
- Revolution Lighting Technologies
- EnergyFocus Inc.
- Helvar Oy
- WattMan Lighting
- Every Watt Matters
- Lighthouse Technologies
- ESB Group (Energy Services)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government energy-efficiency mandates
- 4.2.2 Declining LED & sensor costs
- 4.2.3 Corporate net-zero & ESG targets
- 4.2.4 IoT-enabled smart-building retrofits
- 4.2.5 Green-bond financing for lighting OPEX models
- 4.2.6 AI-driven lighting-as-a-platform upsell potential
- 4.3 Market Restraints
- 4.3.1 High total contract cost vs. cap-ex purchase
- 4.3.2 Utility rebate uncertainty
- 4.3.3 Cyber-security concerns in connected luminaires
- 4.3.4 Limited LaaS awareness in mid-sized enterprises
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Installation Type
- 5.1.1 Indoor
- 5.1.2 Outdoor
- 5.2 By Component
- 5.2.1 Luminaires and Controls
- 5.2.2 Software and Analytics
- 5.2.3 Services (Maintenance, Financing)
- 5.3 By Contract Type
- 5.3.1 Retrofit Projects
- 5.3.2 New Installations
- 5.4 By End User
- 5.4.1 Commercial
- 5.4.2 Municipal
- 5.4.3 Industrial
- 5.4.4 Residential
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 NORDIC Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Signify Holding
- 6.4.2 GE Current, a Daintree company
- 6.4.3 Acuity Brands
- 6.4.4 Zumtobel Group
- 6.4.5 Enlighted Inc (Siemens)
- 6.4.6 LEDVANCE GmbH
- 6.4.7 Ameresco Inc.
- 6.4.8 Orion Energy Systems
- 6.4.9 Lumenix
- 6.4.10 Stouch Lighting
- 6.4.11 LumenServe Inc.
- 6.4.12 Lime Energy (now Willdan)
- 6.4.13 RAB Lighting
- 6.4.14 Revolution Lighting Technologies
- 6.4.15 EnergyFocus Inc.
- 6.4.16 Helvar Oy
- 6.4.17 WattMan Lighting
- 6.4.18 Every Watt Matters
- 6.4.19 Lighthouse Technologies
- 6.4.20 ESB Group (Energy Services)
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

