PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115874

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115874
North America Renewable Aviation Fuel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, North America renewable aviation fuel market size in 2026 is estimated at USD 2.16 billion, growing from 2025 value of USD 1.53 billion with 2031 projections showing USD 12.07 billion, growing at 41.08% CAGR over 2026-2031.
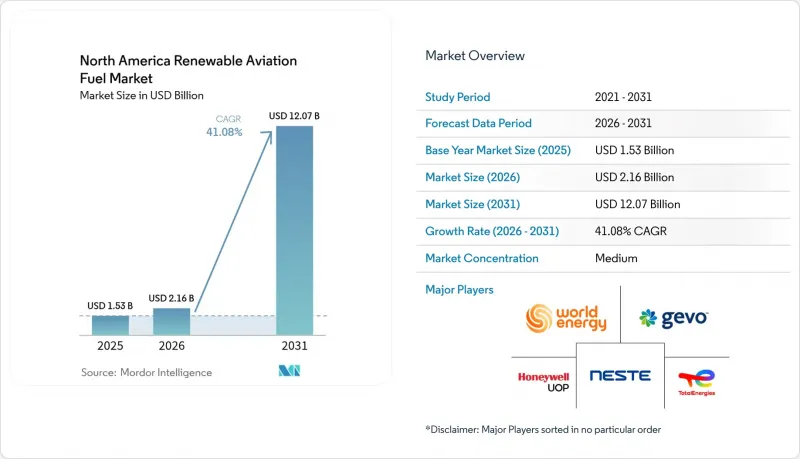
This report is Segmented by Technology (Fischer-Tropsch, Hydroprocessed Esters and Fatty Acids, Alcohol-To-Jet, Synthesized Iso-Paraffinic, Catalytic Hydrothermolysis Jet, and Hydrothermal Liquefaction), Application (Commercial Passenger Airlines, Cargo Airlines, Military Aviation, and Business and General Aviation), and Geography (United States, Canada, and Mexico).
North America Renewable Aviation Fuel Market Trends and Insights
SAF Tax-Credits Under the U.S. Inflation Reduction Act
The Inflation Reduction Act offers up to USD 1.75 per gallon for SAF achieving at least 50% lifecycle greenhouse-gas savings, a step that compresses the cost delta with fossil jet fuel and sets an economic foundation for multi-hundred-million-gallon projects. Lifecycle intensity rules tilt the advantage toward ATJ and Fischer-Tropsch designs that can meet deeper carbon cuts, hastening technology diversification across the North America renewable aviation fuel market. The shift in 2025 to Section 45Z credits layers fresh incentives for agricultural feedstock suppliers, potentially lowering ethanol input cost curves. Obligatory carbon accounting and verification increase administrative complexity, a hurdle more readily cleared by large, integrated producers. Still, the headline tax credit catalyzes offtake deals that transform airline demand into bankable cash flows, supporting the forecast 42.5% CAGR.
Net-Zero Pledges Signed by Above 90% of North-American Airline Capacity
Airlines representing over 90% of passenger capacity have committed to achieving net-zero by 2050, with interim targets that call for 10-30% SAF usage by 2030. Delta alone has secured purchase agreements covering 200 million gallons, while United targets a 10% SAF blend within five years, thereby anchoring long-range demand curves. Military interest intensifies the pull: Lockheed Martin has cleared synthetic fuels for the F-35, F-16, and C-130 fleets, opening another sizable market segment. Binding pledges alter bargaining power, encouraging airlines to negotiate early, sometimes equity-linked, positions in upcoming facilities. The resulting demand certainty lifts lender confidence, accelerating project financial close across the North America renewable aviation fuel market.
Feedstock Aggregation Bottlenecks in the U.S. Midwest
Corn-ethanol plants operate at scales smaller than the 100-million-gallon conversion units optimal for ATJ, resulting in complex aggregation networks that increase logistics costs. Ethanol already competes with gasoline in the market, so SAF projects must compete on price, potentially introducing volatility into supply contracts. Storage and pipeline capacity in the region remain limited, resulting in additional freight expenses for coastal refineries. Co-location strategies, such as SAFFiRE's corn-stover-to-ethanol pairing with LanzaJet technology, partially mitigate the challenge but require synchronized capital deployment. Until bottlenecks ease, the North America renewable aviation fuel market faces supply-side friction that tempers near-term growth.
Other drivers and restraints analyzed in the detailed report include:
- Rising Corporate "Green Travel" Procurement Programs
- Emerging Carbon-Negative Alcohol-to-Jet Pathways
- HEFA Feedstock Price Volatility Linked to Renewable Diesel Build-Out
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
HEFA commanded 83.20% of the North America renewable aviation fuel market share in 2025, a testament to its commercial readiness, existing hydroprocessing infrastructure, and established logistics chains. Capital requirements remain modest because facilities retrofit legacy diesel hydrotreaters, enabling projects to achieve investment-grade status faster than greenfield designs. However, feedstock scarcity and rising competition from renewable diesel refineries curb long-term scalability.
Alcohol-to-jet pathways, although nascent, are projected to post a 45.89% CAGR through 2031, the fastest in the technology stack. LanzaJet's Freedom Pines plant validates the route's commercial viability, while CirculAir's waste-carbon fermentation breaks the dependence on agricultural oils, an advantage that resonates with investors seeking long-lived assets. The high tax-credit uplift for deep-carbon-cut fuels amplifies project IRRs, further shifting capital allocation toward ATJ. Fischer-Tropsch routes remain in the demonstration phase due to high capital expenditures, yet they hold promise for forestry-rich regions like British Columbia. Catalytic Hydrothermolysis Jet and Hydrothermal Liquefaction remain in pilot stages but could advance if lifecycle scores meet the upper tiers of Section 45Z thresholds within the North American renewable aviation fuel market.
Complete Report Scope:
- By Technology
- Fischer-Tropsch (FT)
- Hydroprocessed Esters & Fatty Acids (HEFA)
- Alcohol-to-Jet (ATJ)
- Synthesized Iso-Paraffinic (SIP)
- Catalytic Hydrothermolysis Jet (CHJ)
- Hydrothermal Liquefaction (HTL)
- By Application
- Commercial Passenger Airlines
- Cargo Airlines
- Military Aviation
- Business & General Aviation
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Neste Oyj
- TotalEnergies SA
- World Energy LLC
- Honeywell UOP
- Gevo Inc.
- Fulcrum BioEnergy Inc.
- LanzaTech Global Inc.
- Alder Fuels
- Aemetis Inc.
- SG Preston Company
- Red Rock Biofuels LLC
- Velocys plc
- Marathon-Neste JV (Diamond Green Diesel)
- BP p.l.c.
- Shell plc (Shell Aviation)
- Praj Industries
- Virent Inc.
- SkyNRG Americas
- Boeing (SAF partnerships)
- Carbon Engineering Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 SAF tax-credits under the U.S. Inflation Reduction Act
- 4.2.2 Net-zero pledges signed by Above 90 % of North-American airline capacity
- 4.2.3 Rising corporate "green travel" procurement programs
- 4.2.4 Emerging carbon-negative alcohol-to-jet (ATJ) pathways
- 4.2.5 Regional airport consortia financing on-site SAF blenders
- 4.3 Market Restraints
- 4.3.1 Feedstock aggregation bottlenecks in the U.S. Midwest
- 4.3.2 HEFA feedstock price volatility linked to renewable diesel build-out
- 4.3.3 Lack of ASTM approval for 100 % drop-in SAF use
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Fischer-Tropsch (FT)
- 5.1.2 Hydroprocessed Esters & Fatty Acids (HEFA)
- 5.1.3 Alcohol-to-Jet (ATJ)
- 5.1.4 Synthesized Iso-Paraffinic (SIP)
- 5.1.5 Catalytic Hydrothermolysis Jet (CHJ)
- 5.1.6 Hydrothermal Liquefaction (HTL)
- 5.2 By Application
- 5.2.1 Commercial Passenger Airlines
- 5.2.2 Cargo Airlines
- 5.2.3 Military Aviation
- 5.2.4 Business & General Aviation
- 5.3 By Country
- 5.3.1 United States
- 5.3.2 Canada
- 5.3.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Neste Oyj
- 6.4.2 TotalEnergies SA
- 6.4.3 World Energy LLC
- 6.4.4 Honeywell UOP
- 6.4.5 Gevo Inc.
- 6.4.6 Fulcrum BioEnergy Inc.
- 6.4.7 LanzaTech Global Inc.
- 6.4.8 Alder Fuels
- 6.4.9 Aemetis Inc.
- 6.4.10 SG Preston Company
- 6.4.11 Red Rock Biofuels LLC
- 6.4.12 Velocys plc
- 6.4.13 Marathon-Neste JV (Diamond Green Diesel)
- 6.4.14 BP p.l.c.
- 6.4.15 Shell plc (Shell Aviation)
- 6.4.16 Praj Industries
- 6.4.17 Virent Inc.
- 6.4.18 SkyNRG Americas
- 6.4.19 Boeing (SAF partnerships)
- 6.4.20 Carbon Engineering Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

