PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116109

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116109
Rare Disease Genetic Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, rare disease genetic testing market size in 2026 is estimated at USD 1.38 billion, growing from 2025 value of USD 1.21 billion with 2031 projections showing USD 2.65 billion, growing at 13.96% CAGR over 2026-2031.
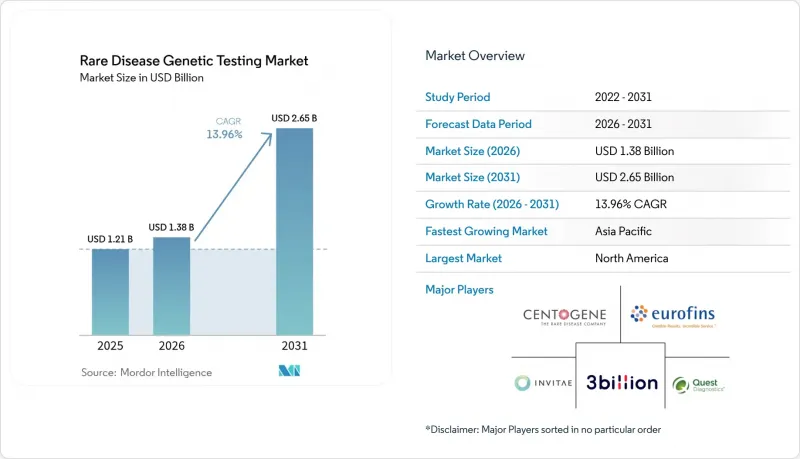
This report Segments the Industry Into by Test Type (Single-Gene Tests, Gene Panels and More), by Technology (Next-Generation Sequencing, PCR-Based Testing and More), by Sample Type (Blood, Saliva/Buccal Swab and More), by Indication (Neurological Disorders, Metabolic Disorders and More), and Geography (North America, Europe and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Rare Disease Genetic Testing Market Trends and Insights
Declining Cost of Next-Generation Sequencing
NGS reagent and instrument costs fell sharply, pushing whole-genome sequencing below USD 600 per sample by late 2024, a threshold that undercuts many multi-gene panels. Cost parity encourages hospitals to deploy genome-first protocols that replace sequential single-gene tests and shorten diagnostic odysseys. Real-world economic studies show mean savings of USD 100,440 per patient when rapid genome sequencing is used in neonatal intensive care units. Throughput gains from instruments such as Illumina's NovaSeq X and Oxford Nanopore's PromethION 2 Integrated further suppress per-base prices, while automation trims personnel expenses. As laboratories scale, the rare disease genetic testing market gains predictable price elasticity, unlocking pent-up demand among clinicians who previously rationed complex testing.
National Reimbursement Expansion for Rare-Disease Diagnostics
Public and private payers now reimburse comprehensive sequencing in several high-income regions. Texas Medicaid introduced coverage for whole-exome and whole-genome sequencing at USD 3,728.40 and USD 3,924.34 respectively in late 2024. North Carolina Medicaid soon followed, covering tests for Duchenne muscular dystrophy and Lynch syndrome. Medicare added hereditary transthyretin amyloidosis sequencing, setting clinical precedent for other payers. These policies reduce patient out-of-pocket exposure and nudge institutions toward routine genomic work-ups, a trend mirrored by nascent subsidy programs in China and India. Reimbursement certainty accelerates revenue capture for laboratories and magnifies the total addressable rare disease genetic testing market.
High Out-of-Pocket Costs & Limited Payer Coverage
Although coverage is expanding, many patients still shoulder fees between USD 300 and USD 5,000 when insurance declines claims. Administrative hurdles such as prior authorization deter ordering clinicians and lengthen turnaround times. Direct-to-consumer firms attempt to bridge gaps with USD 99 monthly subscriptions, yet their recreational reports rarely meet clinical utility standards. In emerging economies, private pay may equal several months of average household income, limiting adoption and constraining the rare disease genetic testing market in regions most burdened by consanguinity-linked disorders.
Other drivers and restraints analyzed in the detailed report include:
- AI-Enhanced Variant-Interpretation Platforms
- Biopharma Trial Recruitment via Rare-Disease Gene Databases
- Shortage of Certified Genetic Counsellors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Whole-exome sequencing led revenue with 36.12% of rare disease genetic testing market share in 2025, balancing cost and diagnostic yield for protein-coding mutations. Whole-genome sequencing, growing at 15.08% CAGR, captures non-coding and structural variants that exomes overlook, steadily eroding panel-based testing. Single-gene assays persist as confirmatory tools when a clear pathogenic variant runs in families.Clinical evidence underpins the transition. Genome sequencing delivers 23% higher yields than chromosomal microarray in neurodevelopmental cohorts while lowering cumulative costs across two years. Long-read workflows from Oxford Nanopore resolve tandem repeat expansions historically invisible to short-reads, positioning long-read genomes as the future gold standard. Rapid neonatal protocols that finish analysis inside 12 hours further reinforce genome testing as an urgent-care staple, cementing its role in the evolving rare disease genetic testing market.
Short-read NGS captured 71.58% revenue during 2025, but long-read platforms are trending up at 15.92% CAGR thanks to structural-variant sensitivity. Sanger sequencing retains utility for variant confirmation, especially when laboratories require orthogonal validation.Technology convergence accelerates. Illumina's NovaSeq X now integrates single-flow-cell chips and AI-driven base-calling, cutting per-sample run time while lifting raw accuracy. Portable devices such as MinION bring near-lab quality to field sites, broadening geographic reach. As accuracy gaps narrow, cost curves favor holistic multi-omic platforms, expanding the rare disease genetic testing market size across hospital tiers and regional laboratories.
Complete Report Scope:
- By Test Type (Value)
- Single-Gene Tests
- Gene Panels
- Whole-Exome Sequencing
- Whole-Genome Sequencing
- By Technology (Value)
- Next-Generation Sequencing
- Sanger Sequencing
- PCR-Based Testing
- By Sample Type (Value)
- Blood
- Saliva/Buccal Swab
- Amniotic/Chorionic (Prenatal)
- By Indication (Value)
- Neurological Disorders
- Metabolic Disorders
- Immunological & Hematological Disorders
- Others
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America, with 42.76% share in 2025, benefits from broad payer coverage, payer-funded NICU sequencing, and clear FDA pathways that tie diagnostics to recently approved gene therapies. Whole-genome reimbursement for critically ill infants lowers barriers across state Medicaid programs and drives steady case volumes into regional reference labs.Asia-Pacific posts the highest growth, advancing at 16.02% CAGR on national registries and subsidized testing in India and China ijbscience.in. Local manufacturers develop cost-effective reagents, while portable sequencers circumvent infrastructure gaps. Government consortiums negotiate bulk pricing, making genome tests affordable for provincial hospitals and amplifying the rare disease genetic testing market footprint.Europe sustains mid-teen growth under the European Health Data Space, which mandates interoperable health records. Germany's Digital Act simplifies cross-border data transfers, enhancing multi-country trial recruitment. Although reimbursement varies, pan-EU data pooling increases diagnostic odds for ultra-rare variants. Latin America and the Middle East remain nascent but leverage pilot programs such as Brazil's Rare Genomes Project to highlight unmet need and justify new funding streams.
- Illumina
- Thermo Fisher Scientific
- Roche
- QIAGEN
- Agilent Technologies
- Invitae
- GeneDx
- Centogene
- PerkinElmer
- Eurofins
- BGI
- Myriad Genetics
- 23andMe
- Oxford Nanopore Technologies
- Natera
- Color Health
- Blueprint Genetics
- Baylor Genetics
- ARUP Laboratories
- BioReference Laboratories
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Declining cost of next-generation sequencing
- 4.2.2 National reimbursement expansion for rare-disease diagnostics
- 4.2.3 AI-enhanced variant-interpretation platforms
- 4.2.4 Biopharma trial recruitment via rare-disease gene databases
- 4.2.5 Newborn genomic-screening pilots
- 4.2.6 Portable long-read sequencers in emerging markets
- 4.3 Market Restraints
- 4.3.1 High out-of-pocket costs & limited payer coverage
- 4.3.2 Shortage of certified genetic counsellors
- 4.3.3 Fragmented genomic-privacy regulations
- 4.3.4 Low diagnostic yield for non-coding/ultra-rare variants
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Test Type (Value)
- 5.1.1 Single-Gene Tests
- 5.1.2 Gene Panels
- 5.1.3 Whole-Exome Sequencing
- 5.1.4 Whole-Genome Sequencing
- 5.2 By Technology (Value)
- 5.2.1 Next-Generation Sequencing
- 5.2.2 Sanger Sequencing
- 5.2.3 PCR-Based Testing
- 5.3 By Sample Type (Value)
- 5.3.1 Blood
- 5.3.2 Saliva/Buccal Swab
- 5.3.3 Amniotic/Chorionic (Prenatal)
- 5.4 By Indication (Value)
- 5.4.1 Neurological Disorders
- 5.4.2 Metabolic Disorders
- 5.4.3 Immunological & Hematological Disorders
- 5.4.4 Others
- 5.5 By Geography (Value)
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Illumina
- 6.3.2 Thermo Fisher Scientific
- 6.3.3 F. Hoffmann-La Roche
- 6.3.4 Qiagen
- 6.3.5 Agilent Technologies
- 6.3.6 Invitae
- 6.3.7 GeneDx
- 6.3.8 Centogene
- 6.3.9 PerkinElmer
- 6.3.10 Eurofins Scientific
- 6.3.11 BGI Genomics
- 6.3.12 Myriad Genetics
- 6.3.13 23andMe
- 6.3.14 Oxford Nanopore Technologies
- 6.3.15 Natera
- 6.3.16 Color Health
- 6.3.17 Blueprint Genetics
- 6.3.18 Baylor Genetics
- 6.3.19 ARUP Laboratories
- 6.3.20 BioReference Laboratories
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

