PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116333

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116333
External Defibrillator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the external defibrillator market size was valued at USD 4.03 billion in 2025 and is estimated to grow from USD 4.32 billion in 2026 to reach USD 6.23 billion by 2031, at a CAGR of 7.60% during the forecast period (2026-2031).
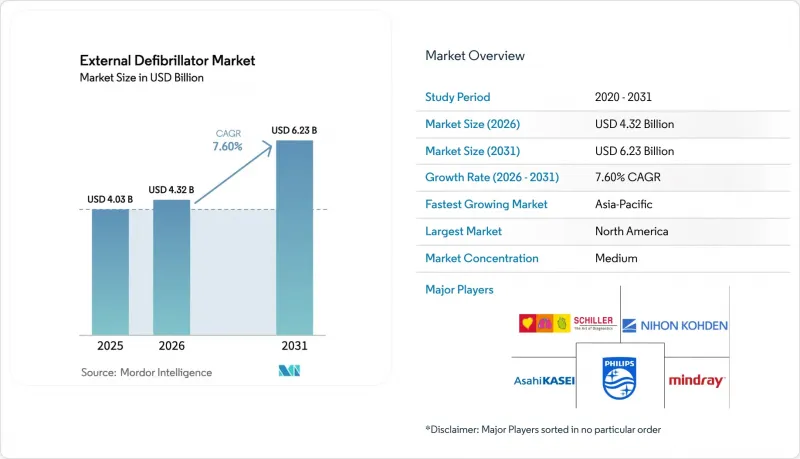
This report is Segmented by Product (Manual External Defibrillators, and More), Patient Type (Adult and Pediatric), End-User (Hospitals & Cardiac Centers, Pre-Hospital & EMS, Public Access Settings, Home Healthcare, and Alternate Care), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global External Defibrillator Market Trends and Insights
Rising Burden of Sudden Cardiac Arrests Globally
Out-of-hospital cardiac arrest affects more than 350,000 people each year in the United States, yet survival-to-discharge remains below 12%, intensifying the need for rapid defibrillation. Aging populations and a higher prevalence of metabolic syndrome are amplifying case volumes across Europe and the Asia-Pacific region, thereby broadening the external defibrillator market. Every minute of defibrillation delay reduces the survival probability by 7% to 10%, prompting health authorities to prioritize the placement of devices in public venues. The 2025 American Heart Association guidelines extended perioperative defibrillation recommendations, prompting the procurement of defibrillators into surgical suites. While epidemiological pressure is high, closing the survival gap also requires training initiatives, compelling manufacturers to bundle education with device sales.
Expanding Public-Access Defibrillation Programs and Mandates
State rules such as Maine's health club AED requirement and New Jersey's school deployment law have accelerated institutional purchases in the United States. In December 2025, PulsePoint and ZOLL Medical launched the National Emergency AED Registry to provide dispatch centers with real-time device location data, thereby shortening response times[2]. Europe's 2022 peri-operative guidelines are driving National Health Service trusts to standardize equipment stocks, and China's December 2024 policy reforms cut clinical review timelines to 30 days in pilot zones. Compliance remains uneven because few jurisdictions enforce penalties; however, the direction is firmly toward broader deployment, which supports demand growth in the external defibrillator market.
High Total Cost of Ownership and Maintenance
The retail price of an automated external defibrillator averages USD 2,338, but batteries and electrode pads require replacement every 2 to 5 years, pushing lifetime outlays above USD 4,000. Schools and community centers with limited budgets often defer the acquisition of refurbished units that lack software updates, creating a bifurcated installed base. Field audits in 2024 revealed 18% of public devices had expired electrodes and 12% had depleted batteries, undermining emergency readiness. The 2026 Durable Medical Equipment fee schedule raised allowable charges by only 2%, leaving most public-access deployments unfunded. Subscription models that bundle hardware, consumables, and monitoring are emerging to convert capital expenditure into predictable operating expenses.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advancements in Smart and Connected AEDs
- Growing Adoption of Wearable Cardioverter Defibrillators
- Insufficient Public Awareness and Training
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Manual external defibrillators captured 45.43% of the external defibrillator market share in 2025, reinforcing their role in critical-care environments that require invasive pressure monitoring and capnography. Average selling prices range between USD 15,000 and USD 25,000, and multi-parameter integrations justify hospital budget allocations despite lengthier replacement cycles. Automated external defibrillators, priced one-tenth as much, are set to expand at 9.54% CAGR, making them the key driver of unit shipments in the external defibrillator market. The external defibrillator market size for automated models is projected to increase by USD 1.25 billion between 2026 and 2031 as public venues update their fleets to comply with new registry-tracking standards. Wearable cardioverter defibrillators remain a niche, but robust clinical evidence and broader reimbursement could unlock incremental growth.
Feature roadmaps emphasize connectivity-Stryker's LIFEPAK 35 uploads readiness data to cloud portals, allowing biomedical engineers to schedule maintenance proactively. AliveCor's 12-lead device blurs lines between responder tools and diagnostic equipment, challenging incumbents to integrate high-resolution sensing without compromising lay-user simplicity. Manual defibrillator suppliers face price pressure as group purchasing organizations negotiate bulk contracts; however, premium software modules for post-event data analytics and protocol compliance help protect margins.
Complete Report Scope:
- By Product
- Manual External Defibrillators
- Automated External Defibrillators (AEDs)
- Semi-Automated AEDs
- Fully-Automated AEDs
- Wearable Cardioverter Defibrillators (WCDs)
- By Patient Type
- Adult
- Pediatric
- By End-User
- Hospitals & Cardiac Centers
- Pre-Hospital & EMS
- Public Access Settings
- Home Healthcare
- Alternate Care
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest Of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest Of Asia-Pacific
- Middle East And Africa
- GCC
- South Africa
- Rest Of Middle East And Africa
- South America
- Brazil
- Argentina
- Rest Of South America
- North America
Geography Analysis
Asia-Pacific is projected to be the fastest-growing region in the external defibrillator market, expanding at an 8.54% CAGR through 2031. China's December 2024 regulatory reforms halved clinical-trial review timelines in pilot zones, accelerating approvals for automated models and encouraging local manufacturing. India's Production Linked Incentive scheme selected BPL Medical Technologies and Allied Medical Limited for domestic production grants, reducing import reliance and improving price competitiveness. Japan's super-aged demographics support institutional procurement, but cultural hesitation toward bystander intervention tempers public-access utilization rates. Localized production, exemplified by BIOTRONIK's Singapore hub, shortens supply chains and sidesteps tariff volatility, positioning multinationals to respond swiftly to regional demand spikes.
North America exhibits mature deployment densities, with most public venues already equipped; growth, therefore, stems from technology refreshes and software upgrades. State mandates, such as Maine's health-club rule, still generate incremental unit sales, but replacement cycles now stretch beyond seven years as hardware reliability improves. Europe is undergoing a supply-chain restructuring following the June 2025 International Procurement Instrument's restriction on Chinese devices in large public tenders, prompting hospitals to shift their orders to regional manufacturers. The change opens up opportunities for European mid-caps, but also presents component-sourcing challenges, as many sub-assemblies originate in China.
The Middle East and Africa remain nascent yet promising segments. Gulf Cooperation Council states are investing in national ambulance modernization, importing defibrillators with Arabic-language interfaces, whereas sub-Saharan markets rely on donor-funded public health projects. South America is expanding slowly; Brazil's public-access initiative in Sao Paulo mandates AEDs in transport terminals, but high import tariffs hinder volume growth. Overall, geographic diversification necessitates multiple regulatory pathways, compelling manufacturers to tailor product documentation, language packs, and post-market surveillance procedures for each jurisdiction.
- Abbott Laboratories
- Asahi Kasei (ZOLL Medical)
- BPL
- Boston Scientific
- Cardiac Science Corp.
- CU Medical Systems
- GE Healthcare
- HeartSine Technologies
- Instramed Industria
- Koninklijke Philips
- Laerdal Medical
- Mediana
- Medtronic
- Metrax GmbH (Primedic)
- Nihon Kohden (Defibtech)
- Progetti
- Schiller
- Mindray
- Stryker (Physio-Control)
- ViVest Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Burden of Sudden Cardiac Arrests Globally
- 4.2.2 Expanding Public-Access Defibrillation Programs and Mandates
- 4.2.3 Technological Advancements in Smart and Connected AEDs
- 4.2.4 Growing Adoption of Wearable Cardioverter Defibrillators
- 4.2.5 Supportive Reimbursement and Regulatory Frameworks
- 4.2.6 Increasing Investments and Strategic Collaborations
- 4.3 Market Restraints
- 4.3.1 High Total Cost of Ownership And Maintenance
- 4.3.2 Supply-Chain Constraints for Critical Components
- 4.3.3 Stringent Regulatory Approval Timelines
- 4.3.4 Insufficient Public Awareness and Training
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory & Reimbursement Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product
- 5.1.1 Manual External Defibrillators
- 5.1.2 Automated External Defibrillators (AEDs)
- 5.1.2.1 Semi-Automated AEDs
- 5.1.2.2 Fully-Automated AEDs
- 5.1.3 Wearable Cardioverter Defibrillators (WCDs)
- 5.2 By Patient Type
- 5.2.1 Adult
- 5.2.2 Pediatric
- 5.3 By End-User
- 5.3.1 Hospitals & Cardiac Centers
- 5.3.2 Pre-Hospital & EMS
- 5.3.3 Public Access Settings
- 5.3.4 Home Healthcare
- 5.3.5 Alternate Care
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest Of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest Of Asia-Pacific
- 5.4.4 Middle East And Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest Of Middle East And Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest Of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)}
- 6.3.1 Abbott Laboratories
- 6.3.2 Asahi Kasei (ZOLL Medical)
- 6.3.3 BPL Medical Technologies
- 6.3.4 Boston Scientific Corp.
- 6.3.5 Cardiac Science Corp.
- 6.3.6 CU Medical Systems
- 6.3.7 GE Healthcare
- 6.3.8 HeartSine Technologies
- 6.3.9 Instramed Industria
- 6.3.10 Koninklijke Philips N.V.
- 6.3.11 Laerdal Medical
- 6.3.12 Mediana Co. Ltd
- 6.3.13 Medtronic Plc
- 6.3.14 Metrax GmbH (Primedic)
- 6.3.15 Nihon Kohden (Defibtech)
- 6.3.16 Progetti Srl
- 6.3.17 Schiller AG
- 6.3.18 Shenzhen Mindray Bio-Medical Electronics
- 6.3.19 Stryker (Physio-Control)
- 6.3.20 ViVest Medical
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

