PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116439

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116439
Oxidative Stress Assay - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the oxidative stress assays market size was valued at USD 1.33 billion in 2025 and estimated to grow from USD 1.46 billion in 2026 to reach USD 2.32 billion by 2031, at a CAGR of 9.68% during the forecast period (2026-2031).
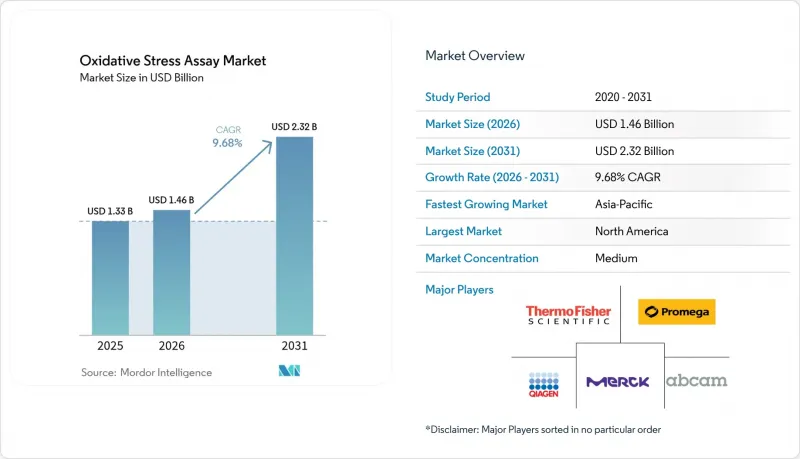
This report is Segmented by Product (Instruments and Consumables), Test Type (Indirect Assays, Antioxidant Capacity Assays, and More), Technology (ELISA, Flow Cytometry, and More), Disease Type (Cardiovascular Diseases, COPD, and More), End User (Contract Research Organizations and More), Sample Type (Cell-Based Samples and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Oxidative Stress Assay Market Trends and Insights
Rapid Growth in Biopharma and Biotech Manufacturing
Expanding biopharma capacity is amplifying demand for oxidative stress assays that serve as real-time quality indicators during process scale-up. Thermo Fisher Scientific invested USD 22 million in oral solid dose facilities and embedded predictive AI to monitor oxidative stress signatures that threaten protein stability. Continuous manufacturing workflows now depend on inline assays able to flag metabolic shifts before they affect yield. Bio-Rad's purchase of Stilla Technologies brought digital PCR sensitivity to oxidative biomarker detection, confirming that next-generation production relies on integrated analytical ecosystems. This transition positions oxidative stress measurement as a standard parameter alongside purity and potency in commercial biologics runs.
Expansion of High-Throughput Screening for ROS Biomarkers
High-throughput screening (HTS) systems let scientists assess thousands of oxidative stress conditions in parallel, cutting discovery timelines for antioxidants and sensitizers. Abcam's FirePlex multiplex platform couples validated antibody pairs with automation, removing the bottleneck of sequential testing and increasing quantitative sensitivity tenfold over earlier kits. Merging HTS with deep-learning algorithms further lowers false positive rates while CRISPR-based functional screening pinpoints genes that mediate redox balance. Cost-reducing miniaturization means libraries can expand without proportional reagent spend, accelerating early-stage drug pipelines.
High Capital Cost of Detection Instruments
Top-tier orbitrap mass spectrometers exceed USD 1 million per unit, and many academic labs defer purchases because budgets trail the pace of innovation. Rapid obsolescence within seven years forces repeat investment, limiting diffusion into resource-constrained geographies. Leasing and pay-per-sample models are emerging but adoption remains low outside North America.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for In-Vitro Toxicology Alternatives
- Mainstream Adoption of Label-Free Live-Cell Imaging Assays
- Lack of Trained Personnel in Multi-Modal Data Interpretation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Instruments generated 55.62% of oxidative stress assays market revenue in 2025 and remain the backbone of advanced screening labs. Novel orbitrap analyzers that profile five times more compounds per run strengthen the segment's appeal among pharmaceutical chemists who require deep metabolite coverage. Consumables, however, will register the fastest 13.12% CAGR to 2031 as kit-based workflows scale beyond top-tier centers. Ready-to-use red-fluorescent probes and standardized reference reagents simplify protocols for smaller labs, widening the oxidative stress assays market. Demand for consumables also benefits from recurring purchasing cycles that accompany ever-shorter assay turnaround expectations.
Second-generation probes with minimized autofluorescence broaden compatibility across flow cytometers and microscopes, boosting kit adoption. At the same time, instrument makers embed AI analytics directly on device firmware, condensing multi-step analysis into a single-click report. This convergence blurs the traditional boundary between hardware and consumables and sustains above-market growth for manufacturers able to provide end-to-end platforms that ensure data continuity.
ROS-based assays accounted for 29.10% of oxidative stress assays market share in 2025 and will grow at 11.82% CAGR as drug developers prioritize real-time insights into oxidative bursts that shape disease progression. Optogenetic H2O2 sensors achieve sub-cellular resolution and capture nanomolar fluxes, enabling researchers to correlate localized stress with pathway activation in cancer and neurodegeneration studies. Indirect assays that measure downstream products such as lipid peroxidation remain valuable when samples are fixed or when long-lived biomarkers are required for population studies.
Multiplex dashboards that combine ROS, antioxidant capacity, and protein oxidation endpoints on a single plate are now common, reducing experiment count and conserving precious primary cells. Such integrated testing shortens validation timelines and supports the oxidative stress assays market size expansion forecast to 2031.
Complete Report Scope:
- By Product
- Instruments
- Consumables
- By Test Type
- Indirect Assays
- Antioxidant Capacity Assays
- Enzyme-based Assays
- Reactive Oxygen Species (ROS)-based Assays
- By Technology
- Enzyme-linked Immunosorbent Assay (ELISA)
- Flow Cytometry
- Chromatography
- Microscopy
- Label-free Impedance & Real-Time Cell Analysis
- By Disease Type
- Cardiovascular Diseases
- Chronic Obstructive Pulmonary Disease (COPD)
- Cancer
- Neuro-degenerative Disorders
- By End User
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutes
- Contract Research Organizations
- By Sample Type
- Cell-based Samples
- Tissue Homogenates
- Blood / Plasma
- Urine & Other Biofluids
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America maintained 36.41% revenue share in 2025 thanks to clear FDA biomarker qualification pathways and a dense biopharma infrastructure that rapidly pilots AI-driven assays from bench to clinic. Venture capital backing and equipment vendors headquartered in the United States foster rapid prototype adoption. Strategic collaborations, such as BioAge Labs partnering with Novartis to explore longevity targets, showcase how regional players leverage oxidative stress data to open new therapeutic frontiers.
Europe follows closely, propelled by stringent 3Rs directives that push laboratories toward validated in-vitro oxidative platforms. Academic centers supply a steady pipeline of assay innovations, while reagent companies emphasize standardized reference materials that meet European Medicines Agency expectations. Joint public-private projects accelerate technology translation and embed oxidative testing in sustainable research frameworks.
Asia Pacific records the fastest 11.05% CAGR through 2031. Chinese institutes advance electrochemical biosensors, and Japan aligns nutraceutical regulations with rigorous oxidative endpoint validation, broadening commercial demand. Government investment in biotechnology education is narrowing the analyst skills gap. Multinational suppliers expand distribution hubs and localized technical support, reflecting confidence in regional growth momentum.
- Thermo Fisher Scientific
- Abcam
- Merck
- QIAGEN
- Promega
- Cell Biolabs
- Cayman Chemical
- Enzo Life Sciences
- AMSBIO
- ImmunoChemistry Technologies
- Biovision
- Creative Diagnostics
- R&D Systems (Bio-Techne)
- Ethos Biosciences
- Signosis Inc.
- Agilent Technologies
- BioAssay Systems
- AssayGenie
- Bio-Rad Laboratories
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth In Biopharma & Biotech Manufacturing
- 4.2.2 Expansion Of High-Throughput Screening (HTS) For ROS Biomarkers
- 4.2.3 Regulatory Push For In-Vitro Toxicology Alternatives
- 4.2.4 Mainstream Adoption Of Label-Free Live-Cell Imaging Assays
- 4.2.5 Novel Red-Fluorescent Probes For Real-Time Mitochondrial ROS
- 4.2.6 Integration Of AI-Driven Assay Analytics
- 4.3 Market Restraints
- 4.3.1 High Capital Cost Of Detection Instruments
- 4.3.2 Lack Of Trained Personnel In Multi-Modal Data Interpretation
- 4.3.3 Photobleaching & Probe-Derived Artifacts
- 4.3.4 Limited Standardization Of ROS Reference Materials
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Product
- 5.1.1 Instruments
- 5.1.2 Consumables
- 5.2 By Test Type
- 5.2.1 Indirect Assays
- 5.2.2 Antioxidant Capacity Assays
- 5.2.3 Enzyme-based Assays
- 5.2.4 Reactive Oxygen Species (ROS)-based Assays
- 5.3 By Technology
- 5.3.1 Enzyme-linked Immunosorbent Assay (ELISA)
- 5.3.2 Flow Cytometry
- 5.3.3 Chromatography
- 5.3.4 Microscopy
- 5.3.5 Label-free Impedance & Real-Time Cell Analysis
- 5.4 By Disease Type
- 5.4.1 Cardiovascular Diseases
- 5.4.2 Chronic Obstructive Pulmonary Disease (COPD)
- 5.4.3 Cancer
- 5.4.4 Neuro-degenerative Disorders
- 5.5 By End User
- 5.5.1 Pharmaceutical & Biotechnology Companies
- 5.5.2 Academic & Research Institutes
- 5.5.3 Contract Research Organizations
- 5.6 By Sample Type
- 5.6.1 Cell-based Samples
- 5.6.2 Tissue Homogenates
- 5.6.3 Blood / Plasma
- 5.6.4 Urine & Other Biofluids
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Thermo Fisher Scientific
- 6.3.2 Abcam plc
- 6.3.3 Merck KGaA (Sigma-Aldrich)
- 6.3.4 Qiagen N.V.
- 6.3.5 Promega Corporation
- 6.3.6 Cell Biolabs Inc.
- 6.3.7 Cayman Chemical
- 6.3.8 Enzo Life Sciences
- 6.3.9 AMSBIO
- 6.3.10 ImmunoChemistry Technologies
- 6.3.11 BioVision Inc.
- 6.3.12 Creative Diagnostics
- 6.3.13 R&D Systems (Bio-Techne)
- 6.3.14 Ethos Biosciences
- 6.3.15 Signosis Inc.
- 6.3.16 Agilent Technologies
- 6.3.17 BioAssay Systems
- 6.3.18 AssayGenie
- 6.3.19 Bio-Rad Laboratories
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

