PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116455

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116455
Neurology Clinical Trials - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the neurology clinical trials market size is expected to grow from USD 6.25 billion in 2025 to USD 6.67 billion in 2026 and is forecast to reach USD 9.26 billion by 2031 at 6.78% CAGR over 2026-2031.
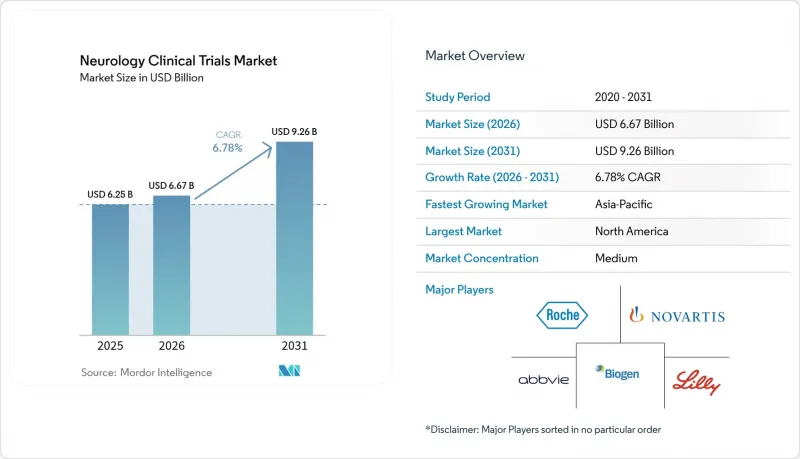
This report is Segmented by Phase (Phase I, Phase II, and More), Study Design (Interventional, Observational, Expanded Access), Indication (Epilepsy, Stroke, Alzheimer's Disease, Parkinson's Disease, Multiple Sclerosis, Migraine, and More), and Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Neurology Clinical Trials Market Trends and Insights
Increasing Global Burden of Neurological Disorders
Neurological conditions now affect more than 1 billion people worldwide, creating urgent demand for disease-modifying therapies that fuels clinical trial volume. Alzheimer's disease alone impacts 55 million individuals and is projected to double by 2050, prompting a pipeline shift toward amyloid- and tau-targeting agents following FDA approvals of aducanumab and lecanemab. Parkinson's disease prevalence surpassed 10 million, and regenerative trials such as Kyoto University's iPS-cell dopaminergic progenitors showed motor-score improvements in 4 of 6 patients. Stroke incidence continues rising, with the Chinese tirofiban study reducing early neurological deterioration by 68% versus aspirin across 10 stroke centers. Population aging therefore extends trial addressable pools and secures multi-year growth momentum for the neurology clinical trials market.
Growing Investment in Central Nervous System Drug Development
Pharmaceutical and venture investors committed record sums to CNS programs in 2025, attracted by clearer regulatory routes and transformative technology platforms. AbbVie launched a USD 2 billion alliance with Gilgamesh Pharmaceuticals to create non-hallucinogenic neuroplastogens for psychiatric disorders. Bayer advanced AB-1005 gene therapy for Parkinson's into Phase II across four countries after favorable Phase Ib safety readouts. Eisai raised its annual venture allocation to JPY 4 billion, earmarking neurology start-ups. New specialist funds such as Nexus NeuroTech Ventures emerged to incubate BCI, gene-editing and neuro-immunology projects. Capital influx accelerates proof-of-concept timelines and diversifies modality choices.
High Cost and Complexity of Late-Phase Neuroscience Trials
Large sample sizes, lengthy follow-up and intricate outcome assessments inflate per-patient costs. The HERCULES study enrolled 1,131 non-relapsing secondary progressive multiple sclerosis patients across 31 countries, illustrating the logistic scale required for progressive indications. Sanofi's parallel Phase III trials for frexalimab further spotlight the financial load of testing novel mechanisms in both relapsing and progressive cohorts. Cell-therapy epilepsy studies demand neurosurgical centers and multi-year monitoring, compounding expenditure. These capital hurdles can deter smaller firms and limit geographic diversity of pivotal trials.
Other drivers and restraints analyzed in the detailed report include:
- Favorable Regulatory Initiatives for Neurotherapeutics
- Technological Advancements in Trial Design and Digital Health
- Stringent Ethical and Regulatory Requirements for CNS Studies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Phase III held the dominant 52.02% neurology clinical trials market share in 2025, reflecting the high revenue weight of large confirmatory studies. Yet Phase I exhibits an 17.35% CAGR to 2031 as gene, cell and BCI programs proliferate. UniQure's AMT-162 SOD1-ALS gene therapy moved into its second dosing cohort within one year, underscoring brisk early-phase throughput. Similarly, Precision's Layer 7 safety trial exemplifies the front-loaded evaluation necessary for invasive neurotech. This burst of Phase I activity signals a robust pipeline that will replenish late-phase volumes after 2027.
Later-stage studies nonetheless remain pivotal for payer acceptance and guideline inclusion. The HERCULES success with tolebrutinib showed a 31% delay in disability progression, setting the stage for regulatory filing and commercial rollout. Post-marketing Phase IV studies-though smaller in spend-provide real-world evidence vital for label expansions, as illustrated by UCSF's ocrelizumab lymph-node mechanism study.
Complete Report Scope:
- By Phase
- Phase I
- Phase II
- Phase III
- Phase IV
- By Study Design
- Interventional
- Observational
- Expanded Access
- By Indication
- Epilepsy
- Stroke
- Alzheimer's Disease
- Parkinson's Disease
- Multiple Sclerosis
- Migraine
- Amyotrophic Lateral Sclerosis
- Other Indications
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America remains the gravitational center of high-complexity neuroscience research. FDA breakthrough designations for BCIs, digital therapeutics and fluid biomarkers lower regulatory opacity and entice multinational sponsors. AbbVie's USD 2 billion neuroplastogen alliance and NIH's USD 10 million annual BRAIN Initiative invasive-device program reinforce capital depth. Extensively networked CROs such as IQVIA and Syneos supply specialized neurosurgical and remote-monitoring logistics, sustaining regional dominance.
Asia-Pacific's momentum derives from broad policy backing and cost-efficient infrastructure. Shanghai StairMed's invasive BCI trial places China among the few nations executing cutting-edge neuroimplants. The 10-center Chinese tirofiban stroke study proved capability to manage >1,000-patient acute trials. Japan's iPS Parkinson's therapy successes ignite regenerative-medicine pipelines. Coupled with rising middle-class neurological disease burden, these factors shift sponsor footprints eastward.
Europe leverages pan-regional networks to run multi-country trials efficiently. Germany's EPIsoDE psilocybin investigation, the UK's temporal-interference Alzheimer's stimulation project and EU-wide Long-COVID neuro-autoantibody trials illustrate breadth of therapeutic exploration. Harmonized ethics review under EMA guidelines shortens setup times, while Horizon Europe grants offset costs for academia-industry consortia.
- Abbvie
- AstraZeneca
- Biogen
- Eli Lilly and Company
- Eisai
- Novartis
- Sanofi
- Merck
- Roche
- Takeda Pharmaceuticals
- Teva Pharmaceutical Industries
- Supernus (Adamas)
- Athira Pharma
- Annovis Bio
- Zydus Group
- Neurocrine Biosciences
- Voyager Therapeutics
- IQVIA
- Parexel International (MA) Corporation
- Charles River
- Syneos Health
- MedPace
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Global Burden of Neurological Disorders
- 4.2.2 Growing Investment in Central Nervous System Drug Development
- 4.2.3 Favorable Regulatory Initiatives for Neurotherapeutics
- 4.2.4 Technological Advancements in Trial Design and Digital Health
- 4.2.5 Expansion of Contract Research Organization Capabilities
- 4.2.6 Rising Adoption of Precision Medicine and Biomarkers in Neurology
- 4.3 Market Restraints
- 4.3.1 High Cost and Complexity of Late-Phase Neuroscience Trials
- 4.3.2 Stringent Ethical And Regulatory Requirements for CNS Studies
- 4.3.3 Recruitment Challenges due to Narrow Patient Eligibility
- 4.3.4 Limited Predictive Preclinical Models for Neurological Diseases
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Buyers
- 4.5.3 Bargaining Power Of Suppliers
- 4.5.4 Threat Of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Phase
- 5.1.1 Phase I
- 5.1.2 Phase II
- 5.1.3 Phase III
- 5.1.4 Phase IV
- 5.2 By Study Design
- 5.2.1 Interventional
- 5.2.2 Observational
- 5.2.3 Expanded Access
- 5.3 By Indication
- 5.3.1 Epilepsy
- 5.3.2 Stroke
- 5.3.3 Alzheimer's Disease
- 5.3.4 Parkinson's Disease
- 5.3.5 Multiple Sclerosis
- 5.3.6 Migraine
- 5.3.7 Amyotrophic Lateral Sclerosis
- 5.3.8 Other Indications
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Abbvie, Inc.
- 6.3.2 Astrazeneca
- 6.3.3 Biogen
- 6.3.4 Eli Lilly & Co.
- 6.3.5 Eisai Co., Ltd.
- 6.3.6 Novartis AG
- 6.3.7 Sanofi
- 6.3.8 Merck & Co.
- 6.3.9 F. Hoffmann-La Roche Ltd.
- 6.3.10 Takeda Pharmaceutical Company Limited
- 6.3.11 Teva Pharmaceutical Industries Ltd.
- 6.3.12 Supernus (Adamas)
- 6.3.13 Athira Pharma
- 6.3.14 Annovis Bio
- 6.3.15 Zydus Group
- 6.3.16 Neurocrine Biosciences
- 6.3.17 Voyager Therapeutics
- 6.3.18 IQVIA Inc.
- 6.3.19 Parexel International (MA) Corporation
- 6.3.20 Charles River Laboratories
- 6.3.21 Syneos Health
- 6.3.22 Medpace, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

