PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116471

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116471
DNA Repair Drugs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the DNA repair drugs market size is expected to grow from USD 8.93 billion in 2025 to USD 10.09 billion in 2026 and is forecast to reach USD 18.53 billion by 2031 at 12.94% CAGR over 2026-2031.
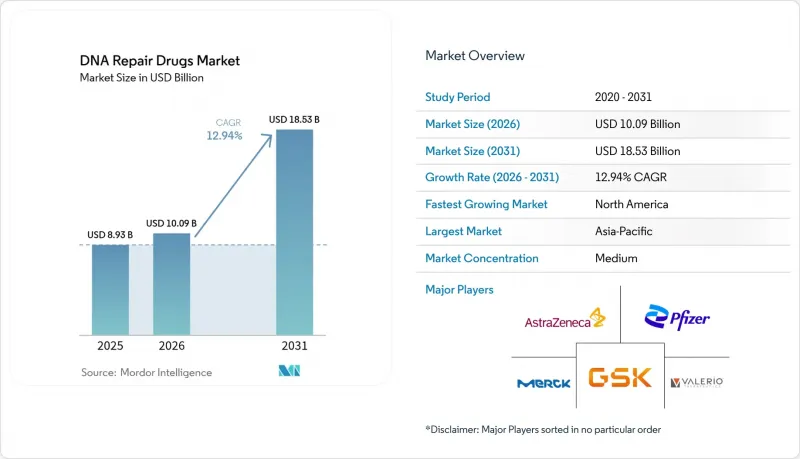
This report is Segmented by Drug Type (PARP Inhibitors and More), Indication (Ovarian Cancer, and More), Line of Therapy (First-Line and Second/Subsequent-Line), Distribution Channel (Hospital Pharmacies, Specialty & Retail Pharmacies, and Online Pharmacies), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global DNA Repair Drugs Market Trends and Insights
Rising Incidence of HR-Deficient Solid Tumors
Expanding HRD testing is enlarging the treatable population for the DNA repair drugs market. Around 50% of high-grade serous ovarian tumors and up to 25% of prostate cancers harbor actionable DNA repair defects. Integration of broad NGS panels into routine care, therefore, unlocks new patient pools and sustains prescription growth, especially where payer coverage is mature.
Label Expansion of PARP Inhibitors into Early-Line & Maintenance Settings
Front-line maintenance use is lengthening therapy duration by 10-12 months versus later-line use, as demonstrated in the PRIMA trial where niraparib yielded a 5-year progression-free survival (PFS) rate of 35% in HRD-positive ovarian cancer. Extended exposure drives higher cumulative sales and strengthens class incumbency.
High Cost of HRD / BRCA Testing Limiting Eligible Patient Pool
Comprehensive genomic profiling costs USD 3,500-5,800 per patient, limiting test uptake to 47% of guideline-eligible ovarian-cancer cases in the United States. The affordability gap is wider in low- and middle-income regions, shrinking the real-world funnel of patients who can access targeted therapies.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Synthetic-Lethality Combination Regimens
- Shift Toward Oral Oncolytics in Oncology Formularies
- Safety Signals-Myelosuppression & MDS/AML-Capping Duration of Therapy
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PARP inhibitors retained 49.02% of the DNA repair drugs market share in 2025, underpinned by mature commercial footprints across ovarian, breast, and prostate cancers. The DNA repair drugs market size for this class is projected to expand steadily, although competitive intensity is rising. Momentum is shifting toward ATM kinase inhibitors, forecast to clock a 18.92% CAGR as lartesertib and other pipeline agents enter late-phase trials. Their appeal lies in activity against tumors harboring ATM loss, which encompasses 5-8% of prostate, pancreatic, and gastric cancers.
Early data show objective responses in tumors previously refractory to PARP therapy, positioning the segment as a resistance-management option. Manufacturers are layering ATM inhibitors into frontline trials, accelerating potential uptake. Continuous-dosing oral formulations further align with the health-system trend toward ambulatory oncology, bolstering channel penetration through specialty pharmacies. Collectively, pipeline depth suggests ATM inhibitors may erode the incumbent lead of PARP agents by 2030, when first-generation products face patent expiry.
Ovarian cancer generated 38.72% of 2025 revenue because of entrenched PARP maintenance protocols and the highest prevalence of HRD. The DNA repair drugs market size attached to this indication remains robust, yet growth is moderating as penetration approaches saturation in developed markets. In contrast, prostate cancer is pacing the field with an 17.86% CAGR owing to compelling overall-survival gains with olaparib-abiraterone doublets that lifted median survival to 42.1 months.
Beyond metastatic castration-resistant prostate cancer, sponsors are now testing combinations in hormone-sensitive and localized settings, potentially quadrupling the eligible patient base. Heightened NGS adoption-spurred by APODDC guidelines-will further raise diagnostic capture rates across Asia Pacific, reinforcing demand growth. Simultaneously, pancreatic and colorectal cancers are moving up the opportunity curve as synthetic-lethal partners magnify PARP activity in tumors without BRCA mutations.
Complete Report Scope:
- By Drug Type
- PARP Inhibitors
- ATM Kinase Inhibitors
- ATR Inhibitors
- DNA-PK Inhibitors
- Other Drug Types
- By Indication
- Ovarian Cancer
- Breast Cancer
- Prostate Cancer
- Pancreatic Cancer
- Glioblastoma & CNS Tumors
- Other Indications
- By Line of Therapy
- First-Line Maintenance
- Second-/Subsequent-Line Treatment
- By Distribution Channel
- Hospital Pharmacies
- Specialty & Retail Pharmacies
- Online Pharmacies
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 47.35% of 2025 revenue, anchored by early regulatory approvals and payer coverage for HRD testing. Integrated health-system ownership of specialty pharmacies promotes seamless genomic test-to-treatment conversion, propelling steady volume growth. The region also hosts the highest density of combination trials exploring ATR-PARP and PARP-checkpoint inhibitor regimens, ensuring rapid uptake of future approvals.
Asia Pacific is the fastest-growing territory, advancing at 16.35% through 2031 as precision-oncology initiatives unlock pent-up demand. China's 2025 approval of senaparib for first-line ovarian maintenance-based on the FLAMES Study-illustrates accelerating regulatory momentum. Japan and South Korea are updating reimbursement schedules to include multigene HRD panels, elevating test adoption rates above 60%. India and Southeast Asian markets remain underpenetrated but are trending upward as local contract research organizations bring cost-efficient trials to the region.
Europe holds the second-largest share and is expanding at a steady 12.21% CAGR. National reimbursement bodies increasingly mandate biomarker-driven frameworks, aligning with EMA favorable benefit-risk assessments for new DDR agents. South America and the Middle East and Africa are tracking 12.96% and 14.66% CAGRs, respectively, albeit from lower baselines. Multinational firms are piloting tiered-pricing strategies and public-private diagnostic partnerships to overcome affordability barriers. Expansion of tertiary oncology centers across Brazil, Saudi Arabia and the United Arab Emirates is expected to widen clinical trial participation, bolstering physician familiarity with DDR mechanisms.
- Abbvie
- Allarity Therapeutics Inc.
- Antengene Corporation Limited
- Artios Pharma Ltd.
- AstraZeneca
- Breakpoint Therapeutics GmbH
- FoRx Therapeutics AG
- GlaxoSmithKline
- Ideaya Biosciences
- Johnson & Johnson
- Merck
- Novartis
- Pfizer
- Rakovina Therapeutics Inc.
- Repare Therapeutics Inc.
- Tolmar, Inc
- Valerio Therapeutics
- Zai Lab Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Incidence of HR-Deficient Solid Tumours
- 4.2.2 Label Expansion of PARP Inhibitors into Early-Line & Maintenance Settings
- 4.2.3 Adoption of Synthetic-Lethality Combination Regimens
- 4.2.4 Shift Toward Oral Oncolytics in Oncology Formularies
- 4.2.5 Accelerated Regulatory Pathways Shortening Time-to-Market
- 4.2.6 Public Precision-Oncology Initiatives Driving Companion-Dx Uptake
- 4.3 Market Restraints
- 4.3.1 High Cost of HRD / BRCA Testing Limiting Eligible Patient Pool
- 4.3.2 Safety Signals-Myelosuppression & MDS/AML-Capping Duration of Therapy
- 4.3.3 Escalating Payer Scrutiny on Overall-Survival Benefit vs. Standard Chemotherapy
- 4.3.4 Patent Cliff 2028-30 for First-Wave PARP Inhibitors Dampening Revenue Visibility
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Drug Type
- 5.1.1 PARP Inhibitors
- 5.1.2 ATM Kinase Inhibitors
- 5.1.3 ATR Inhibitors
- 5.1.4 DNA-PK Inhibitors
- 5.1.5 Other Drug Types
- 5.2 By Indication
- 5.2.1 Ovarian Cancer
- 5.2.2 Breast Cancer
- 5.2.3 Prostate Cancer
- 5.2.4 Pancreatic Cancer
- 5.2.5 Glioblastoma & CNS Tumors
- 5.2.6 Other Indications
- 5.3 By Line of Therapy
- 5.3.1 First-Line Maintenance
- 5.3.2 Second-/Subsequent-Line Treatment
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Specialty & Retail Pharmacies
- 5.4.3 Online Pharmacies
- 5.5 By Geography (Value)
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Competitive Benchmarking
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 AbbVie Inc.
- 6.4.2 Allarity Therapeutics Inc.
- 6.4.3 Antengene Corporation Limited
- 6.4.4 Artios Pharma Ltd.
- 6.4.5 AstraZeneca PLC
- 6.4.6 Breakpoint Therapeutics GmbH
- 6.4.7 FoRx Therapeutics AG
- 6.4.8 GlaxoSmithKline PLC
- 6.4.9 Ideaya Biosciences
- 6.4.10 Johnson & Johnson (Janssen)
- 6.4.11 Merck KGaA (EMD Serono)
- 6.4.12 Novartis AG
- 6.4.13 Pfizer Inc.
- 6.4.14 Rakovina Therapeutics Inc.
- 6.4.15 Repare Therapeutics Inc.
- 6.4.16 Tolmar, Inc
- 6.4.17 Valerio Therapeutics
- 6.4.18 Zai Lab Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

