PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116492

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116492
Medical Scheduling Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the medical scheduling software market size in 2026 is estimated at USD 496.19 million, growing from 2025 value of USD 443.34 million with 2031 projections showing USD 871.65 million, growing at 11.92% CAGR over 2026-2031.
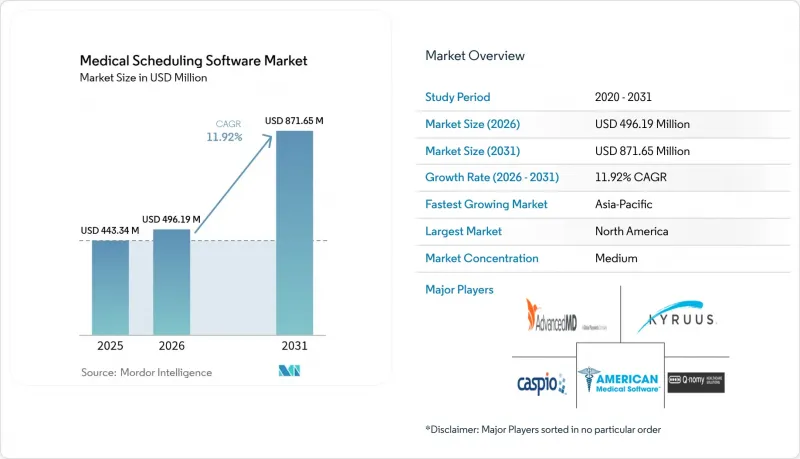
This report is Segmented by Product Type (Patient Scheduling, Care Provider Scheduling, Others), Deployment Model (Cloud-Based, On-Premise, Hybrid), End User (Hospitals, Clinics, Ambulatory Surgical Centers, and More), Specialty (Primary Care, Dentistry, Behavioral and Mental Health, Others), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Scheduling Software Market Trends and Insights
Increasing Demand to Efficiently Manage & Optimize Workflow
Manual appointment coordination consumes up to half a day of administrative time per month in the average ambulatory facility, driving leaders to automate template creation, wait-list handling, and resource balancing. A Florida-based health system saved USD 2 million in contract labor by shrinking the shift-planning cycle from three business days to less than four hours. Predictive scheduling has also dropped labor costs 8% at large academic centers, while simultaneously lifting provider satisfaction scores. Executives increasingly view streamlined scheduling as a lever to bolster net operating margins, curb staff burnout, and improve patient throughput .
Rising Adoption of Patient-Centric Care Models
Eight in ten U.S. consumers prefer to set appointments online, and more than half of self-service bookings originate from new patients. Digital convenience lowers missed-visit risk by 17% and enlarges clinics' new-patient funnel by over one-third. Millennials remain the most prolific users, yet nearly 40% of bookings placed through self-scheduling portals come from patients aged >40 years. Providers that embed real-time slot visibility and automated reminders into websites and mobile apps are therefore outpacing peers on both acquisition and retention metrics.
Risk of Data Security Breaches & Cyber-Attacks
Health records remain the most valuable data category on the dark web, and breaches rose for a third consecutive year. Security fears deter 60% of non-migrated providers from moving scheduling to the cloud. HIPAA, GDPR, and emerging U.S. state privacy laws demand multi-layer encryption, role-based access, and audit trails. Breach remediation can cost USD 9.5 million per incident, diverting budgets away from new deployments. Vendors that maintain SOC 2 and HITRUST certifications are consequently gaining a competitive edge.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Shift Toward Cloud-Native Healthcare IT Stacks
- Expansion of Telehealth & Remote Consultations
- Shortage of Skilled Health-IT Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The patient-scheduling segment generated 58.25% revenue in 2025-the highest within the medical scheduling software market size-as hospitals prioritized frictionless consumer access. Platforms now embed AI suggestions to propose optimal physician-patient matches, boosting completed-visit ratios by 9%. Care-provider scheduling, the fastest-expanding niche at 12.64% CAGR, benefits from modules that map acuity scores against staffing skillsets to reduce understaffing penalties.
Integrators increasingly combine both modules so a vacant provider slot automatically surfaces to patients, uniting demand and capacity management. Advanced provider-scheduling suites supervise duty-hour compliance, fatigue indices, and licensure alerts, further tightening quality control. Vendors that bundle these capabilities are differentiating in request-for-proposal (RFP) cycles, especially among IDNs operating across multiple time zones.
Public-cloud rollouts contributed 69.10% of 2025 revenue, reinforcing cloud as the default backbone of the medical scheduling software market. Multitenant architectures accelerate quarterly feature drops, keep version skew low, and provide API toolkits for omnichannel patient engagement. Nonetheless, hybrid models will climb at 12.70% CAGR as providers isolate sensitive clinician payroll data on-premise while steering consumer-facing workflows toward hyperscale data centers.
Edge-compute nodes inside hospital data rooms handle latency-sensitive image uploads or real-time surgery updates, while bulk analytics and AI training run in the cloud. This split mitigates bandwidth constraints and supports national-data-residency statutes now active in 65+ jurisdictions worldwide. Vendors able to orchestrate workload placement seamlessly are seeing longer contract tenures and higher net-promoter scores.
Complete Report Scope:
- By Product Type
- Patient Scheduling
- Care Provider Scheduling
- Others
- By Deployment Model
- Cloud-Based
- On-Premise
- Hybrid
- By End User
- Hospitals
- Clinics
- Ambulatory Surgical Centers
- Telehealth Providers
- Others
- By Specialty
- Primary Care
- Dentistry
- Behavioral and Mental Health
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 42.10% of global revenue in 2025 on the strength of mature EHR penetration, payer reimbursement mandates favoring electronic workflows, and a consolidated hospital network eager to scale AI pilots into production. Epic Systems added 176 facilities to its Cadence install base, while Oracle Health lost ground, illustrating momentum shifts based on scheduling-module performance. Yet saturation among tier-one health systems is slowing incremental license expansion, opening space for cost-conscious regional hospitals to experiment with lighter SaaS entrants.
Europe posts stable single-digit growth underpinned by coordinated e-health regulations and investments targeting cross-border interoperability. Country-level privacy statutes necessitate configurable consent tracking and in-language patient-facing screens. National Health Service trusts in the United Kingdom recently mandated open-Booking APIs, elevating vendor scoring criteria focused on standards adherence. Eastern European clinics, retooling post-pandemic, increasingly adopt subscription models bundled with outcome-based contracting.
Asia-Pacific, forecast at 13.02% CAGR, remains the prime acceleration zone. Public-private funding blends in India and Indonesia subsidize cloud scheduling for mid-size hospitals lacking robust IT teams. China's smart-hospital plan Phase III earmarks budget for AI triage and real-time scheduling dashboards in provincial centers. Local data-residency laws drive partnerships with domestic cloud providers, requiring multinational vendors to refactor code for onshore hosting.
The Middle East shows emergent momentum as Gulf Cooperation Council hospitals surpass 75% EHR adoption, paving the way for enterprise scheduling tie-ins. Africa and South America remain nascent but feature innovation sandboxes-mobile-first booking apps bundled with appointment-linked ride services-that could leapfrog legacy desktop systems once connectivity improves.
- PatientStudio
- Yocale Network
- Tinivia
- 10to8
- American Medical Software
- Kyruus
- Caspio
- AdvancedMD
- Q-nomy
- Terminapp
- SuperSaaS
- Biosoftworld Medical Software
- Vocantas
- Epic Systems
- Oracle Health (Cerner)
- AthenaHealth
- Qgenda
- PerfectServe
- Zocdoc
- Relatient
- NextGen Healthcare
- eClinicalWorks
- Meditech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing demand to efficiently manage & optimize workflow
- 4.2.2 Rising adoption of patient-centric care models
- 4.2.3 Accelerated shift toward cloud-native healthcare IT stacks
- 4.2.4 Expansion of telehealth & remote consultations
- 4.2.5 AI-driven dynamic capacity management adoption
- 4.2.6 Real-time insurance-verification integration
- 4.3 Market Restraints
- 4.3.1 Risk of data security breaches & cyber-attacks
- 4.3.2 Shortage of skilled health-IT professionals
- 4.3.3 Fragmented interoperability across specialty EHRs
- 4.3.4 Price-deflation from freemium scheduling apps
- 4.4 Regulatory Landscape
- 4.5 Porters Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Patient Scheduling
- 5.1.2 Care Provider Scheduling
- 5.1.3 Others
- 5.2 By Deployment Model
- 5.2.1 Cloud-Based
- 5.2.2 On-Premise
- 5.2.3 Hybrid
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Clinics
- 5.3.3 Ambulatory Surgical Centers
- 5.3.4 Telehealth Providers
- 5.3.5 Others
- 5.4 By Specialty
- 5.4.1 Primary Care
- 5.4.2 Dentistry
- 5.4.3 Behavioral and Mental Health
- 5.4.4 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 PatientStudio
- 6.3.2 Yocale Network Corporation
- 6.3.3 Tinivia
- 6.3.4 10to8 Ltd.
- 6.3.5 American Medical Software
- 6.3.6 Kyruus
- 6.3.7 Caspio
- 6.3.8 AdvancedMD, Inc.
- 6.3.9 Q-nomy Inc.
- 6.3.10 Terminapp GmbH
- 6.3.11 SuperSaaS
- 6.3.12 Biosoftworld Medical Software
- 6.3.13 Vocantas Inc.
- 6.3.14 Epic Systems Corporation
- 6.3.15 Oracle Health (Cerner)
- 6.3.16 AthenaHealth
- 6.3.17 Qgenda
- 6.3.18 PerfectServe
- 6.3.19 Zocdoc
- 6.3.20 Relatient
- 6.3.21 NextGen Healthcare
- 6.3.22 eClinicalWorks
- 6.3.23 MEDITECH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

