PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116522

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116522
Digital Dentistry - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the digital dentistry market size is projected to expand from USD 9.61 billion in 2025 and USD 10.53 billion in 2026 to USD 16.67 billion by 2031, registering a CAGR of 9.62% between 2026 and 2031.
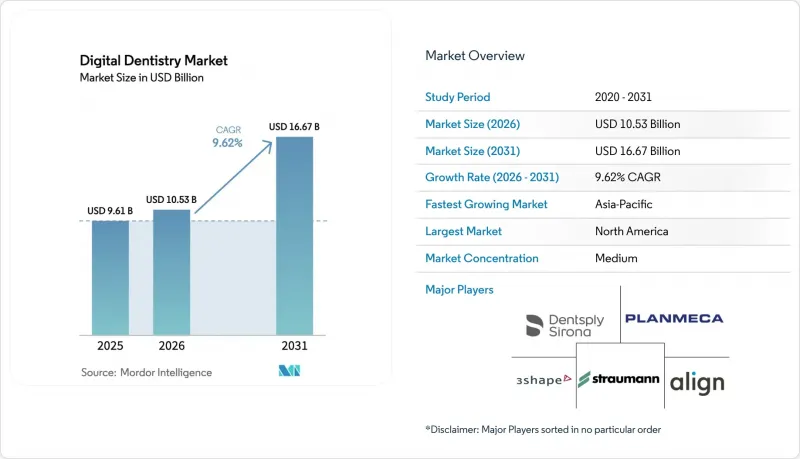
This report is Segmented by Type (Instruments [CAD/CAM Systems, Dental Software, Sensors and IoT Devices, and More] and Consumables), Specialty (Restorative Dentistry, Prosthodontics, Orthodontics, and More), End User (Hospitals, Dental Clinics, Dental Laboratories, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market and Forecasts are Provided in Terms of Value (USD).
Global Digital Dentistry Market Trends and Insights
Rapid Adoption of Chairside CAD/CAM Systems
Chairside CAD/CAM units cut restorative workflows from two appointments across 10-14 days to a single 90-minute visit, freeing late-afternoon slots for higher-margin crowns. Dentsply Sirona's CEREC Cercon 4D Abutment, cleared in May 2024, lets practitioners mill titanium-base abutments in-office, eliminating USD 150-250 laboratory fees per case. Solventum and SprintRay are co-developing chairside 3D-printed permanent crowns for a USD 7.5 billion global restoration pool, leveraging 20,000 installed printers to fuse ceramic-like esthetics with resin economics. Such advances raise throughput without extra operatory build-out, reinforcing the digital dentistry market's appeal to high-volume practices. Subscription-based equipment bundles that convert capital expenditure into operating expense further widen access among volume-constrained dentists.
Growing Geriatric Edentulous Population
Individuals aged 65+ will constitute 16% of the world's population by 2030, expanding full-arch restoration demand in North America, Europe and mature Asia-Pacific markets. Digital denture workflows trim patient visits from five to three, lowering chair time by 40% while automated occlusal algorithms improve fit. A 2024 Journal of Prosthetic Dentistry study reported milled dentures show 30-50% lower vertical dimension error than compression-molded acrylic, cutting post-delivery adjustments. Labs responding to geriatric case-mix are investing in 5-axis mills and multi-material 3D printers; 3D Systems' NextDent Denture 3D+ resin, FDA-cleared in September 2024, enables base-and-tooth co-printing. These gains reinforce long-term unit volumes that underpin the digital dentistry market.
High Upfront Equipment and Maintenance Costs
Intraoral scanners cost USD 30,000-50,000, mills USD 80,000-120,000 and furnaces USD 15,000-25, creating a steep entry barrier for volume-constrained practices. Annual service adds USD 5,000-8,000 per device. Break-even requires 300-500 restorative cases, a volume 40% of U.S. offices cannot reach. Subscription bundles such as Dentsply Sirona's USD 1,200-per-month CEREC plan convert capex to opex, lowering risk and preserving vendor revenue. Until financing models proliferate, high costs will temper short-term diffusion of the digital dentistry market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Cosmetic/Aesthetic Dentistry
- Consolidation of DSOs Pooling Capex for Digital Tech
- Limited Reimbursement of Digital Restorations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Instruments accounted for 75.54% of revenue in 2025 and are forecast to grow at 10.25% through 2031 as practices prioritize capability-unlocking equipment ahead of recurring materials. Within this category, imaging systems form the digital twin that anchors every downstream workflow, cementing their must-buy status in the digital dentistry market. Chairside CAD/CAM units replace laboratory turnaround with same-day restorations, letting clinics internalize lab margins. Dentsply Sirona's Primescan 2 wireless scanner completes full-arch scans in under 60 seconds and uploads to cloud CAD hubs, enabling overnight offshore design services that stretch chair productivity.
3D printers and mills are converging as hybrid units emerge, letting labs toggle between subtractive and additive fabrication without doubling floor space. Software is shifting to subscription bundles that fold practice management, imaging viewers and AI triage into USD 300-500 per-provider monthly plans. Sensors and IoT-enabled handpieces remain niche but rising, feeding predictive-maintenance dashboards that cut downtime. Consumables expand more slowly because digital impressions eliminate 90% of polyvinyl siloxane waste, lowering volumes even as unit prices for resins and ceramics rise. The digital dentistry market size for consumables still scales with installed equipment, but margin leverage is strongest on high-utility instruments.
Complete Report Scope:
- By Product Type
- Instrument
- Imaging Systems
- Intra-oral Scanners
- CBCT & Digital X-ray
- CAD/CAM Systems
- Chairside Systems
- Laboratory Systems
- 3-D Printing Equipment
- Milling Machines
- Dental Software
- Sensors & IoT Devices
- Accessories & Services
- Imaging Systems
- Consumables
- Instrument
- By Specialty
- Restorative Dentistry
- Prosthodontics
- Orthodontics
- Implantology
- Endodontics
- Periodontics
- By End User
- Dental Clinics
- Dental Service Organizations (DSOs)
- Dental Laboratories
- Hospitals
- Academic & Research Institutes
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 38.53% of 2025 revenue, buoyed by early AI approvals, mature insurance coverage and high DSO density. The U.S. leads scanner and CBCT replacement cycles, though growth moderates as installed bases mature. Canada mirrors these patterns, albeit with slower DSO penetration due to differing provincial reimbursement. Regulatory clarity from the FDA on AI/ML SaMD keeps venture capital active, sustaining North American innovation nodes within the digital dentistry market.
Europe contributes steady volume underpinned by universal dental coverage and strict Medical Device Regulation oversight that stretches product launch timelines but elevates safety. Straumann derived 46% of 2024 revenue from EMEA, capitalizing on dense implantology networks in Germany, France and Italy. Southern European economies adopt digital workflows more slowly, restrained by lower discretionary spending, yet public procurement of imaging systems is rising under EU recovery-fund allocations.
Asia-Pacific is the fastest-growing geography at a 10.1% CAGR to 2031, propelled by China's digital-health mandates and India's expanding middle-class appetite for cosmetic procedures. Chinese state-owned dental chains are bulk-ordering intraoral scanners to standardize treatment quality, while Indian clinics market same-day veneers to dental-tourism clients. Japan and South Korea leverage aging demographics to scale full-arch restoration volumes. Southeast Asia lags but leapfrogs with mobile-based smile-design apps that funnel patients to urban hubs. Collectively the region enlarges the digital dentistry market size, offsetting North American saturation.
The Middle East and Africa remain nascent: high-end private clinics in the Gulf import CAD/CAM suites for affluent patients, yet public systems rely on analog impressions. Latin America shows city-center adoption; Sao Paulo and Buenos Aires house boutique practices offering clear aligners at 40-60% below U.S. prices, expanding digital dentistry market share despite macro volatility.
- Align Technology
- Dentsply Sirona
- Solventum Corporation
- Ivoclar Vivadent
- Straumann Group
- Envista Holdings (Kerr, Nobel Biocare)
- Planmeca
- 3 Shape
- Formlabs Inc.
- Stratasys
- Carestream Dental
- Vatech Co. Ltd.
- Kulzer
- GC Corporation
- J. Morita Corp.
- Apteryx Imaging (Planet DDS)
- Amann Girrbach
- Exocad GmbH
- Zimvie
- Shofu Inc.
- Voco GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Chairside CAD/CAM Systems
- 4.2.2 Growing Geriatric Edentulous Population
- 4.2.3 Rising Demand for Cosmetic / Aesthetic Dentistry
- 4.2.4 Consolidation of DSOs Pooling Capex for Digital Tech
- 4.2.5 Regulatory Green-Lights for 3D-Printable Permanent Ceramic Crowns
- 4.2.6 Open-Architecture Intraoral Scanners Accelerating Third-Party AI Apps
- 4.3 Market Restraints
- 4.3.1 High Upfront Equipment & Maintenance Costs
- 4.3.2 Limited Reimbursement of Digital Restorations
- 4.3.3 Vendor Lock-In to Closed CAD/CAM Ecosystems
- 4.3.4 Post-Market Algorithm Drift Triggering New Regulatory Oversight
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Instrument
- 5.1.1.1 Imaging Systems
- 5.1.1.1.1 Intra-oral Scanners
- 5.1.1.1.2 CBCT & Digital X-ray
- 5.1.1.2 CAD/CAM Systems
- 5.1.1.2.1 Chairside Systems
- 5.1.1.2.2 Laboratory Systems
- 5.1.1.3 3-D Printing Equipment
- 5.1.1.4 Milling Machines
- 5.1.1.5 Dental Software
- 5.1.1.6 Sensors & IoT Devices
- 5.1.1.7 Accessories & Services
- 5.1.1.1 Imaging Systems
- 5.1.2 Consumables
- 5.1.1 Instrument
- 5.2 By Specialty
- 5.2.1 Restorative Dentistry
- 5.2.2 Prosthodontics
- 5.2.3 Orthodontics
- 5.2.4 Implantology
- 5.2.5 Endodontics
- 5.2.6 Periodontics
- 5.3 By End User
- 5.3.1 Dental Clinics
- 5.3.2 Dental Service Organizations (DSOs)
- 5.3.3 Dental Laboratories
- 5.3.4 Hospitals
- 5.3.5 Academic & Research Institutes
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Align Technology Inc.
- 6.3.2 Dentsply Sirona
- 6.3.3 Solventum Corporation
- 6.3.4 Ivoclar Vivadent
- 6.3.5 Straumann Group
- 6.3.6 Envista Holdings (Kerr, Nobel Biocare)
- 6.3.7 Planmeca Oy
- 6.3.8 3Shape A/S
- 6.3.9 Formlabs Inc.
- 6.3.10 Stratasys Ltd.
- 6.3.11 Carestream Dental LLC
- 6.3.12 Vatech Co. Ltd.
- 6.3.13 Kulzer GmbH
- 6.3.14 GC Corporation
- 6.3.15 J. Morita Corp.
- 6.3.16 Apteryx Imaging (Planet DDS)
- 6.3.17 Amann Girrbach AG
- 6.3.18 Exocad GmbH
- 6.3.19 Zimvie
- 6.3.20 Shofu Inc.
- 6.3.21 Voco GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

