PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116527

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116527
Operating Room Integration - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the operating room integration market size is expected to grow from USD 2.87 billion in 2025 to USD 3.18 billion in 2026 and is forecast to reach USD 5.33 billion by 2031 at 10.88% CAGR over 2026-2031.
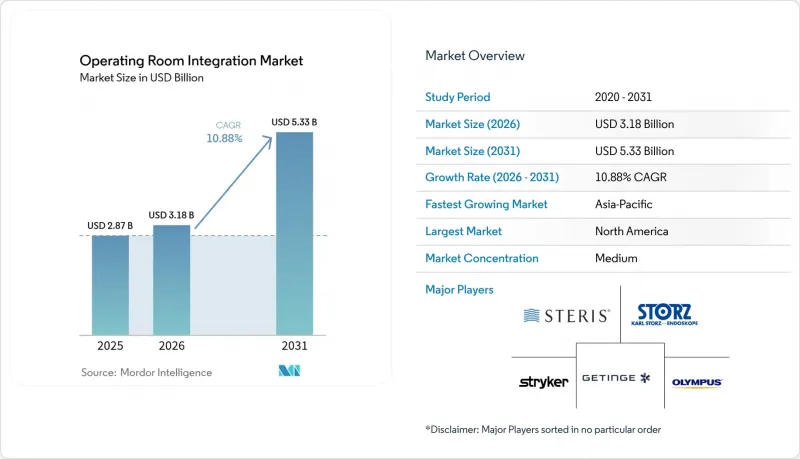
This report is Segmented by Component (Software, Services, Hardware), Application (General Surgery, Orthopedic Surgery, Cardiovascular Surgery, Neurosurgery, Urology & Gynecology), End-User (Large Hospitals, Small & Mid-Size Hospitals, Ascs), or Type (Hybrid ORs, Integrated Digital ORs), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Operating Room Integration Market Trends and Insights
Rise in Number of Surgical Procedures
Hospitals worldwide are booking fuller operating schedules as aging populations and chronic conditions fuel procedure demand. Integrated workflow software helps teams turn over theatres faster, allocate instruments efficiently, and shorten anesthesia times. The payoff is clearest in robot-assisted cases where platforms such as da Vinci Xi achieve accuracy above 90%, sharply reducing costly revisions and freeing capacity for additional patients. These throughput gains make operating room integration market implementations financially attractive, particularly for systems facing strained staffing and reimbursement pressures.
Rapid Uptake of Minimally Invasive & Image-Guided Surgeries
Laparoscopic and endovascular techniques require simultaneous visualization of high-resolution video, fluoroscopy, and navigation data. Augmented-reality overlays have improved precision in microsurgical fields and neurosurgery, streamlining complex instrument maneuvers.Hospitals therefore prioritize interoperable video routing, low-latency image processing, and sterile touch interfaces, all of which propel the operating room integration market.
High Capital & Lifecycle Maintenance Cost of OR Integration
Beyond initial hardware, hospitals must fund software licenses, patch management, and staff retraining, often surpassing upfront spend over a decade. Smaller campuses with limited surgical throughput struggle to clear return-on-investment thresholds, slowing penetration in community settings.
Other drivers and restraints analyzed in the detailed report include:
- Hospital Investments in Digital/IoT-Enabled OR Platforms
- Post-Pandemic Backlog Reduction Programs
- Lengthy Procurement Cycles & Budget Freezes in Public Hospitals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software accounted for 44.12% of 2025 revenue, underscoring the migration from cabling and routers toward data orchestration, workflow guidance, and AI-based predictive alerts. Service contracts are forecast to rise at a 14.57% CAGR as customers recognize that every upgrade introduces change-management and cybersecurity tasks best handled by specialists. In contrast, commoditized hardware such as ceiling booms and monitor arms delivers solid but slower growth. The operating room integration market size for services is projected to expand from USD 1.28 billion in 2025 to USD 2.9 billion by 2031, mirroring the industry's pivot to recurring revenue. AI-enabled platforms, including KARL STORZ's Artisight collaboration, reveal how real-time analytics lower turnover times and elevate staff satisfaction.
Purpose-built middleware integrates multi-vendor imaging, anesthesia records, and pathology reports into a unified timeline that surgeons can query intra-operatively. Hospitals cite automated preference-card management and predictive device servicing as the top two software benefits. These capabilities reinforce the view that the operating room integration market will reward vendors that deliver open APIs, granular cybersecurity controls, and intuitive dashboards rather than isolated display routers.
General surgery commanded 36.25% revenue share in 2025 due to sheer case volume, yet neurosurgery will grow fastest at a 13.22% CAGR as frameless navigation, robotic scaffolds, and intra-operative CT imaging become routine. The operating room integration market size associated with neurosurgery is projected to nearly double by 2031. Integrated guidance systems have already pushed pedicle-screw placement accuracy to 99% in hybrid rooms, slashing revision operations and radiation exposure.
Cardiovascular, orthopedics, and urology maintain healthy shares, but their growth hinges on procedure migration to outpatient and catheter-based labs. Neurosurgery's insistence on zero-latency imaging, redundant power, and vibration control makes it the bellwether for next-generation suite specifications. Hospitals aligning early with this trajectory future-proof their investment and solidify referral pipelines, supporting wider growth in the operating room integration market.
Complete Report Scope:
- By Component
- Software
- Services
- Hardware (AV management, surgical displays, OR booms, lights)
- By Application
- General Surgery
- Orthopedic Surgery
- Cardiovascular Surgery
- Neurosurgery
- Urology & Gynecology
- By End-User
- Large Hospitals (>=500 beds)
- Small & Mid-size Hospitals (<500 beds)
- Ambulatory Surgical Centers (ASCs)
- By OR Type
- Hybrid Operating Rooms
- Integrated Digital ORs (non-hybrid)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 39.12% of 2025 revenue on the back of entrenched hospital networks, reimbursement clarity, and early adoption of digital health mandates. Systems leverage predictive scheduling tools to recapture elective volumes that fell during the pandemic. The operating room integration market size in the United States alone surpassed USD 1.1 billion in 2025. Canada's publicly funded model adds momentum through national backlog-reduction funds that earmark capital for integrated theatres.
Europe remains a mature yet innovative cluster. Sustainability directives spur replacement of legacy halogen lighting with LED arrays and demand life-cycle assessments for every large capital project. High-profile programs such as Germany's Hospital Future Act disburse grants for interoperability upgrades, sustaining steady adoption. Meanwhile, stringent procurement laws lengthen decision cycles, tempering the operating room integration market's growth rate relative to North America.
Asia-Pacific represents the breakout region with a forecast 13.94% CAGR. China's public hospitals scale AI-enabled smart wards and adopt hybrid theatres to handle rising vascular and oncology caseloads. Japan advances showcase projects like Sapporo Kashiwabakai Hospital, where Siemens Healthineers engineered a fully digital, patient-centric "Smart-OR" that shortens emergency transfer times. India and Southeast Asia emphasize modular, cost-optimized suites suited to constrained budgets but high procedure growth, broadening the operating room integration market.
Latin America and the Middle East & Africa post modest uptake impeded by currency volatility and infrastructure gaps. Nonetheless, selected private groups invest strategically to attract medical tourism and retain top surgical talent, laying the groundwork for future expansion.
- Stryker
- Karl Storz
- STERIS
- Olympus
- Getinge
- Brain Lab
- Canon
- Merivaara
- Skytron
- Doricon Medical Systems
- Barco NV
- Sony Medical Solutions
- EIZO Corp.
- Baxter
- Richard Wolf
- Koninklijke Philips
- Siemens Healthineers
- Conmed
- B. Braun
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise In Number Of Surgical Procedures
- 4.2.2 Rapid Uptake Of Minimally-Invasive & Image-Guided Surgeries
- 4.2.3 Hospital Investments In Digital/IoT-Enabled OR Platforms
- 4.2.4 Post-Pandemic Backlog Reduction Programs (North America & EU)
- 4.2.5 IP-Based 4K/8K Video Routing Enabling Remote Collaboration
- 4.2.6 ESG-Driven Demand For Energy-Efficient, Modular OR Infrastructure
- 4.3 Market Restraints
- 4.3.1 High Capital & Lifecycle Maintenance Cost Of OR Integration
- 4.3.2 Lengthy Procurement Cycles & Budget Freezes In Public Hospitals
- 4.3.3 Shortage Of Biomedical IT Personnel For Complex OR Networking
- 4.3.4 Cyber-Security & Data-Privacy Risks In Connected ORs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.1.3 Hardware (AV management, surgical displays, OR booms, lights)
- 5.2 By Application
- 5.2.1 General Surgery
- 5.2.2 Orthopedic Surgery
- 5.2.3 Cardiovascular Surgery
- 5.2.4 Neurosurgery
- 5.2.5 Urology & Gynecology
- 5.3 By End-User
- 5.3.1 Large Hospitals (>=500 beds)
- 5.3.2 Small & Mid-size Hospitals (<500 beds)
- 5.3.3 Ambulatory Surgical Centers (ASCs)
- 5.4 By OR Type
- 5.4.1 Hybrid Operating Rooms
- 5.4.2 Integrated Digital ORs (non-hybrid)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Stryker Corporation
- 6.3.2 KARL STORZ SE & Co. KG
- 6.3.3 STERIS plc
- 6.3.4 Olympus Corporation
- 6.3.5 Getinge AB
- 6.3.6 Brainlab AG
- 6.3.7 Canon Medical Systems Corp.
- 6.3.8 Merivaara Corp.
- 6.3.9 Skytron LLC
- 6.3.10 Doricon Medical Systems
- 6.3.11 Barco NV
- 6.3.12 Sony Medical Solutions
- 6.3.13 EIZO Corp.
- 6.3.14 Baxter
- 6.3.15 Richard Wolf GmbH
- 6.3.16 Philips Healthcare
- 6.3.17 Siemens Healthineers
- 6.3.18 Conmed Corp.
- 6.3.19 B. Braun Melsungen AG
- 6.3.20 Zimmer Biomet Holdings
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

