PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116531

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116531
Attention Deficit Hyperactivity Disorder - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
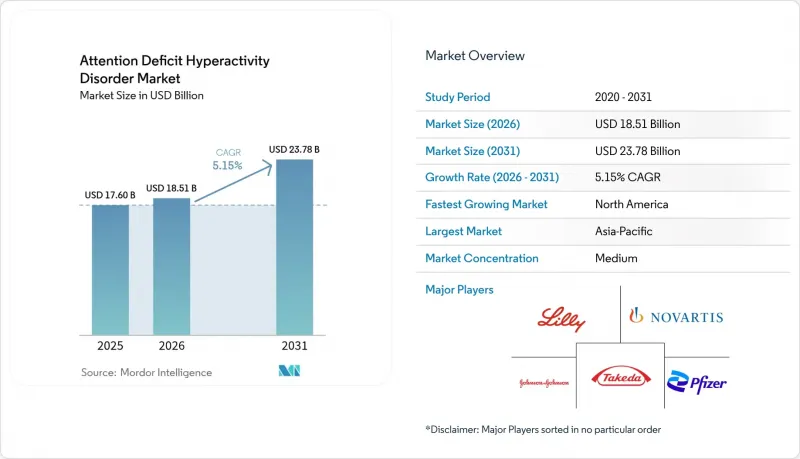
According to Mordor Intelligence, the attention deficit hyperactivity disorder market size was valued at USD 17.60 billion in 2025 and estimated to grow from USD 18.51 billion in 2026 to reach USD 23.78 billion by 2031, at a CAGR of 5.15% during the forecast period (2026-2031).
This report is Segmented by Drug Type (Stimulant and Non-Stimulant), Age Group (Children (<=17 Years) and Adults (>=18 Years)), Distribution Channel (Retail Pharmacy, Hospital Pharmacy, and Online Pharmacy), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Attention Deficit Hyperactivity Disorder Market Trends and Insights
Rising ADHD Prevalence Worldwide
Global prevalence continues climbing: 12.0% of U.S. children aged 3-17 had an ADHD diagnosis in 2023, an uptick that stems from refined diagnostic criteria rather than sudden pathological change. Adult diagnoses pass 15.5 million in the United States, half confirmed after age 18, underscoring long-standing underrecognition. China's school-age prevalence reached 6.4%, with modelling indicating a peak caseload in 2029, signalling sizeable latent demand in emerging economies. Climbing prevalence syncs with prescription volumes; U.S. stimulant scripts rose 57.9% from 2012-2022, sustaining demand across therapeutic classes.
Growing Awareness and Screening Initiatives
Primary-care clinicians increasingly deploy validated screeners, trimming referral delays. The American Professional Society for ADHD and Related Disorders is finalising the first U.S. adult guideline, closing a long-standing gap in standardised assessment pathways. Telehealth broadens access: 46% of diagnosed adults used virtual consultations in 2024 and 30.5% secured prescriptions online. Canadian claims data show a 20% jump in ADHD medication reimbursements during 2024, an indicator of accelerated recognition.
Diagnostic Challenges and Underrecognition
Subjective symptom scoring and overlap with anxiety or mood disorders complicate clear-cut diagnosis. Absence of a biomarker forces clinicians to rely on multi-informant scales, generating both false negatives and false positives. Research on circulating micro-RNAs such as miR-140-3p advances but is years from routine use. Primary-care providers, especially in resource-limited settings, report low confidence in adult assessment, perpetuating unmet need. Cultural stigma further depresses help-seeking in Asia-Pacific, slowing attention deficit hyperactivity disorder market penetration despite public awareness drives.
Other drivers and restraints analyzed in the detailed report include:
- Advancements in Pharmacotherapy and Formulations
- Expanding Adult Patient Segment via Telehealth
- High Abuse Liability and Safety Concerns of Stimulants
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Stimulant products generated 67.88% of 2025 revenue, illustrating entrenched efficacy and prescriber familiarity. Yet non-stimulants logged a 7.32% CAGR, exceeding total attention deficit hyperactivity disorder market growth as safety-minded clinicians search for lower diversion risk. Lisdexamfetamine's patent expiry in 2024 unlocked generic competition; Granules India and Lupin secured FDA approvals, supplying cost-sensitive buyers. DEA production caps pressured amphetamine supply, nudging prescribers toward alternatives such as viloxazine and guanfacine.
Supernus Pharmaceuticals reported Qelbree sales of USD 241.3 million in 2024, a 72% jump year-on-year, signalling robust uptake of novel non-stimulant mechanisms. Atomoxetine use remained steady despite batch recalls elsewhere, underlining persistent need for once-daily options. Liquid clonidine (Onyda XR) now offers paediatric caregivers a nocturnal regimen that circumvents school-time dosing hurdles. Consequently, the attention deficit hyperactivity disorder market size for non-stimulants is forecast to expand faster than any subcategory through 2031.
Complete Report Scope:
- By Drug Type
- Stimulant
- Amphetamine
- Methylphenidate
- Dextroamphetamine
- Dexmethylphenidate
- Lisdexamfetamine Dimesylate
- Non-Stimulant
- Atomoxetine
- Bupropion
- Guanfacine
- Clonidine
- Stimulant
- By Age Group
- Children (<17 Years)
- Adults (>18 Years)
- By Distribution Channel
- Retail Pharmacy
- Hospital Pharmacy
- Online Pharmacy
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America, with 42.02% 2025 revenue, remains the anchoring geography. In 2023, U.S. pharmacies dispensed 45 million stimulant prescriptions, up from 35.5 million in 2019, indicating pervasive clinical adoption. Canada's claim volumes climbed 20% in 2024 after provinces widened coverage, reinforcing access. Regional innovation depth is notable: most first-in-class approvals-Onyda XR, solriamfetol, CTx-1301-originated or were trialled here, underscoring a pipeline advantage.
Europe offers a structurally mature but controlled environment. Post-pandemic, prescription volumes ran 16.4% above pre-COVID forecasts by 2022, signalling greater societal comfort with pharmacologic care. The EMA's green lights for Paxneury and Tuzulby added guanfacine and extended-release methylphenidate choices to paediatric algorithms. Germany spearheads digital therapeutics; EndeavorRx secured CE marking and a reimbursement code, accelerating adoption pathways.
Asia-Pacific delivers the fastest 6.42% CAGR, lifted by policy liberalisation and urbanising populations. Japan's government-backed biotech incentives catalyse neuroscience start-ups, widening clinical trial capacity. China's 6.4% paediatric prevalence equates to tens of millions of potential patients as screening scales nationally. India's manufacturers leverage FDA approvals-such as generic Vyvanse-to supply lower-priced options globally, reinforcing regional affordability. Remaining hurdles include rural service gaps and persisting stigma, but rising digital literacy mitigates some obstacles, suggesting the attention deficit hyperactivity disorder market will experience steady diffusion across megacities first, then into secondary centres.
- Takeda Pharmaceutical Co. (Shire)
- Novartis
- Johnson & Johnson
- Eli Lilly and Company
- Pfizer
- Mallinckrodt plc
- Supernus Pharmaceuticals
- Aytu BioPharma (NEOS Therapeutics)
- Ironshore Pharmaceuticals
- KemPharm Inc. (Corium)
- Tris Pharma
- Aurobindo Pharma
- Lupin
- Otsuka
- Hisamitsu Pharma (Noven)
- Purdue Pharma (Adlon)
- Corium
- Sun Pharmaceutical Inds.
- Amneal Pharmaceuticals
- H. Lundbeck
- Shionogi & Co. Ltd.
- Rhodes Pharmaceuticals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising ADHD Prevalence Worldwide
- 4.2.2 Growing Awareness and Screening Initiatives
- 4.2.3 Advancements in Pharmacotherapy and Formulations
- 4.2.4 Supportive Reimbursement and Coverage Policies
- 4.2.5 Expanding Adult Patient Segment Via Telehealth
- 4.2.6 Integration of Digital Therapeutics with Medication
- 4.3 Market Restraints
- 4.3.1 Diagnostic Challenges and Underrecognition
- 4.3.2 High Abuse Liability and Safety Concerns of Stimulants
- 4.3.3 Strict Regulatory Controls on Controlled Substances
- 4.3.4 Cost Containment Pressures from Healthcare Payers
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Buyers
- 4.5.3 Bargaining Power Of Suppliers
- 4.5.4 Threat Of Substitutes
- 4.5.5 Competitive Rivalry Intensity
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Drug Type
- 5.1.1 Stimulant
- 5.1.1.1 Amphetamine
- 5.1.1.2 Methylphenidate
- 5.1.1.3 Dextroamphetamine
- 5.1.1.4 Dexmethylphenidate
- 5.1.1.5 Lisdexamfetamine Dimesylate
- 5.1.2 Non-Stimulant
- 5.1.2.1 Atomoxetine
- 5.1.2.2 Bupropion
- 5.1.2.3 Guanfacine
- 5.1.2.4 Clonidine
- 5.1.1 Stimulant
- 5.2 By Age Group
- 5.2.1 Children (<17 Years)
- 5.2.2 Adults (>18 Years)
- 5.3 By Distribution Channel
- 5.3.1 Retail Pharmacy
- 5.3.2 Hospital Pharmacy
- 5.3.3 Online Pharmacy
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Takeda Pharmaceutical Co. (Shire)
- 6.3.2 Novartis AG
- 6.3.3 Johnson & Johnson (Janssen)
- 6.3.4 Eli Lilly & Co.
- 6.3.5 Pfizer Inc.
- 6.3.6 Mallinckrodt plc
- 6.3.7 Supernus Pharmaceuticals
- 6.3.8 Aytu BioPharma (NEOS Therapeutics)
- 6.3.9 Ironshore Pharmaceuticals
- 6.3.10 KemPharm Inc. (Corium)
- 6.3.11 Tris Pharma
- 6.3.12 Aurobindo Pharma
- 6.3.13 Lupin Ltd.
- 6.3.14 Otsuka Holdings
- 6.3.15 Hisamitsu Pharma (Noven)
- 6.3.16 Purdue Pharma (Adlon)
- 6.3.17 Corium Inc.
- 6.3.18 Sun Pharmaceutical Inds.
- 6.3.19 Amneal Pharmaceuticals
- 6.3.20 H. Lundbeck A/S
- 6.3.21 Shionogi & Co. Ltd.
- 6.3.22 Rhodes Pharmaceuticals
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

