PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116536

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116536
Dentures - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the global dentures market size was valued at USD 2.44 billion in 2025 and estimated to grow from USD 2.6 billion in 2026 to reach USD 3.56 billion by 2031, at a CAGR of 6.49% during the forecast period (2026-2031).
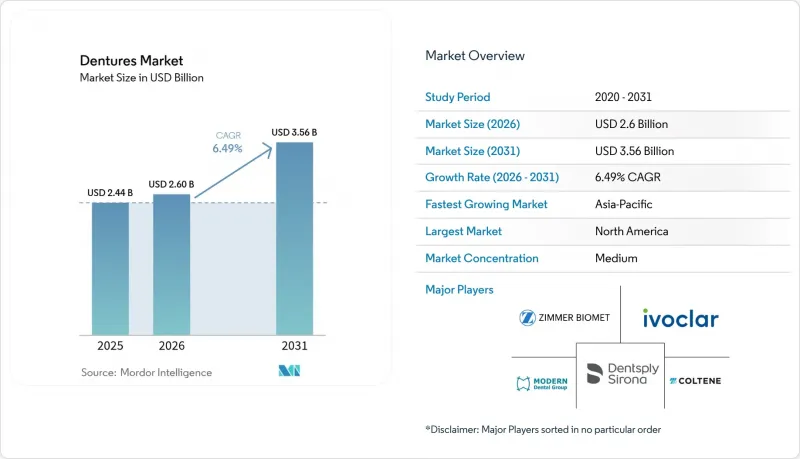
This report is Segmented by Product Type (Complete Dentures, and More), Usage (Fixed and Removable), Manufacturing Technology (Conventional Molding, and More), Material (Acrylic Resin, and More), End User (Dental Clinics & Hospitals, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Dentures Market Trends and Insights
Increasing Prevalence of Oral Health Disorders
Chronic periodontal disease and untreated caries continue to push millions toward tooth loss each year, sustaining the dentures market as edentulism remains widespread despite preventive care investments. A Global Burden of Disease assessment projected persistent high edentulism prevalence through 2050, underscoring denture therapy's long-term relevance. Geriatric oral-health programs now use multidisciplinary assessment models that flag complex prosthodontic needs earlier, channeling more candidates into denture workflow. Evidence also links poor oral status with chronic conditions such as diabetes and cardiovascular disease, adding urgency for timely prosthetic rehabilitation. Public perception is shifting 91% of adults rate dental visits as vital as annual physical exams, spotlighting oral treatment as preventive medicine. Ironically, broader preventive screenings reveal unmet tooth-replacement requirements, redirecting patients toward denture solutions.
Rapid Growth of Aging Population
Adults aged 65 and older represent the core consumer base for dentures, and their numbers are expanding faster than any other demographic group. Studies show that older adults who receive partial dentures experience slower cognitive decline, adding medical impetus to treatment. The current generation of seniors retains natural teeth longer, but once loss occurs, expectations for quality of life and dietary freedom drive demand for premium, digitally fabricated prostheses. Policymakers are likewise recognizing denture therapy as essential health maintenance rather than a cosmetic service, paving the way for improved reimbursement frameworks. As life expectancy rises, so does the cumulative period during which seniors require functional oral rehabilitation, making the dentures market a structural beneficiary of demographic aging.
High Treatment and Product Costs
Despite manufacturing advances, total treatment costs-including clinical time, imaging, and follow-up-remain a barrier, especially where insurance penetration is low. Traditional Medicare still excludes routine prosthodontics, leaving many seniors to self-fund denture therapy. Although Medicaid expansion has improved access in select U.S. states, fixed-income retirees in others continue to delay or forgo treatment. Smaller practices also struggle to justify capital outlays for digital equipment, reinforcing a cost gap between high-tech laboratories and conventional facilities. Even in Europe's socialized systems, budget constraints create waiting lists that push patients toward cheaper, out-of-pocket international alternatives.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advancements in Digital Denture Manufacturing
- Rising Demand for Aesthetic Dental Solutions
- Expansion of Dental Insurance Coverage
- Availability of Alternative Tooth Replacement Options
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Complete dentures represented 63.72% of global revenue in 2025, anchored by a large edentulous population that demands full-arch rehabilitation. This category improves oral-health quality of life by more than 9% within a year of wear, according to systematic clinical reviews. Digital workflows now permit precise duplication of established occlusal schemes, boosting acceptance among practitioners and patients. Partial dentures remain important for mixed-dentition cases, serving as a conservative, tooth-preserving option. The Other Types segment-primarily implant-retained overdentures and fixed hybrid prostheses-advances at an 8.25% CAGR as implant surgery becomes more affordable. Superior stability and reduced gag reflex are key selling points, particularly for younger edentulous patients who demand higher functionality. Overall, shifting patient expectations and cross-specialty collaboration will continue to realign type preference, yet complete dentures are expected to retain a commanding role in the dentures market through 2031.
Growing acceptance of hybrid solutions does not cannibalize traditional sales fully; instead, it extends the dentures market size by drawing in candidates previously skeptical of removable appliances. Many clinicians now offer a two-phase treatment pathway, starting with complete dentures for tissue conditioning and progressing to implant-supported configurations once bone remodeling stabilizes. This staged approach balances cost, surgical risk, and adaptation, ensuring dentures market continuity across all income brackets.
Removable appliances captured 70.58% share in 2025, favored for their non-invasive nature and immediate reversibility. Digital impression systems reduce gag reflex incidence and improve accuracy, alleviating key patient objections. Lower unit costs make removable dentures the mainstay in insurance reimbursement schedules, keeping them relevant in both public and private healthcare environments. Fixed options, largely dependent on implant fixtures, are growing at a 7.72% CAGR as new mini-implant protocols expand the eligible patient base. Chewing-efficiency studies consistently show fixed restorations outperforming removable variants, but the gap is narrowing as precision attachments and soft-liner materials improve removable stability.
Hybrid overdentures illustrate convergence: they clip onto bar or locator attachments while retaining daily removability for hygiene. This model delivers much of the stability of a fixed system while preserving the affordability of removable therapy. As clinicians integrate chairside CAD/CAM systems, patients can trial virtual setups, boosting confidence and uptake of both usage types across the dentures market.
Complete Report Scope:
- By Type
- Complete Dentures
- Partial Dentures
- Other Types
- By Usage
- Fixed
- Removable
- By Material
- Acrylic Resin
- Porcelain
- Metal-Ceramic
- Flexible (Nylon-Based)
- 3-D Printed Photopolymer
- By Manufacturing Technology
- Conventional Molding
- CAD/CAM Milled
- 3-D Printed Additive
- By End User
- Dental Clinics & Hospitals
- Dental Laboratories
- Academic & Research Institutes
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America dominated the dentures market with 42.11% revenue share in 2025, propelled by insurance reforms and broad adoption of chairside digital dentistry. Medicare rule changes taking effect in 2025 will reimburse medically necessary prosthodontic services linked to systemic treatments, lowering financial barriers. Medicaid's adult dental benefit extensions in nine states have likewise widened access. Denture manufacturers benefit from a thick network of dental-support organizations that quickly roll out technology upgrades system-wide, reinforcing regional leadership.
Asia-Pacific is the fastest-growing geography with a 7.74% CAGR to 2031. China's rapidly aging demographic and rising middle-class income underpin strong volume growth, while local manufacturers accelerate adoption of intraoral scanners and UV-cured resins to serve domestic clinics. Straumann Group recorded 82% year-on-year regional growth in early 2024, citing surging demand for scanners and implant-supported overdentures. Southeast Asian nations promote bundled tourism-plus-denture packages, leveraging lower labor costs to attract Western patients. Such cross-border traffic stimulates investment in advanced laboratory equipment, feeding back into regional dentures market expansion.
Europe sustains steady, technology-driven growth underpinned by mandatory health insurance and high practitioner skill levels. German and Spanish clinics led double-digit organic growth for Straumann's EMEA segment in 2024. The European Union's well-defined Medical Device Regulation fosters transparent approval pathways for new denture materials, encouraging faster market entry. Meanwhile, economic constraints in Southern and Eastern Europe extend case acceptance timelines, slowing overall regional CAGR relative to Asia-Pacific but preserving high digital-dentistry penetration.
The Middle East & Africa and South America collectively capture a smaller share today but exhibit expanding opportunities through urbanization and rising disposable income. Dental-school partnerships with Western universities are improving clinician capacity, laying groundwork for long-term dentures market development. Government-backed health-insurance pilots in the Gulf Cooperation Council are beginning to include fixed and removable prosthodontics, hinting at new reimbursable demand streams.
- Dentsply Sirona
- Zimmer Biomet
- Ivoclar Vivadent
- Modern Dental Group
- Coltene Holding
- Amann Girrbach
- VITA Zahnfabrik H. Rauter GmbH & Co. KG
- Shofu Inc.
- Kulzer
- GC Corporation
- Panthera Dental
- 3M Company (Dental Solutions)
- VOCO
- Mitsui Chemicals (Sun Medical)
- Aspen Dental
- Candulor AG
- Huge Dental Material Co. Ltd.
- Thommen Medical
- DIO
- Straumann Group
- Iverson Dental Laboratories
- Lazarus 3D
- SprintRay
- Formlabs Inc.
- Corus Dental
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Prevalence Of Oral Health Disorders
- 4.2.2 Rapid Growth Of Aging Population
- 4.2.3 Technological Advancements In Digital Denture Manufacturing
- 4.2.4 Rising Demand For Aesthetic Dental Solutions
- 4.2.5 Expansion Of Dental Insurance Coverage
- 4.2.6 Growing Dental Tourism In Emerging Economies
- 4.3 Market Restraints
- 4.3.1 High Treatment And Product Costs
- 4.3.2 Availability Of Alternative Tooth Replacement Options
- 4.3.3 Limited Skilled Workforce For Advanced Denture Technologies
- 4.3.4 Stringent Regulatory Approval Processes
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Buyers / Consumers
- 4.5.3 Bargaining Power Of Suppliers
- 4.5.4 Threat Of Substitute Products
- 4.5.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type
- 5.1.1 Complete Dentures
- 5.1.2 Partial Dentures
- 5.1.3 Other Types
- 5.2 By Usage
- 5.2.1 Fixed
- 5.2.2 Removable
- 5.3 By Material
- 5.3.1 Acrylic Resin
- 5.3.2 Porcelain
- 5.3.3 Metal-Ceramic
- 5.3.4 Flexible (Nylon-Based)
- 5.3.5 3-D Printed Photopolymer
- 5.4 By Manufacturing Technology
- 5.4.1 Conventional Molding
- 5.4.2 CAD/CAM Milled
- 5.4.3 3-D Printed Additive
- 5.5 By End User
- 5.5.1 Dental Clinics & Hospitals
- 5.5.2 Dental Laboratories
- 5.5.3 Academic & Research Institutes
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 DENTSPLY SIRONA Inc.
- 6.3.2 Zimmer Biomet Holdings Inc.
- 6.3.3 Ivoclar Vivadent AG
- 6.3.4 Modern Dental Group Ltd.
- 6.3.5 COLTENE Holding AG
- 6.3.6 Amann Girrbach AG
- 6.3.7 VITA Zahnfabrik H. Rauter GmbH & Co. KG
- 6.3.8 Shofu Inc.
- 6.3.9 Kulzer GmbH
- 6.3.10 GC Corporation
- 6.3.11 Panthera Dental
- 6.3.12 3M Company (Dental Solutions)
- 6.3.13 VOCO GmbH
- 6.3.14 Mitsui Chemicals (Sun Medical)
- 6.3.15 Aspen Dental
- 6.3.16 Candulor AG
- 6.3.17 Huge Dental Material Co. Ltd.
- 6.3.18 Thommen Medical AG
- 6.3.19 DIO Corporation
- 6.3.20 Straumann Group
- 6.3.21 Iverson Dental Laboratories
- 6.3.22 Lazarus 3D
- 6.3.23 SprintRay Inc.
- 6.3.24 Formlabs Inc.
- 6.3.25 Corus Dental
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

