PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116545

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116545
Autism Spectrum Disorders Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the autism spectrum disorders treatment market size is expected to grow from USD 2.34 billion in 2025 to USD 2.46 billion in 2026 and is forecast to reach USD 3.18 billion by 2031 at 5.22% CAGR over 2026-2031.
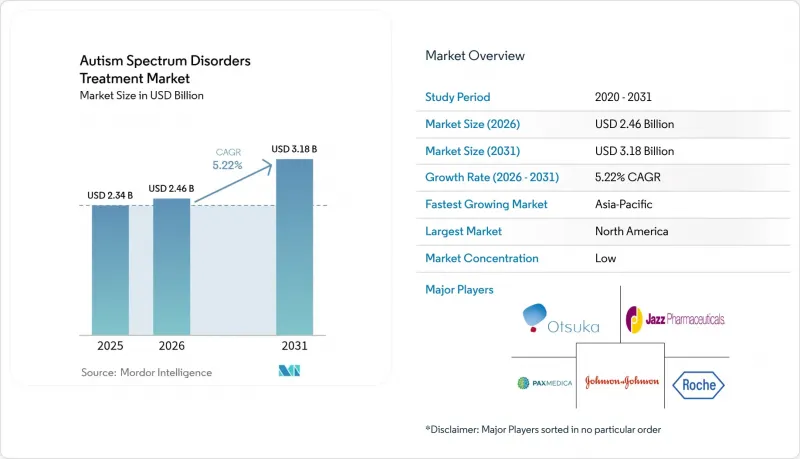
This report is Segmented by Drug Class (Antipsychotic Drugs, SSRIs/Antidepressants, Stimulants, Hormone Therapies and More), ASD Type (Autistic Disorder, Asperger's Syndrome, Rett Syndrome and More), Age Group (Pediatrics, Adolescents and More), Distribution Channel (Hospital Pharmacies, Retail and Drug Stores and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Autism Spectrum Disorders Treatment Market Trends and Insights
High Burden of Autism Spectrum Disorders (ASD)
Escalating prevalence-now 1 in 36 children-adds load to health systems that still rely on labor-intensive behavioral care, prompting families to seek pharmacologic relief when aggression threatens safety. Lifetime economic burden has been pegged at USD 7 trillion by 2029, reflecting medical costs plus lost productivity. Pharma pipelines still focus on pediatric needs, yet rising diagnoses among young adults are widening the untreated population, validating the adult segment's 8.92% CAGR outlook. Medication remains common; two-thirds of autistic adolescents receive psychotropics, underscoring unmet demand for safer, more targeted drugs.
Growing Awareness & Early Diagnosis Initiatives Coupled with Government Funding
The NIMH allocates USD 47 billion for neuroscience, and HRSA adds USD 5 million for autism programs, reinforcing national priorities.Multistage screening networks are improving detection among underserved groups, while FDA-designated tools like StrandDx ASD promise prediction at birth with 80-90% accuracy. Earlier identification lengthens treatment horizons, supporting recurring revenue models for therapy developers.
High Cost of Long-term Pharmacologic Management
Lifelong drug regimens accumulate costs that deter uptake, especially where payer budgets remain tight. Metabolic monitoring for antipsychotics adds testing fees and clinician visits, and adherence gaps drive relapse episodes that require expensive interventions. Polypharmacy exposes patients to additive side-effect risks; roughly 30% of individuals take two or more agents, adding complexity and financial load.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Reimbursement Coverage for ASD Therapies
- Robust Late-stage Pipeline of Novel Therapeutics
- Stringent Regulatory Hurdles & Limited Surrogate Endpoints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Antipsychotics retained 41.10% Autism Spectrum Disorder treatment market share in 2025, anchored by risperidone and aripiprazole approvals for irritability. Their growth is moderating due to metabolic risks, while cannabinoid therapeutics record an 8.38% CAGR as FDA acceptance of botanical dossiers widens. Antidepressants and SSRIs remain stable for anxiety comorbidity, and stimulants such as methylphenidate gain favor for overlapping ADHD. Hormone-based approaches advance via oxytocin and vasopressin analogs, and microbiome modulators show Phase 2 success. Evolving evidence prompts neurologists to shift anticonvulsant use toward lower teratogenic agents.
The Autism Spectrum Disorder treatment market size for cannabinoid drugs could climb markedly if AJA001 and HOPE-1 secure approval, though rigorous lot consistency testing remains a gatekeeper. Antipsychotic incumbents are deploying long-acting injectables to defend share, yet patient and caregiver sentiment is gravitating toward therapies that treat social deficits, setting the stage for category disruption over the forecast window.
Autistic Disorder stood at 53.20% of revenue in 2025, reflecting diagnostic prevalence. Rett Syndrome, a rare but well-defined genetic variant, is growing fastest at 7.88% CAGR, riding trofinetide's first-in-class approval. Market access teams are educating clinicians on syndrome-specific eligibility, shifting perceptions from broad-spectrum prescriptions to genotype-guided options.
The Autism Spectrum Disorder treatment market size attached to Rett Syndrome therapies will expand further as Canada's Priority Review and potential EU filings widen geographic reach. Success of DAYBUE also motivates investors to fund programs for Phelan McDermid and Fragile X, signaling momentum toward tailored molecules that can command premium pricing.
Complete Report Scope:
- By Drug Class
- Antipsychotic Drugs
- SSRIs / Antidepressants
- Stimulants
- Hormone Therapies
- Anticonvulsants
- Cannabinoid-based Therapies
- Microbiome Modulators
- Other Drug Classes
- By ASD Type
- Autistic Disorder
- Asperger Syndrome
- PDD-NOS
- Rett Syndrome
- Childhood Disintegrative Disorder
- Other Types
- By Age Group
- Pediatrics (2-12 yrs)
- Adolescents (13-17 yrs)
- Adults (18+ yrs)
- By Distribution Channel
- Hospital Pharmacies
- Retail & Drug Stores
- Specialty Pharmacies
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 45.70% of 2025 revenue as FDA approvals, broad insurance coverage and early digital tool adoption support therapy demand. The US leads clinical-trial volume, and Canada's fast-track processes for Rett Syndrome drugs indicate regulatory alignment. Mexico is climbing as diagnosis rates improve alongside private insurance penetration.
Europe exhibits stable expansion. EMA harmonization eases multi-country launches, and Germany's Digital Health Applications pathway reimburses software therapeutics. France and Italy sustain antipsychotic volume, while the UK funds community autism hubs that incorporate pharmacologic and behavioral care.
Asia-Pacific posts the strongest growth at 7.55% CAGR. Japan is updating its Pharmaceuticals and Medical Devices Act to smooth botanical approvals, and China's Hainan pilot zone permits conditional imports of unapproved drugs for urgent needs, accelerating cannabinoid access. India's expanding telemedicine footprint supports online pharmacy uptake, although reimbursement lags.
Middle East & Africa remains nascent but benefits from Gulf states' employment of universal health-coverage programs that include pediatric neurodevelopmental services. South America records steady gains, with Brazil's ANVISA fast-tracking certain cannabis formulations and Argentina increasing public funding for early screening.
- QIAGEN
- PaxMedica Inc.
- Yamo Pharmaceuticals LLC
- Otsuka
- Roche
- Curemark LLC
- Zynerba Pharmaceuticals Inc.
- Axial Therapeutics
- STALICLA SA
- Johnson & Johnson
- Jazz Pharma
- Eli Lilly and Company
- Pfizer
- NeuroNOS
- DeFloria, Inc.,
- Jaguar Gene Therapy
- Anavex Life Sciences Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High Burden of Austism Spectrum Disorders (ASD)
- 4.2.2 Growing Awareness & Early diagnosis initiatives Coupled with Government Funding
- 4.2.3 Expanding Reimbursement Coverage for ASD Therapies
- 4.2.4 Robust Late-stage Pipeline of Novel Therapeutics
- 4.2.5 Advancement in Diagnostic Tools and Digital Therapeutics
- 4.2.6 Private Sector Investment Collaboration and Funding for Rare ASD Sub-types
- 4.3 Market Restraints
- 4.3.1 High Cost of Long-term Pharmacologic Management
- 4.3.2 Stringent Regulatory Hurdles & Limited Surrogate Endpoints
- 4.3.3 Limited Efficacy & Adverse Effects of Existing Drugs
- 4.3.4 Data-privacy Limits on Pooled Genomic Datasets
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Drug Class
- 5.1.1 Antipsychotic Drugs
- 5.1.2 SSRIs / Antidepressants
- 5.1.3 Stimulants
- 5.1.4 Hormone Therapies
- 5.1.5 Anticonvulsants
- 5.1.6 Cannabinoid-based Therapies
- 5.1.7 Microbiome Modulators
- 5.1.8 Other Drug Classes
- 5.2 By ASD Type
- 5.2.1 Autistic Disorder
- 5.2.2 Asperger Syndrome
- 5.2.3 PDD-NOS
- 5.2.4 Rett Syndrome
- 5.2.5 Childhood Disintegrative Disorder
- 5.2.6 Other Types
- 5.3 By Age Group
- 5.3.1 Pediatrics (2-12 yrs)
- 5.3.2 Adolescents (13-17 yrs)
- 5.3.3 Adults (18+ yrs)
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail & Drug Stores
- 5.4.3 Specialty Pharmacies
- 5.4.4 Online Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Q BioMed Inc.
- 6.3.2 PaxMedica Inc.
- 6.3.3 Yamo Pharmaceuticals LLC
- 6.3.4 Otsuka Pharmaceutical Co., Ltd.
- 6.3.5 F. Hoffmann-La Roche Ltd.
- 6.3.6 Curemark LLC
- 6.3.7 Zynerba Pharmaceuticals Inc.
- 6.3.8 Axial Therapeutics
- 6.3.9 STALICLA SA
- 6.3.10 Johnson & Johnson (Janssen)
- 6.3.11 Jazz Pharma
- 6.3.12 Eli Lilly and Company
- 6.3.13 Pfizer Inc.
- 6.3.14 NeuroNOS
- 6.3.15 DeFloria, Inc.,
- 6.3.16 Jaguar Gene Therapy
- 6.3.17 Anavex Life Sciences Corp.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

