PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116555

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116555
Global PTA Balloon Catheter - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the PTA balloon catheter market size is expected to grow from USD 3.10 billion in 2025 to USD 3.35 billion in 2026 and is forecast to reach USD 4.96 billion by 2031 at 8.15% CAGR over 2026-2031.
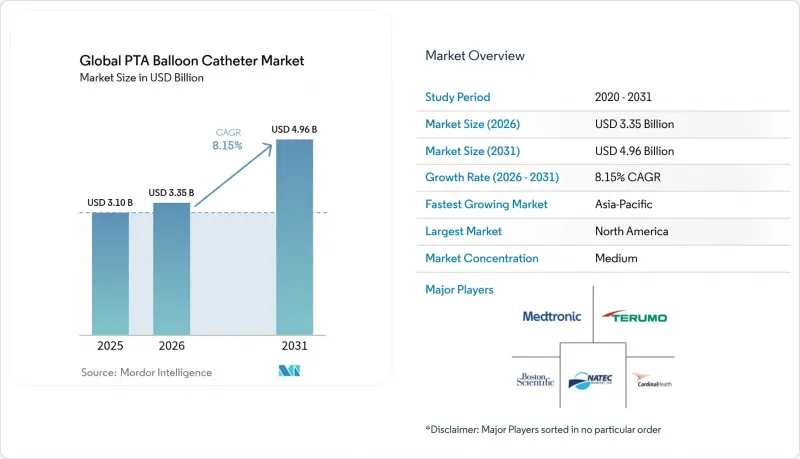
This report is Segmented by Material Type (Polyurethane, Nylon, and More), Coating Type (Plain Non-Coated, and More), Compliance Level (Compliant, Semi-Compliant, Non-Compliant), Application (Coronary Artery Disease, and More), End User (Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global PTA Balloon Catheter Market Trends and Insights
Rising Prevalence of Coronary & Peripheral Artery Diseases
Escalating cardiovascular disease has enlarged the addressable patient pool for angioplasty. Coronary artery disease affects more than 200 million people, and peripheral artery disease impacts roughly 230 million worldwide, with incidence tripling beyond age 65 . Balloon angioplasty is used in 85% of coronary revascularization procedures, and calcified lesions now comprise 40% of interventional cases-conditions that increasingly require specialized cutting or scoring balloons. Diabetes further fuels demand, as drug-coated balloons lower restenosis rates in diabetic vessels. This epidemiologic base anchors sustained utilization even during economic downturns.
Shift Toward Minimally-Invasive Endovascular Procedures
Endovascular therapy now represents 78% of all vascular interventions in developed markets, reflecting shorter recovery times and lower complication rates. Design advances such as ultra-low crossing profiles let physicians treat anatomies once deemed inoperable, while robotic catheter systems cut radiation exposure and improve precision. COVID-19 accelerated the pivot as hospitals prioritized quick, low-risk care. Five-year follow-up from the IN.PACT Global Study shows 69.4% freedom from target lesion revascularization with drug-coated balloons, reinforcing long-term durability.
High Cost of Drug-Coated Balloons & Reimbursement Gaps
Drug-coated balloons cost 3-4 times more than conventional options, at USD 800-1,200 per unit in many emerging markets. Uneven reimbursement forces physicians to navigate prior-authorization delays, curbing uptake. Producers face higher manufacturing expenses due to paclitaxel handling and quality controls, passing costs to providers. Value-based frameworks that credit lower reintervention rates are still nascent, limiting penetration despite clinical advantages.
Other drivers and restraints analyzed in the detailed report include:
- Growing Geriatric Population With Comorbidities
- Expedited Approvals & Coverage for Drug-Coated Balloons in Mid-Income Markets
- Procedural Complications (Restenosis, Dissection)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyurethane commanded 43.12% of PTA balloon catheter market share in 2025, reflecting mature production lines and proven biocompatibility. Pebax and other advanced polymers are expanding at 9.11% CAGR, owing to their kink resistance and multi-durometer flexibility, which improve trackability in tortuous vessels. Nylon remains favored for cost-sensitive applications, and PET supports high-pressure balloons designed for rigid lesions. Saint-Gobain's medical-grade Pebax blends enable balloons that flex without losing burst strength. Duke Extrusion's custom Pebax tubing and emerging PEEK substitutes that avoid PFAS demonstrate how sustainability considerations are steering material selection.
Clinical complexity underpins polymer substitution trends. Operators are tackling more calcified and below-the-knee lesions, requiring materials that combine pushability with low crossing profiles. The PTA balloon catheter market continues to reward suppliers that tailor polymer grades for precise compliance and inflation response, supporting higher technical success in difficult anatomy. As value analysis committees scrutinize product differentiation, proven procedural benefits help premium polymers secure formulary acceptance.
Plain non-coated balloons retained 57.66% revenue share in 2025, underlining their role as baseline therapy for lesion dilation. Drug-coated paclitaxel balloons, however, are growing at 8.97% CAGR, buoyed by randomized trials showing 11.1% fewer adverse events compared with uncoated devices following FDA approval of Boston Scientific's AGENT balloon in 2024. Specialty hydrophilic coatings serve small niches where low friction benefits outweigh added cost.
The PTA balloon catheter market benefits from maturing drug-transfer science. The AGENT platform's 2 µg/mm2 paclitaxel dose maintains efficacy while reducing systemic exposure. Large-scale registry data from Sweden confirm better outcomes for in-stent restenosis with drug-coated balloons versus plain angioplasty. As guidelines evolve, facilities factor reduced reintervention into total-cost-of-care models, supporting wider formulary adoption of therapeutic coatings.
Complete Report Scope:
- By Material Type
- Polyurethane
- Nylon
- PET
- Pebax & Other Advanced Polymers
- By Coating Type
- Plain (Non-coated)
- Drug-Coated - Paclitaxel
- Specialty Hydrophilic Coatings
- By Compliance Level
- Compliant
- Semi-Compliant
- Non-Compliant
- By Application
- Coronary Artery Disease
- Peripheral Vascular Disease
- Renal Artery Disease
- Neurovascular Disease
- AV Fistula Stenosis
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 44.92% revenue share in 2025, nourished by robust reimbursement, deep clinical expertise, and first-in-class approvals like the AGENT drug-coated coronary balloon in February 2024. ASC-based PCI sites doubled from 2019 to 2023 as payment rules favored outpatient care, generating fresh volume outside hospital walls . Canadian and Mexican markets add incremental gains via modernization of cath-lab infrastructure and broader insurance coverage.
Asia-Pacific is the fastest-growing region at 9.71% CAGR. China's NMPA granted marketing authorization to AGENT in 2024, signaling a friendlier stance toward novel cardiovascular devices. India's updated device code and increased public-private hospital spending uplift demand, while Japan's super-aged society drives high utilization of premium balloons. WHO reports cite stronger regulatory oversight across the Western Pacific, removing bottlenecks that once delayed launches. Rising middle-class income and private insurance adoption further enlarge the patient base.
Europe sustains substantial volume through established clinical research networks and harmonized procurement processes. Evidence such as the IN.PACT Global Study underpins payer acceptance of drug-coated balloons. The Medical Device Regulation framework safeguards quality without stifling innovation. Green-procurement policies promote reprocessing programs, influencing disposable-versus-reusable calculus and potentially lowering life-cycle costs. Eastern European countries, meanwhile, lean on EU cohesion funds to upgrade cath-lab equipment, adding pockets of high growth within a mature overall landscape.
- Medtronic
- Boston Scientific
- Abbott Laboratories
- Terumo
- Cook Group
- Cardinal Health
- BIOTRONIK
- B. Braun
- Koninklijke Philips
- Natec Medical
- AndraTec
- Cardionovum
- Asahi Intecc
- Merit Medical Systems
- MicroPort
- Lepu Medical
- MedAlliance
- Surmodics
- Sinomed
- BD (Becton, Dickinson & Co.)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence Of Coronary & Peripheral Artery Diseases
- 4.2.2 Shift Toward Minimally-Invasive Endovascular Procedures
- 4.2.3 Growing Geriatric Population With Comorbidities
- 4.2.4 Expedited Approvals & Coverage For Drug-Coated Balloons In Mid-Income Markets
- 4.2.5 Outpatient Payment Reforms Favoring Day-Case Angioplasty
- 4.2.6 Ai-Based Vessel Sizing Boosting Pta Balloon Utilization
- 4.3 Market Restraints
- 4.3.1 High Cost Of Drug-Coated Balloons & Reimbursement Gaps
- 4.3.2 Procedural Complications (Restenosis, Dissection)
- 4.3.3 Environmental Restrictions On Paclitaxel Supply Chain
- 4.3.4 Rise Of Alternative Therapies (Atherectomy, Lithotripsy)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Material Type
- 5.1.1 Polyurethane
- 5.1.2 Nylon
- 5.1.3 PET
- 5.1.4 Pebax & Other Advanced Polymers
- 5.2 By Coating Type
- 5.2.1 Plain (Non-coated)
- 5.2.2 Drug-Coated - Paclitaxel
- 5.2.3 Specialty Hydrophilic Coatings
- 5.3 By Compliance Level
- 5.3.1 Compliant
- 5.3.2 Semi-Compliant
- 5.3.3 Non-Compliant
- 5.4 By Application
- 5.4.1 Coronary Artery Disease
- 5.4.2 Peripheral Vascular Disease
- 5.4.3 Renal Artery Disease
- 5.4.4 Neurovascular Disease
- 5.4.5 AV Fistula Stenosis
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgical Centers
- 5.5.3 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Medtronic plc
- 6.3.2 Boston Scientific Corporation
- 6.3.3 Abbott Laboratories
- 6.3.4 Terumo Corporation
- 6.3.5 Cook Medical
- 6.3.6 Cardinal Health
- 6.3.7 BIOTRONIK
- 6.3.8 B. Braun Melsungen AG
- 6.3.9 Koninklijke Philips N.V.
- 6.3.10 Natec Medical
- 6.3.11 AndraTec
- 6.3.12 Cardionovum GmbH
- 6.3.13 Asahi Intecc
- 6.3.14 Merit Medical Systems
- 6.3.15 MicroPort Scientific
- 6.3.16 Lepu Medical
- 6.3.17 MedAlliance
- 6.3.18 Surmodics
- 6.3.19 Sinomed
- 6.3.20 BD (Becton, Dickinson & Co.)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

