PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116564

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116564
Suture Anchor Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the global suture anchor devices market size was valued at USD 860 million in 2025 and estimated to grow from USD 906.1 million in 2026 to reach USD 1,176.74 million by 2031, at a CAGR of 5.36% during the forecast period (2026-2031).
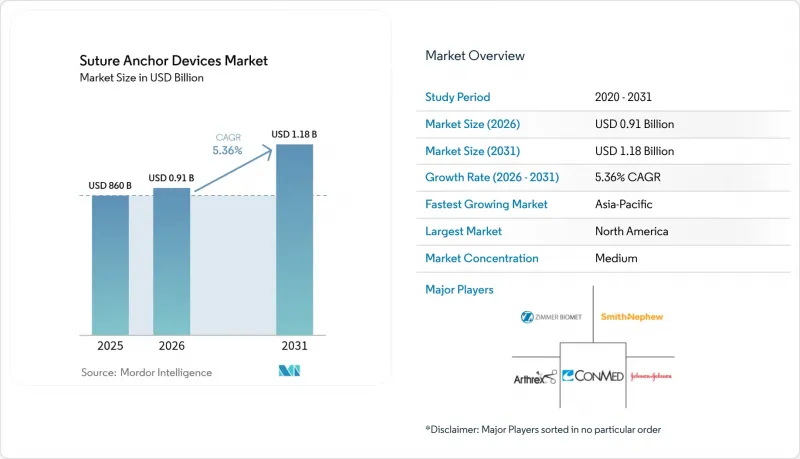
This report is Segmented by Product Types (Absorbable and Non-Absorbable), Material Type (Metal, Bio-Absorbable Polymer, and More), Fixation Mechanism (Knotted, Knotless, and Tape-Based), Application (Shoulder-Rotator Cuff, Hip-labral & FAIS, and More), End-User (Hospitals, and More) and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Suture Anchor Devices Market Trends and Insights
Aging-Related Orthopedic Injuries Surge
An expanding cohort of adults over 65 now drives roughly half of the 18.5 million orthopedic procedures performed annually in the United States. Higher life expectancy and active lifestyles mean more patients present with rotator-cuff tears, osteoarthritis, and hip fractures, all of which routinely require anchor fixation. Germany anticipates knee arthroplasty incidence to climb 55% by 2040, illustrating demographic pull across Europe. In parallel, U.S. outpatient reimbursement uplifts make anchor-based repairs viable in non-acute settings, reinforcing volume growth. These intersecting trends underpin durable demand for the suture anchor devices market.
Growing Demand For Minimally-Invasive Arthroscopy
Nano-arthroscopy has reduced portal size to 2 mm, enabling procedures under local anesthesia that bypass full-scale operating rooms. Arthrex's NanoScope platform exemplifies this shift with single-use 1 mm imaging sensors that also serve as MRI alternatives. Clinical data show needle arthroscopy produces lower post-op pain scores compared with standard techniques, while ASCs can perform such cases at 26% lower cost than hospital outpatient departments. As minimally invasive preferences deepen, procedure counts-and by extension the suture anchor devices market-are set to rise.
Adverse Tissue Reactions To Certain Absorbable Polymers
Polyglycolic acid anchors evoke granulomatous inflammation requiring surgical drainage in 6.3% of cases, with hospital stays averaging 18 days. Osteolytic tunnels can appear 12 weeks post-op, compromising fixation integrity. Carbon-fiber PEEK plates also shed particles that elevate local cytokine response. These biocompatibility hurdles temper near-term uptake of newer materials in the suture anchor devices market.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Incidence Of Sports & Recreation Accidents
- Shift Toward Bio-Absorbable Anchors To Reduce MRI Artifacts
- Premium Pricing Versus Conventional Fixation Methods
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Absorbable anchors represent the innovation vanguard. In 2025 non-absorbables retained the largest block at 53.02% revenue, yet absorbables are projected to outpace with an 8.13% CAGR. This divergence directly increases the suture anchor devices market size captured by degradable formats as hospitals shift to MRI-friendly post-op protocols. Smith & Nephew's REGENESORB platform, which converts to bone within two years, embodies the clinical argument for resorption. Surgeons remain cautious because 4.3% of bio-polymer cases show adverse reactions, but ongoing polymer science is trimming complication rates. Government standards like ASTM F2579-18 certify performance criteria, easing tender participation and reinforcing confidence in the suture anchor devices market.
The non-absorbable category still commands surgeon loyalty where high-load bearing and long-term certainty are paramount. Metallic anchors excel in revision scenarios, while expanded PEEK lines deliver bone-like modulus to mitigate stress shielding. As competitive suppliers blend absorbable tips with non-absorbable cores, hybrid designs will blur categorical lines, sustaining wide choice within the suture anchor devices market.
PEEK and carbon-reinforced PEEK formed 35.12% of overall revenue in 2025, giving this high-performance polymer the single-largest material footprint in the suture anchor devices market share. Machinability and CT-compatibility make PEEK a default in complex shoulder and hip work. Evonik's VESTAKEEP i4 3DF now enables ASTM F2026-compliant 3-D printed implants, unlocking surgeon-specific geometries. Yet bio-polymers such as PLLA and PLGA are accelerating at 8.03% CAGR, underpinned by degradability and osteoconductive fillers.
Titanium and stainless steel retain niches in trauma and hard-bone fixation where permanent strength overrides imaging concerns. Coralline graft composites and biphasic calcium phosphate-doped PEEK offer middle-ground solutions that encourage bone in-growth. Over the forecast period, material diversity is likely to intensify as suppliers hedge against PEEK supply concentration, cushioning the suture anchor devices market against raw-material shocks.
Complete Report Scope:
- By Product Type
- Absorbable
- Non-Absorbable
- By Material
- Metal (Titanium / Stainless)
- Bio-absorbable Polymer (PLLA, PLGA)
- PEEK & Carbon-reinforced PEEK
- Hybrid / Bio-composite
- By Fixation Mechanism
- Knotted
- Knotless
- Tape-based
- By Application
- Shoulder-Rotator Cuff
- Hip-Labral & FAIS
- Knee-Meniscal & MCL
- Foot & Ankle
- Elbow & Wrist
- By End-user
- Hospitals
- Ambulatory Surgical Centers (ASCs)
- Specialty Orthopedic Clinics
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 40.33% of 2025 revenue and remains the technology bellwether for the suture anchor devices market. Medicare's 36.2% rise in outpatient shoulder arthroplasty reimbursement, together with a 2.9% facility-wide uplift, reinforces hospital and ASC economics. Canadian universal coverage ensures consistent baseline volumes, while Mexican medical-tourism corridors broaden the regional patient pool.
Europe contributes stable but slower growth as national health systems impose strict cost containment. Medical Device Regulation (EU) 2017/745 compels recertification of legacy anchors, adding compliance costs yet heightening product quality. Germany's knee and hip replacement projections underpin procedure demand, whereas microplastics rules effective October 2029 will steer material choices toward eco-compliant polymers.
Asia-Pacific is on a 9.14% CAGR trajectory, outpacing all regions. Japan showcases early adoption of robotic arthroplasty and absorbable anchors to manage an aging demographic. India and ASEAN nations prioritize capacity investments; reference-market inclusion changes in Australia simplify device approvals, speeding cross-border introduction. Manufacturers with regional assembly or price-band portfolios will capture outsized upside in this high-growth theater of the suture anchor devices market.
- Smiths Group
- Johnson & Johnson
- Arthrex
- Stryker
- Zimmer Biomet
- Conmed
- Medtronic
- Parcus Medical LLC
- Wright Medical Group
- Teknimed
- Enovis (DJO)
- Integra LifeSciences
- Double Medical
- Anika Therapeutics
- Medartis
- Orthomed SAS
- B. Braun
- OrthAlign Inc.
- Ceterix Orthopaedics
- Teleflex Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging-Related Orthopedic Injuries Surge
- 4.2.2 Growing Demand For Minimally-Invasive Arthroscopy
- 4.2.3 Increasing Incidence Of Sports & Recreation Accidents
- 4.2.4 Shift Toward Bio-Absorbable Anchors To Reduce MRI Artifacts
- 4.2.5 Advancements In Knotless, Tape-Based Anchor Platforms
- 4.2.6 US ASC Reimbursement Changes Favoring Anchor-Based Repairs
- 4.3 Market Restraints
- 4.3.1 Adverse Tissue Reactions To Certain Absorbable Polymers
- 4.3.2 Premium Pricing Versus Conventional Fixation Methods
- 4.3.3 Emerging Micro-Plastics Regulations Targeting Degrading Polymers
- 4.3.4 PEEK Supply-Chain Concentration Elevating Raw-Material Risk
- 4.4 Porter's Five Forces
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Absorbable
- 5.1.2 Non-Absorbable
- 5.2 By Material
- 5.2.1 Metal (Titanium / Stainless)
- 5.2.2 Bio-absorbable Polymer (PLLA, PLGA)
- 5.2.3 PEEK & Carbon-reinforced PEEK
- 5.2.4 Hybrid / Bio-composite
- 5.3 By Fixation Mechanism
- 5.3.1 Knotted
- 5.3.2 Knotless
- 5.3.3 Tape-based
- 5.4 By Application
- 5.4.1 Shoulder-Rotator Cuff
- 5.4.2 Hip-Labral & FAIS
- 5.4.3 Knee-Meniscal & MCL
- 5.4.4 Foot & Ankle
- 5.4.5 Elbow & Wrist
- 5.5 By End-user
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgical Centers (ASCs)
- 5.5.3 Specialty Orthopedic Clinics
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Smith & Nephew plc
- 6.3.2 Johnson & Johnson (DePuy Synthes)
- 6.3.3 Arthrex Inc.
- 6.3.4 Stryker Corporation
- 6.3.5 Zimmer Biomet Holdings
- 6.3.6 ConMed Corporation
- 6.3.7 Medtronic plc
- 6.3.8 Parcus Medical LLC
- 6.3.9 Wright Medical Group
- 6.3.10 Teknimed
- 6.3.11 Enovis (DJO)
- 6.3.12 Integra LifeSciences
- 6.3.13 Double Medical
- 6.3.14 Anika Therapeutics
- 6.3.15 Medartis AG
- 6.3.16 Orthomed SAS
- 6.3.17 B. Braun Melsungen AG
- 6.3.18 OrthAlign Inc.
- 6.3.19 Ceterix Orthopaedics
- 6.3.20 Teleflex Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

