PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116646

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116646
Healthcare Distribution - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the healthcare distribution market size was valued at USD 1.11 billion in 2025 and estimated to grow from USD 1.18 billion in 2026 to reach USD 1.61 billion by 2031, at a CAGR of 6.37% during the forecast period (2026-2031).
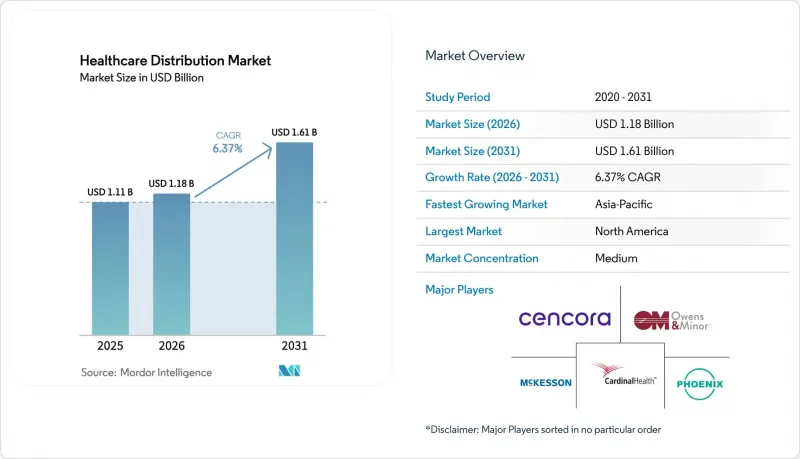
This report is Segmented by Product Type (Pharmaceutical Product Distribution Services, and More), Service Type (Warehousing & Storage, and More), End-User (Retail Pharmacies, and More), Distribution Channel (Traditional Full-Line Wholesalers, and More), Delivery Mode (Non-Cold Chain, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Healthcare Distribution Market Trends and Insights
Rising Global Pharmaceutical Expenditure
Global drug spending reached USD 1.48 trillion in 2024, and every incremental USD 1 in medicine outlays generates roughly USD 0.15 in distribution revenue. Specialty products now form 54% of spend despite just 2% of volumes, tilting the healthcare distribution market toward high-value, low-volume shipments. Distributors that operate GDP-certified cold-chain facilities capture premium handling fees, especially in oncology and rare diseases where a single treatment course can exceed USD 100,000 per patient. Value-based care models intensify demand for supply-chain analytics and inventory optimization that reduce waste and improve adherence. Competition for manufacturer contracts has therefore sharpened, prioritizing partners that bundle patient-support programs with proven logistics performance.
Expansion of Biologics and Specialty Therapies
Biologics exceeded USD 451 billion in sales during 2024 and require storage temperatures as low as -80 °C, which can triple handling costs versus conventional drugs. Cell and gene therapies heighten complexity, as a single personalized shipment may hold USD 2-3 million in product value and must arrive within tightly defined time windows. Market leaders are investing accordingly: DHL has earmarked EUR 2 billion through 2030 for new pharma hubs, validated cold rooms, and digital monitoring solutions. Smaller distributors frequently exit this segment because capex for ultra-cold infrastructure and compliance far exceeds their balance-sheet capacity, catalyzing further consolidation within the healthcare distribution market.
Margin Compression from Price Transparency Initiatives
Federal and state rules that demand disclosure of net drug prices are eroding traditional rebate economics, trimming distributor spreads and spurring a pivot toward fee-for-service contracts. The top three PBMs command about 80% of U.S. prescription claims, using that scale to negotiate lower distribution fees. Many states now set upper payment limits, which further squeeze margins. Consequently, distributors in the healthcare distribution market are investing in automation and analytics to cut operating costs and to offer value-added services that justify explicit handling fees.
Other drivers and restraints analyzed in the detailed report include:
- Growth of E-Commerce and Mail-Order Pharmacies
- Regulatory Emphasis on Supply-Chain Security
- Healthcare Provider Consolidation Driving Bulk Purchasing
- Supply-Chain Disruptions and Geopolitical Instability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pharmaceutical product distribution services captured 67.02% revenue in 2025, reflecting large-volume demand for traditional small-molecule medicines. However, biopharmaceutical activities, notably monoclonal antibodies and cell therapies, are expanding at an 8.21% CAGR. Recombinant proteins lead the pace, propelled by autoimmune and oncology indications that require stringent temperature control and serialized packaging. Vaccines remain a steady baseline after COVID-19 created permanent cold-chain infrastructure. Integrated therapeutics such as insulin pumps now blur drug and device categories, offering distributors cross-portfolio bundling opportunities. The healthcare distribution market size for biologics is anticipated to exceed USD 706 million by 2031, representing more than 43.00% of total value. Distributors that finance ultra-cold vaults, execute reverse-logistics protocols for returns, and deploy IoT trackers gain preferred-partner status among manufacturers. As biosimilars rise, volumes grow while temperature requirements stay rigid, reinforcing demand for premium logistics services across the healthcare distribution market.
Second-generation gene therapies intensify complexity, because many products ship patient-specific payloads that must arrive within 24-48 hours. Service-level guarantees now tie payment milestones to clinical outcomes, obliging distributors to embed real-time monitoring and contingency routing. Advanced analytics predict lane-level bottlenecks, reducing spoilage and enabling risk-based inventory allocations. With these capabilities, large third-party logistics providers are displacing regional couriers in high-value lanes, further concentrating share among global players in the healthcare distribution market.
Warehousing & storage held 46.05% share in 2025, underscoring the continuing weight of inventory management in the healthcare distribution market. Yet Cold-Chain Logistics is expanding at 8.41% CAGR, the fastest among service categories. End-to-end temperature management spans validated packaging, GPS-enabled data loggers, and GDP-certified cross-docks. Growth is magnified by biosimilars, mRNA vaccines, and emerging cell-therapy launches. Automation within ambient warehouses keeps occupancy costs down, allowing margin reinvestment into cold rooms and liquid nitrogen storage. Transportation & Freight networks have adopted active containers and software that reroutes shipments in flight when excursion risk rises. Reverse Logistics now handles both environmental stewardship and product-integrity mandates, bolstered by legislation on proper disposal of expired drugs.
The healthcare distribution industry increasingly sells bundled contracts that combine warehousing, pick-and-pack, and last-mile freight under one performance SLA, shifting procurement from transactional tariffs to multi-year service agreements. Distributors that exhibit sub-1% temperature excursions win long-term partnerships, creating high switching barriers. Consequently, regional firms collaborate via alliances to offer network scale without heavy capex, but their combined reach still lags the largest operators in the healthcare distribution market.
Complete Report Scope:
- By Product Type
- Pharmaceutical Product Distribution Services
- OTC Drugs
- Generic Drugs
- Branded Drugs
- Biopharmaceutical Product Distribution Services
- Recombinant Proteins
- Monoclonal Antibodies
- Vaccines
- Medical Devices Distribution Services
- Pharmaceutical Product Distribution Services
- By Service Type
- Warehousing & Storage
- Transportation & Freight (Non-cold chain)
- Cold-Chain Logistics
- Reverse Logistics & Returns
- By End-User
- Retail Pharmacies
- Hospital Pharmacies
- Other End-Users
- By Distribution Channel
- Traditional Full-line Wholesalers
- Specialty Distributors
- Mail-Order / Online Pharmacies
- Direct-to-Hospital (Manufacturer to Provider)
- By Delivery Mode
- Non-Cold Chain
- Cold Chain
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 43.21% revenue in 2025, anchored by the United States, where prescription spend surpassed USD 500 billion and DSCSA compliance has created a barrier for smaller firms. Canada's single-payer formulary adds complexity, requiring contract diligence and bilingual labeling, while Mexico's growing contract-manufacturing base strengthens north-south freight corridors. Health-system consolidation generates large integrated delivery networks that favor distributors with national coverage, advanced analytics, and proven cold-chain capacity. The healthcare distribution market size in North America is on track to climb to USD 705 million by 2031, even as pricing transparency squeezes average margins.
Asia-Pacific is the fastest-growing region at 7.32% CAGR. China's aging population and expanded insurance coverage unlock scale, though intricate provincial licensing demands local alliances. India's dominance in generics triggers volume-driven logistics models emphasizing cost control, while Japan's mature biologics pipeline necessitates rigid temperature assurance. Southeast Asia is capitalizing on free-trade accords that promote regional hubs in Singapore and Malaysia, where distributors invest in dual-certified cold rooms to serve both public tenders and private hospitals. The healthcare distribution market is therefore bifurcating between high-growth emerging economies that value reach and affordability, and mature economies that prioritize specialty capability and regulatory depth. Europe maintains steady expansion supported by the Falsified Medicines Directive, which mandates unique identifiers and safety seals across 27 member states, thereby harmonizing compliance requirements. Unified labeling curbs counterfeit risks and aligns distributor IT investments. In Western Europe, national health services drive tenders that reward lowest-total-cost providers, encouraging distributors to blend consolidated transport with data-rich adherence programs. Central and Eastern Europe see rising biologics import volumes, spurring investment in GDP-validated facilities. The Middle East & Africa region is accelerating infrastructure upgrades funded by sovereign initiatives, especially in Gulf Cooperation Council countries that import high volumes of specialty therapies. South America benefits from Mercosur tariff structures, though currency volatility complicates contract pricing. Collectively, these regions contribute diversified growth vectors that will push the healthcare distribution market past USD 1.61 billion by 2031.
- Mckesson
- Cardinal Health
- Cencora (AmerisourceBergen)
- Owens & Minor
- PHOENIX Group
- Shanghai Pharmaceuticals Holding
- Medline Industries
- DHL Supply Chain & GF (Life Sciences)
- UPS Healthcare
- FedEx HealthCare Solutions
- Zuellig Pharma
- Patterson Companies
- Morris & Dickson
- Smith Drug Company
- CuraScript SD
- Mutual Drug
- Alfresa Holdings
- Walgreens Boots Alliance (Wholesale Division)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Pharmaceutical Expenditure
- 4.2.2 Expansion of Biologics and Specialty Therapies
- 4.2.3 Aging Population and Increased Medication Demand
- 4.2.4 Growth of E-Commerce and Mail-Order Pharmacies
- 4.2.5 Regulatory Emphasis on Supply Chain Security
- 4.2.6 Healthcare Provider Consolidation Driving Bulk Purchasing
- 4.3 Market Restraints
- 4.3.1 Margin Compression From Price Transparency Initiatives
- 4.3.2 Supply Chain Disruptions and Geopolitical Instability
- 4.3.3 Stringent Temperature-Controlled Logistics Requirements
- 4.3.4 Workforce Shortages in Transportation and Warehousing
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Anlaysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Pharmaceutical Product Distribution Services
- 5.1.1.1 OTC Drugs
- 5.1.1.2 Generic Drugs
- 5.1.1.3 Branded Drugs
- 5.1.2 Biopharmaceutical Product Distribution Services
- 5.1.2.1 Recombinant Proteins
- 5.1.2.2 Monoclonal Antibodies
- 5.1.2.3 Vaccines
- 5.1.3 Medical Devices Distribution Services
- 5.1.1 Pharmaceutical Product Distribution Services
- 5.2 By Service Type
- 5.2.1 Warehousing & Storage
- 5.2.2 Transportation & Freight (Non-cold chain)
- 5.2.3 Cold-Chain Logistics
- 5.2.4 Reverse Logistics & Returns
- 5.3 By End-User
- 5.3.1 Retail Pharmacies
- 5.3.2 Hospital Pharmacies
- 5.3.3 Other End-Users
- 5.4 By Distribution Channel
- 5.4.1 Traditional Full-line Wholesalers
- 5.4.2 Specialty Distributors
- 5.4.3 Mail-Order / Online Pharmacies
- 5.4.4 Direct-to-Hospital (Manufacturer to Provider)
- 5.5 By Delivery Mode
- 5.5.1 Non-Cold Chain
- 5.5.2 Cold Chain
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 McKesson Corporation
- 6.3.2 Cardinal Health
- 6.3.3 Cencora (AmerisourceBergen)
- 6.3.4 Owens & Minor
- 6.3.5 PHOENIX Group
- 6.3.6 Shanghai Pharmaceuticals Holding
- 6.3.7 Medline Industries
- 6.3.8 DHL Supply Chain & GF (Life Sciences)
- 6.3.9 UPS Healthcare
- 6.3.10 FedEx HealthCare Solutions
- 6.3.11 Zuellig Pharma
- 6.3.12 Patterson Companies
- 6.3.13 Morris & Dickson
- 6.3.14 Smith Drug Company
- 6.3.15 CuraScript SD
- 6.3.16 Mutual Drug
- 6.3.17 Alfresa Holdings
- 6.3.18 Walgreens Boots Alliance (Wholesale Division)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

