PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116767

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116767
Dyspnea Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the dyspnea treatment market size was valued at USD 7.02 billion in 2025 and estimated to grow from USD 7.46 billion in 2026 to reach USD 10.14 billion by 2031, at a CAGR of 6.32% during the forecast period (2026-2031).
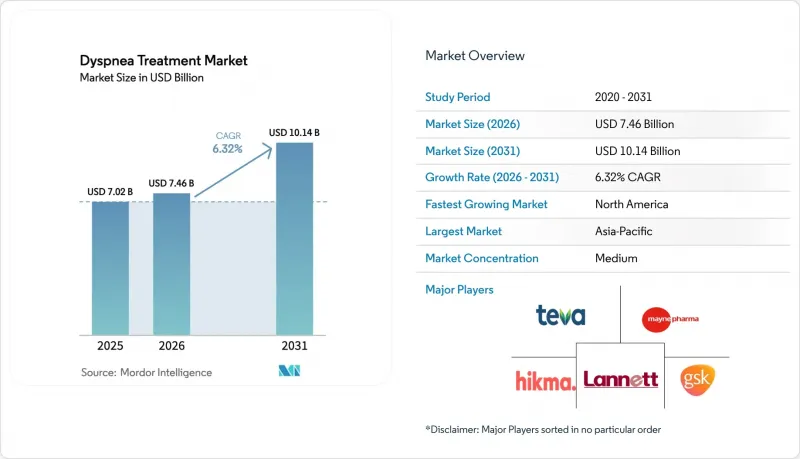
This report is Segmented by Treatment Type (Therapy [Supplemental Oxygen Therapy, Relaxation/Fan Therapy], Drug Class [Antianxiety Agents, Antibiotics, Anticholinergic Agents, and More]), Route of Administration (Oral, Inhalation, Others), End User (Hospitals, Home Care Settings, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Dyspnea Treatment Market Trends and Insights
Accelerating Prevalence of COPD and Post-COVID Breathlessness
Post-COVID-19 cough persists in 48.1% of patients with dyspnea, generating a sizeable new cohort that now enters clinical pathways for chronic breathlessness management. Virtual pulmonary rehabilitation programs demonstrate 99% safe engagement among COPD patients who need supplemental oxygen, proving the viability of tech-enabled interventions. Asia-Pacific markets face an alarming rise in COPD among adults aged 15-49 linked to particulate pollution, underscoring future demand for cost-effective dyspnea therapies. Economic modelling estimates COPD-linked direct and indirect costs could total USD 4.326 trillion from 2020-2050, reinforcing investment urgency.
Rapid Uptake of Home Oxygen Concentrators in Middle-Income Countries
Portable and solar-powered concentrators are proliferating where piped oxygen and cylinder logistics remain weak. Solar systems deliver oxygen at an incremental USD 20 per disability-adjusted life-year saved, a highly cost-effective ratio for resource-constrained hospitals. The OXFO valve conserved 92.3% oxygen without compromising saturation levels in clinical testing, directly lowering operating costs. Comprehensive oxygen ecosystem programs in Kenya, Rwanda, and Ethiopia boosted procurement volumes by up to 220% at USD 7.34 per patient treated, validating scalable supply-hub models. Patient-controlled flow devices such as FlexO2 raised self-management scores from 14 to 92 points, highlighting empowerment benefits.
High Capital Cost of High-Flow Oxygen Systems in LMIC Hospitals
The substantial capital requirements for advanced oxygen delivery infrastructure create significant barriers to market penetration in resource-constrained healthcare systems. Sophisticated high-flow units cost more than USD 50,000 each, exceeding budgets in low-resource facilities. Pulse-oximetry rollouts also struggle with procurement, training, and maintenance costs, limiting guideline uptake. Although solar concentrators show favourable cost-effectiveness, initial financing remains a hurdle. Alternative approaches like the low-cost SpO2 integrated neonatal CPAP device, costing under USD 200, show promise but require extensive validation and regulatory approval processes that further delay implementation.
Other drivers and restraints analyzed in the detailed report include:
- Pipeline Arrival of Once-Daily Triple-Combo Inhalers
- AI-Enabled Early-Warning Wearables Reducing ER Dyspnea Admissions
- Drug-Device Regulatory Mismatches Delaying Combo Launches
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Supplemental oxygen therapy represented 68.74% of 2025 revenue, reflecting entrenched clinical protocols and dependable reimbursement. Evidence from large COPD cohorts confirms sustained demand, particularly for ambulatory and nocturnal hypoxemia management. Yet relaxation and fan therapy is expanding at a 5.98% CAGR as randomized studies validate symptom relief and as value-based care incentivizes non-pharmacological tools. The dyspnea treatment market size for relaxation and fan modalities is on course to widen steadily, aided by cost-conservation devices such as OXFO that save 92.3% oxygen while maintaining target saturation levels.
Drug classes pivot toward precision medicine and environmental sustainability. Long-standing corticosteroid and anticholinergic categories retain broad utility, but biologics like depemokimab offer twice-yearly dosing and possible disease modification. Handheld fan trials reveal meaningful Visual Analogue Scale improvements, accelerating institutional acceptance. These dynamics suggest the dyspnea treatment market will witness gradual erosion of oxygen therapy's share as low-cost, evidence-backed alternatives scale globally.
Complete Report Scope:
- By Treatment Type
- Therapy
- Supplemental Oxygen Therapy
- Relaxation / Fan Therapy
- Drug Class
- Antianxiety Agents
- Antibiotics
- Anticholinergic Agents
- Corticosteroids
- Others
- Therapy
- By Route of Administration
- Oral
- Inhalation
- Others
- By End User
- Hospitals
- Home Care Settings
- Specialty and Pulmonary Rehab Centers
- Ambulatory Surgical Centers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 37.66% of 2025 revenue on the back of robust insurance coverage, established rehabilitation networks, and rapid regulatory clearance for novel therapeutics. CPT 94625 and 94626 improved pulmonary rehabilitation payment parity, fueling virtual program adoption. OHTUVAYRE's FDA approval confirms the region's innovation leadership. Pharmaceutical copay caps, such as Boehringer Ingelheim's USD 35 ceiling, address affordability gaps that could otherwise constrain uptake.
Asia-Pacific is the fastest growing with an 7.78% CAGR. COPD underdiagnosis in Japan, where only 8.4% of airflow-obstructed individuals receive a formal diagnosis, highlights latent demand. Solar-powered concentrators and PSA plants deliver oxygen at favourable DALY-based cost ratios suitable for emerging economies. Workforce initiatives in China that pair academic respiratory therapy programs with tertiary hospitals aim to meet escalating service needs.
Europe maintains steady progress owing to universal health systems and strict evidence thresholds. The European Respiratory Society's guidelines expedite uniform adoption of validated interventions. Environmental regulations advance propellant reforms, positioning the region as a catalyst for low-GWP inhaler transitions. Latin America, Africa, and the Middle East remain smaller but strategic, leveraging innovations such as solar concentrators and regional oxygen hubs to bypass legacy infrastructure barriers.
- GlaxoSmithKline
- AstraZeneca
- Novartis
- Teva Pharmaceutical Industries
- Boehringer Ingelheim
- Pfizer
- Viatris
- Sun Pharmaceuticals Industries
- Hikma Pharmaceuticals
- Lupin
- Amneal Pharmaceuticals
- Lannett Company Inc.
- Mayne Pharma
- Bausch Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Prevalence of COPD and Post-COVID Breathlessness
- 4.2.2 Rapid Uptake of Home Oxygen Concentrators in Middle-Income Countries
- 4.2.3 Pipeline Arrival of Once-Daily Triple-Combo Inhalers
- 4.2.4 AI-Enabled Early-Warning Wearables Reducing ER Dyspnea Admissions
- 4.2.5 Reimbursement Expansion for Remote Pulmonary Rehab
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of High-Flow Oxygen Systems in LMIC Hospitals
- 4.3.2 Drug-Device Regulatory Mismatches Delaying Combo Launches
- 4.3.3 Low Clinician Adoption of Non-Pharma Dyspnea Scoring Tools
- 4.3.4 Patent Expiration Pressures on Established Therapies
- 4.4 Regulatory Landscape
- 4.5 Pipeline Analysis
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Treatment Type
- 5.1.1 Therapy
- 5.1.1.1 Supplemental Oxygen Therapy
- 5.1.1.2 Relaxation / Fan Therapy
- 5.1.2 Drug Class
- 5.1.2.1 Antianxiety Agents
- 5.1.2.2 Antibiotics
- 5.1.2.3 Anticholinergic Agents
- 5.1.2.4 Corticosteroids
- 5.1.2.5 Others
- 5.1.1 Therapy
- 5.2 By Route of Administration
- 5.2.1 Oral
- 5.2.2 Inhalation
- 5.2.3 Others
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Home Care Settings
- 5.3.3 Specialty and Pulmonary Rehab Centers
- 5.3.4 Ambulatory Surgical Centers
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 GlaxoSmithKline plc
- 6.3.2 AstraZeneca plc
- 6.3.3 Novartis AG
- 6.3.4 Teva Pharmaceutical Industries Ltd.
- 6.3.5 Boehringer Ingelheim International GmbH
- 6.3.6 Pfizer Inc.
- 6.3.7 Viatris Inc. (Mylan N.V.)
- 6.3.8 Sun Pharmaceutical Industries Ltd.
- 6.3.9 Hikma Pharmaceuticals plc
- 6.3.10 Lupin Limited
- 6.3.11 Amneal Pharmaceuticals LLC
- 6.3.12 Lannett Company Inc.
- 6.3.13 Mayne Pharma Group Limited
- 6.3.14 Bausch Health Companies Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

