PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116786

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116786
Automotive Imaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive imaging market size is expected to grow from USD 5.7 billion in 2025 to USD 6.15 billion in 2026 and is forecast to reach USD 9.01 billion by 2031 at 7.94% CAGR over 2026-2031.
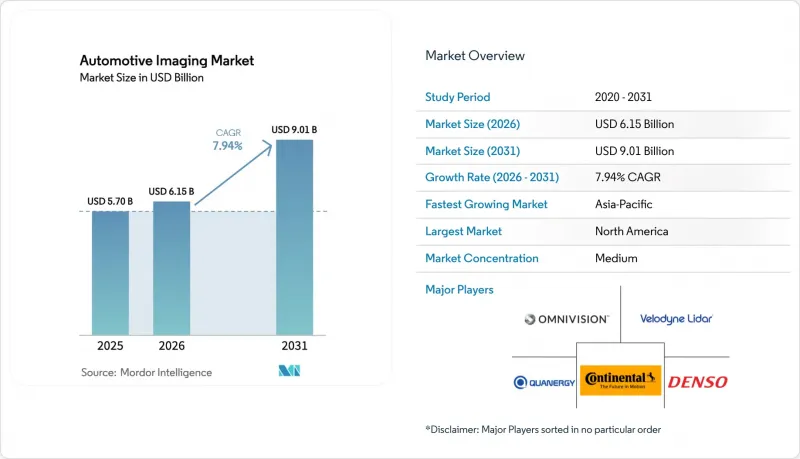
This report is Segmented by Product Type (CMOS Image Sensors and Camera Modules and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles and More), Level of Automation (SAE L0-L1, SAE L2, and More), Application (Rear View, 360-Surround and More), Imaging Technology (2-D CMOS, 3-D ToF / Structured Light and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Imaging Market Trends and Insights
Heightened NCAP-driven Multi-camera Mandates
Evolving NCAP rules require broader camera coverage for higher safety ratings. The US National Highway Traffic Safety Administration ruled that all light vehicles must feature AEB by September 2029, pushing automakers to add forward, side and rear imaging units for pedestrian detection. Euro NCAP's 2026 protocol introduces enhanced vulnerable-road-user assessments, encouraging high-dynamic-range sensors able to operate in varied lighting. China NCAP 2024 implements similar multi-camera benchmarks with added emphasis on night-vision capability, further lifting demand for thermal imaging. Together, these standards turn multi-camera arrays into foundational safety infrastructure rather than premium options. Suppliers that deliver AEC-Q-qualified 8-Mpixel sensors stand to benefit as OEMs converge on four- to six-camera baselines for all trims of future model years.
Cost-down of Stacked SPAD ToF Sensors Below USD 50
Sony's IMX479 stacked SPAD depth sensor exemplifies how manufacturing scale drives solid-state LiDAR costs below USD 50, unlocking depth perception for mid-tier vehicles. SPAD arrays now achieve 37% photon-detection efficiency at 300 m range, meeting ISO 26262 redundancy guidelines without mechanical scanning. Automakers leverage the economic crossover to deploy hybrid camera-LiDAR bundles that mitigate corner-case failures and improve automatic emergency braking performance. Industry trackers anticipate SPAD-based ToF penetration to exceed 40% of global new-vehicle programs by 2027, compared with under 5% in 2024, confirming the cost inflection as a key growth catalyst for the automotive imaging market.
Persistent Thermal Management Issues in 120 °C Engine Bays
Cameras mounted near radiators or exhaust manifolds face temperature cycling from -40 °C to +125 °C, compromising alignment and accelerating component aging. Samsung Electro-Mechanics is readying weather-proof modules with lens heating and hydrophobic coatings, but these counter-measures inflate bill-of-materials cost. STMicroelectronics' VG6640 sensor extends operation to +125 °C, yet sustained exposure still erodes signal-to-noise margins. Thermal stress therefore hinders free placement of forward-facing cameras and limits uptake in certain vehicle segments, tempering growth for the automotive imaging market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Shift to 8-Mpixel HDR Image Sensors in ADAS
- Robotaxi Pilots Triggering >12-camera Architectures
- L4 Regulatory Ambiguity Delaying High-Volume LiDAR Take-rate
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
CMOS image sensors accounted for 38.10% of 2025 revenue and set the cadence for the automotive imaging market size because nearly every vehicle grade depends on at least one CMOS-based camera. Sony aims to lift its automotive share to 43% by fiscal 2026 on the strength of stacked-sensor roadmaps and stable wafer supply contracts. Increasing frame rates and HDR levels allow a single 8-Mpixel module to replace multiple VGA units, cutting harness weight while raising content value. The segment also benefits from cost-optimized wafer stacking that integrates AI ISP blocks, shortening development cycles for Tier 1 modules.
Solid-state LiDAR, in contrast, contributed a modest revenue base in 2025 but demonstrates a 28.15% CAGR through 2031, the fastest across product categories in the automotive imaging market. Vendors such as Luminar deliver 4-fold performance gains and 50% cost reductions in one product turn, shrinking housing dimensions to fit behind windshield blackouts. Mass-market adoption accelerates when OEMs pair LiDAR with existing camera suites for higher NCAP ratings, unlocking advanced hands-free features. The combination of volume CMOS shipments and high-growth LiDAR pulls supporting segments-vision processors, ToF sensors and camera-module assemblies-up the value chain.
Passenger cars generated 62.40% of automotive imaging market demand in 2025, anchored by global AEB mandates that compel inclusion of rear-view and forward-facing cameras. Typical C-segment sedans now ship with eight imagers; mid-cycle refreshes slated for 2027 already blueprint for twelve. Rising trim penetration for 360-degree surround-view cameras further elevates average sensor counts, sustaining high wafer utilization at foundry partners.
Robotaxis and shuttles, albeit smaller in unit terms, carry a 37.25% CAGR that outpaces every other vehicle category. Fleet operators insist on redundant camera-LiDAR-radar stacks exceeding 50 sensors to meet no-driver fallback requirements. These reference designs validate megapixel-grade thermal imagers, 4-D radar and multi-camera synchronization networks that later flow into premium passenger vehicles. The technology spillover feeds cross-segment scalability, cementing the automotive imaging market as a beneficiary of autonomous mobility trials.
Complete Report Scope:
- By Product Type
- CMOS Image Sensors
- Camera Modules
- Vision Processors / ISP
- LiDAR Units
- Radar Sensors
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Robotaxis and Shuttles
- By Level of Automation
- SAE L0-L1
- SAE L2
- SAE L2+
- SAE L3
- SAE L4+
- By Application
- Rear View
- 360-Surround
- Forward ADAS
- Night-Vision & Side-Mirror Replacement
- In-Cabin Driver/Occupant Monitoring
- Dashboard / Event Data
- By Imaging Technology
- 2-D CMOS
- 3-D ToF / Structured Light
- Mechanical LiDAR
- Solid-State LiDAR
- 4-D Imaging Radar
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific led with 41.60% of 2025 revenue and an 11.1% CAGR outlook, anchored by China's aggressive electrification targets and LiDAR scale. Hesai alone captured 37% global LiDAR shipments, extending from robotaxis into premium EVs. Japanese suppliers add momentum; Sony seeks 43% of global automotive CMOS share by 2026 as domestic OEMs expand camera counts. South Korea contributes through Samsung Electro-Mechanics' weather-proof modules, mitigating regional hot-climate challenges. These developments ensure a continuous pull for sensor wafers, modules and AI processors throughout the region.
North America remains the second-largest market due to early autonomous pilot programs and firm NHTSA timelines for AEB deployment. High-power compute availability and a robust software ecosystem accelerate the adoption of camera-centric ADAS across both passenger cars and robotaxi fleets. Regional suppliers secure long-term allocation of 8-Mpixel sensors, minimizing exposure to potential supply disruptions.
Europe sustains strong demand, propelled by Euro NCAP's 2026 scoring model that weights pedestrian and cyclist protection heavily. German premium brands incorporate multi-modal sensor fusion to defend market positioning, fostering uptake of 4-D radar and thermal imagers. Middle East and Africa, although nascent, mimic European regulation over time, while South America catches up as local safety agencies tighten crash-avoidance criteria. Across all territories, regulated safety performance underpins the automotive imaging market's resilience to macroeconomic cycles.
- Sony Group Corporation
- ON Semiconductor Corporation
- OmniVision Technologies, Inc.
- Samsung Electronics Co., Ltd.
- Panasonic Holdings Corporation
- STMicroelectronics N.V.
- Robert Bosch GmbH
- Continental AG
- Aptiv plc
- ZF Friedrichshafen AG
- Valeo SE
- Magna International Inc.
- DENSO Corporation
- Veoneer Holdings Ltd.
- LG Electronics Inc.
- Luminar Technologies, Inc.
- Innoviz Technologies Ltd.
- Hesai Group
- RoboSense (Beijing) Technology Co., Ltd.
- PIXELPLUS Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Heightened NCAP-driven multi-camera mandates
- 4.2.2 Cost-down of stacked SPAD ToF sensors below US$50
- 4.2.3 Rapid shift to 8-Mpixel HDR image sensors in ADAS
- 4.2.4 Robotaxi pilots triggering >12-camera architectures
- 4.2.5 Cyber-secure OTA update regulations (UNECE R156)
- 4.2.6 Integrated AI ISP reducing latency by 30%
- 4.3 Market Restraints
- 4.3.1 Persistent thermal management issues in 120 °C engine bays
- 4.3.2 L4 regulatory ambiguity delaying high-volume LiDAR take-rate
- 4.3.3 Silicon supply crunch for BSI pixels <2 µm
- 4.3.4 Radar-camera fusion IP litigation risk
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 CMOS Image Sensors
- 5.1.2 Camera Modules
- 5.1.3 Vision Processors / ISP
- 5.1.4 LiDAR Units
- 5.1.5 Radar Sensors
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Heavy Commercial Vehicles
- 5.2.4 Robotaxis and Shuttles
- 5.3 By Level of Automation
- 5.3.1 SAE L0-L1
- 5.3.2 SAE L2
- 5.3.3 SAE L2+
- 5.3.4 SAE L3
- 5.3.5 SAE L4+
- 5.4 By Application
- 5.4.1 Rear View
- 5.4.2 360-Surround
- 5.4.3 Forward ADAS
- 5.4.4 Night-Vision & Side-Mirror Replacement
- 5.4.5 In-Cabin Driver/Occupant Monitoring
- 5.4.6 Dashboard / Event Data
- 5.5 By Imaging Technology
- 5.5.1 2-D CMOS
- 5.5.2 3-D ToF / Structured Light
- 5.5.3 Mechanical LiDAR
- 5.5.4 Solid-State LiDAR
- 5.5.5 4-D Imaging Radar
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 Middle East
- 5.6.4.1 Israel
- 5.6.4.2 Saudi Arabia
- 5.6.4.3 United Arab Emirates
- 5.6.4.4 Turkey
- 5.6.4.5 Rest of Middle East
- 5.6.5 Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Egypt
- 5.6.5.3 Rest of Africa
- 5.6.6 South America
- 5.6.6.1 Brazil
- 5.6.6.2 Argentina
- 5.6.6.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Sony Group Corporation
- 6.4.2 ON Semiconductor Corporation
- 6.4.3 OmniVision Technologies, Inc.
- 6.4.4 Samsung Electronics Co., Ltd.
- 6.4.5 Panasonic Holdings Corporation
- 6.4.6 STMicroelectronics N.V.
- 6.4.7 Robert Bosch GmbH
- 6.4.8 Continental AG
- 6.4.9 Aptiv plc
- 6.4.10 ZF Friedrichshafen AG
- 6.4.11 Valeo SE
- 6.4.12 Magna International Inc.
- 6.4.13 DENSO Corporation
- 6.4.14 Veoneer Holdings Ltd.
- 6.4.15 LG Electronics Inc.
- 6.4.16 Luminar Technologies, Inc.
- 6.4.17 Innoviz Technologies Ltd.
- 6.4.18 Hesai Group
- 6.4.19 RoboSense (Beijing) Technology Co., Ltd.
- 6.4.20 PIXELPLUS Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

