PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116801

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116801
Military Transport - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the military transport market size in 2026 is estimated at USD 24.14 billion, growing from 2025 value of USD 22.79 billion with 2031 projections showing USD 32.23 billion, growing at 5.92% CAGR over 2026-2031.
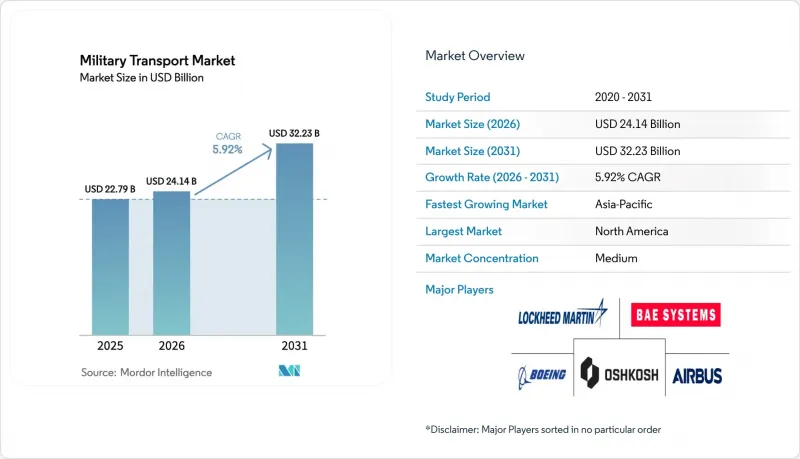
This report is Segmented by Platform Type (Ground Transport Vehicles, Naval Transport Vessels, and Air Transport Aircraft), Application (Personnel Transport, Cargo/Equipment Transport, and More), Propulsion Technology (Conventional, Hybrid-Electric, and Others), End User (Army, Navy, and Air Force), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Military Transport Market Trends and Insights
Growing Global Demand for Strategic and Tactical Airlift Capabilities
Japan's decision to add 13 KC-46A tankers and 17 CH-47 Block II Chinooks underscores rising lift requirements for Indo-Pacific missions. China promotes its Y-20B airlifter to states like Nigeria, expanding competition beyond traditional suppliers. A decade of A400M Atlas service with the RAF validates the platform's 37-ton payload and 8,900 km unrefuelled range for combat and humanitarian tasks. Demand is reinforced by multinational exercises that move heavy equipment across long distances, compelling air forces to enlarge their fleets. These procurements steadily widen the addressable base for maintenance, training, and ground-support contracts within the military transport market.
Operational Shift Toward Rapid Deployment in Decentralized Warfare Environments
Doctrine now centers on agile units able to disperse and re-aggregate quickly across multiple domains. The US Army's Next Generation Tactical Vehicle-Hybrid offers Silent Drive and Watch modes, permitting covert convoy movement and on-board power generation. Australia's Talisman Sabre exercise, involving 35,000 personnel from 19 countries, highlighted how US watercraft supported littoral logistics quickly. China integrates high-speed rail into mobilization plans, reducing transit times for brigades traversing vast distances. Such concepts push demand for versatile platforms that load and unload quickly, reinforcing procurement pipelines for tactical trucks, tilt-rotors, and mobile port equipment within the military transport market.
Supply Chain Vulnerabilities Affecting Aerospace-Grade Material Availability
Material shortages undermine production schedules for aircraft, trucks, and naval hulls that demand aerospace-grade aluminum, titanium, and rare-earth alloys. The Pentagon has listed 280 critical material dependencies, many tied to Chinese supply chains, exposing programs that rely on specialty metals and electronic components. European manufacturers are adopting dual-sourcing and accepting longer lead times, with Airbus revising A400M delivery calendars while Rheinmetall buys US suppliers to secure titanium feedstock and machining capability. Semiconductor scarcity exacerbates the problem; lead times for military-grade chips have stretched from 12 weeks to more than 52 weeks, forcing avionics engineers to redesign boards around whatever parts can be sourced. Mitigation measures such as the US CHIPS Act and the European Critical Raw Materials Act promise fresh capacity. Yet, new foundries and processing plants will not reach volume for at least three years, keeping near-term production risk elevated. These constraints delay the fielding of new lift assets and reduce the annual delivery profile that underpins the military transport market.
Other drivers and restraints analyzed in the detailed report include:
- Modernization and Recapitalization of Aging Military Transport Fleets
- Rising Frequency of Global Humanitarian and Disaster-Relief Missions
- Budgetary Shifts Toward Unmanned Systems Amid Rising Defense Inflation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ground vehicles captured 42.12% of the military transport market share in 2025 while registering the fastest 9.52% CAGR projection to 2031. Programs such as the USD 1.54 billion FHTV V contract and continued FMTV A2 orders are refreshing heavy and medium truck fleets with enhanced payload protection and digital diagnostics. The military transport market size for heavy tactical trucks is primed to rise as armies adopt modular architectures that integrate power distribution units for directed-energy or command-and-control payloads. Hybrid-electric conversions are cascading across light and medium platforms. GM Defense's Next Generation Tactical Vehicle-Hybrid delivers silent-watch functionality and exportable 120 kW power, supporting sensors and unmanned systems in austere sites. Armored logistics carriers such as Rheinmetall's TGS-Mil Protected unite NATO Level 3 protection with 4X4 drivetrains optimized for expeditionary ops.
Naval transport vessels continue to evolve through roll-on/roll-off hull forms and enhanced beaching capabilities. India's 200 m Landing Platform Dock program integrates electric propulsion and 60-day endurance, offering humanitarian assistance scalability for Indo-Pacific settings. Concurrently, airlift platforms such as the A400M Atlas mark milestones that validate multi-domain integration, with Airbus now showcasing a variant able to network swarming drones. These advances widen capability gaps that drive procurement of blended fleets across the military transport market.
Cargo and equipment transport preserved a 45.73% revenue lead in 2025, underpinning the routine movement of ammunition, bridging systems, and armored vehicles worldwide. Within this segment, the C-17 Globemaster and A400M Atlas remain indispensable for outsize loads and austere-strip operations, maintaining robust utilization rates during exercises such as Australia's Pitch Black and multinational relief sorties.
Humanitarian and disaster-relief missions are expected to grow faster than any other application, recording a 7.06% CAGR to 2031. The Gaza pier operation validated Joint Logistics Over-the-Shore constructs, spurring fresh interest in modular causeways and sealift connectors. India's evolution from regional responder to global evacuator underscores political value in fast, credible lift. Autonomous casualty evacuation robots, like the Expeditionary Modular Autonomous Vehicle, showcase how unmanned ground systems can shorten the critical care timeline, raising tactical and strategic stakes within the military transport market size for humanitarian tasks. Personnel transport continues to absorb investment, particularly for rotary-wing fleets that hoist troops into dispersed landing zones. Medevac and emergency rescue variants leverage augmented-reality medical displays and secure telemetry links that improve in-flight triage. These upgrade cycles ensure the broader military transport industry addresses complex scenarios ranging from urban search-and-rescue to expeditionary peacekeeping.
Complete Report Scope:
- By Platform Type
- Ground Transport Vehicles
- Heavy Tactical Trucks
- Light Utility Vehicles
- Armored Logistics and MRAPs
- Naval Transport Vessels
- Roll-on/Roll-off (Ro-Ro) and Sealift Ships
- Landing Platform Docks (LPD/LHD)
- Auxiliary Cargo and Replenishment Ships
- Air Transport Aircraft
- Fixed-Wing
- Rotary and Tilt-Rotor
- Ground Transport Vehicles
- By Application
- Personnel Transport
- Cargo/Equipment Transport
- Emergency Rescue and Medevac
- Humanitarian and Disaster-relief
- By Propulsion Technology
- Conventional
- Hybrid-Electric
- Others
- By End User
- Army
- Navy
- Air Force
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 32.12% of the military transport market in 2025, powered by the United States' USD 214.8 million FMTV A2 truck buy, USD 360 million MV-22B modernization, and multiple aerial refueler programs. Canada is fielding Arctic patrol ships and joint support vessels that strengthen NATO's resilience in the High North. The region's leadership in AI diagnostics and hybrid-electric propulsion positions domestic suppliers to capture export orders, further enlarging the military transport market.
Asia-Pacific is projected to be the fastest-growing region at 7.18% CAGR. China inducts next-generation heavy trucks, advances Y-20B airlifter production, and integrates high-speed rail into mobilization doctrine. Japan's multibillion-dollar airlift and helicopter purchases and South Korea's USD 8.8 billion procurement approvals signal a broad commitment to logistics modernization. Historical investment since 2019 shows a steady shift from platform quantity to capability depth, reinforcing growth prospects for the military transport market in the region.
Europe maintains robust demand via multinational frameworks and national programs. Germany's EUR 3.5 billion (USD 4.05 billion) vehicle agreement underpins continental logistics readiness. The trilateral Future Mid-Size Tactical Cargo initiative allocates EUR 30 million (USD 34.71 million) to design a C-130 replacement by 2040, demonstrating collaborative innovation. Consolidation moves such as Leonardo's Iveco Defence purchase concentrate expertise and align supply chains, keeping Europe a pivotal contributor to the military transport market.
List of Companies Covered in this Report:
- Airbus SE
- The Boeing Company
- Lockheed Martin Corporation
- Rostec
- Embraer S.A.
- Leonardo S.p.A.
- Kawasaki Heavy Industries, Ltd.
- Tata Advanced Systems Limited
- Rheinmetall AG
- Oshkosh Defense, LLC (Oshkosh Corporation)
- BAE Systems plc
- General Dynamics Corporation
- Textron Inc.
- Hyundai Rotem Company
- Israel Aerospace Industries Ltd.
- ANTONOV COMPANY (State Concern "Ukroboronprom")
- ND Defense LLC
- Iveco Defence Vehicles (Iveco Group)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing global demand for strategic and tactical airlift capabilities
- 4.2.2 Operational shift toward rapid deployment in decentralized warfare environments
- 4.2.3 Modernization and recapitalization of aging military transport fleets
- 4.2.4 Rising frequency of global humanitarian and disaster relief missions
- 4.2.5 Increased adoption of dual-use transport platforms with civil certification pathways
- 4.2.6 Integration of AI-driven predictive maintenance to optimize life-cycle costs
- 4.3 Market Restraints
- 4.3.1 Supply chain vulnerabilities affecting aerospace-grade material availability
- 4.3.2 Budgetary shifts toward unmanned systems amid rising defense inflation
- 4.3.3 Limited global shipyard capacity for large roll-on/roll-off vessel construction
- 4.3.4 Stricter emission regulations delaying upgrades of legacy propulsion systems
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Platform Type
- 5.1.1 Ground Transport Vehicles
- 5.1.1.1 Heavy Tactical Trucks
- 5.1.1.2 Light Utility Vehicles
- 5.1.1.3 Armored Logistics and MRAPs
- 5.1.2 Naval Transport Vessels
- 5.1.2.1 Roll-on/Roll-off (Ro-Ro) and Sealift Ships
- 5.1.2.2 Landing Platform Docks (LPD/LHD)
- 5.1.2.3 Auxiliary Cargo and Replenishment Ships
- 5.1.3 Air Transport Aircraft
- 5.1.3.1 Fixed-Wing
- 5.1.3.2 Rotary and Tilt-Rotor
- 5.1.1 Ground Transport Vehicles
- 5.2 By Application
- 5.2.1 Personnel Transport
- 5.2.2 Cargo/Equipment Transport
- 5.2.3 Emergency Rescue and Medevac
- 5.2.4 Humanitarian and Disaster-relief
- 5.3 By Propulsion Technology
- 5.3.1 Conventional
- 5.3.2 Hybrid-Electric
- 5.3.3 Others
- 5.4 By End User
- 5.4.1 Army
- 5.4.2 Navy
- 5.4.3 Air Force
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 France
- 5.5.2.3 Germany
- 5.5.2.4 Spain
- 5.5.2.5 Russia
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Airbus SE
- 6.4.2 The Boeing Company
- 6.4.3 Lockheed Martin Corporation
- 6.4.4 Rostec
- 6.4.5 Embraer S.A.
- 6.4.6 Leonardo S.p.A.
- 6.4.7 Kawasaki Heavy Industries, Ltd.
- 6.4.8 Tata Advanced Systems Limited
- 6.4.9 Rheinmetall AG
- 6.4.10 Oshkosh Defense, LLC (Oshkosh Corporation)
- 6.4.11 BAE Systems plc
- 6.4.12 General Dynamics Corporation
- 6.4.13 Textron Inc.
- 6.4.14 Hyundai Rotem Company
- 6.4.15 Israel Aerospace Industries Ltd.
- 6.4.16 ANTONOV COMPANY (State Concern "Ukroboronprom")
- 6.4.17 ND Defense LLC
- 6.4.18 Iveco Defence Vehicles (Iveco Group)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

