PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117202

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117202
Anti-Biofilm Wound Dressing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the anti-biofilm wound dressings market size in 2026 is estimated at USD 1.04 billion, growing from 2025 value of USD 0.95 billion with 2031 projections showing USD 1.63 billion, growing at 9.41% CAGR over 2026-2031.
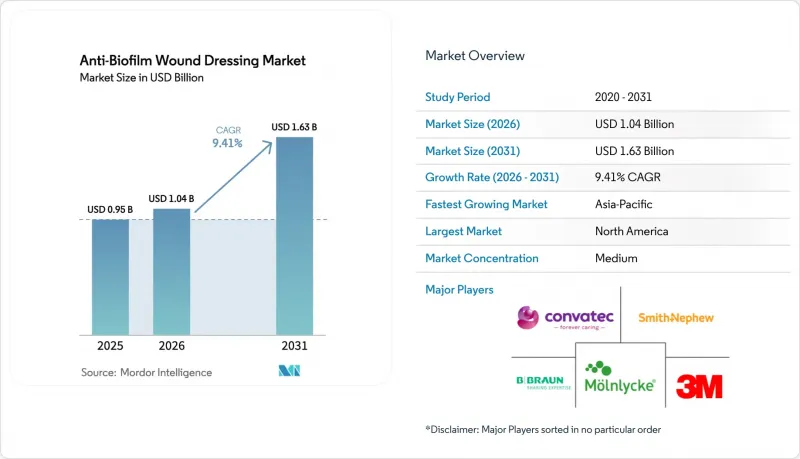
This report is Segmented by Mechanism (Physical, Chemical, and Biological), Wound Type (Chronic Wounds and Acute Wounds), Dressing Material (Foam, Hydrogel, and More), Active Antimicrobial Agent (Silver-Based, Iodine-Based, and More), End-User (Hospitals and Clinics, Ambulatory Surgical Centers, and More), and Geography. The Report Offers the Value (in USD Million) for the Above Segments.
Global Anti-Biofilm Wound Dressing Market Trends and Insights
Rising Prevalence of Chronic Wounds
Chronic wounds now impose an AUD 2-4 billion (USD 1.3-2.6 billion) annual burden in Australia alone. Older adults and people with diabetes present impaired immunity that fosters biofilm formation, and 80% of non-healing ulcers have biofilms. The epidemiology is shifting treatment protocols toward dressings able to dismantle biofilm architecture. Procurement policies now specify anti-biofilm capability, especially for home health programs where nurse oversight is limited. This momentum elevates demand for solutions that shorten healing time and curb systemic antibiotic use.
Surge in Surgical Procedures
Global surgical volume is rising fastest in Asia-Pacific. Acute wounds from operations can form biofilms within hours, prompting hospitals to add anti-biofilm dressings to peri-operative bundles. Silver-coated sutures cut Staphylococcus aureus and multi-drug-resistant Pseudomonas aeruginosa colonization in controlled trials. Orthopedic and cardiac centers now extend biofilm-prevention protocols to closed-incision care, expanding addressable demand beyond chronic wounds. As a result, the anti-biofilm wound dressings market is embedding into surgical infection control budgets.
High Product Cost vs. Conventional Dressings
Premium price points challenge uptake, especially in publicly funded systems that still reimburse commodity gauze. Yet real-world evidence shows total treatment expense drops when anti-biofilm dressings cut healing time and facility visits. The 2025 Medicare Physician Fee Schedule expands tele-wound codes, letting clinicians guide community nurses remotely and reduce inpatient stays. As payers reward outcome-based pathways, budget silos are breaking, and upfront cost barriers are softening.
Other drivers and restraints analyzed in the detailed report include:
- Product Innovation in Advanced Wound Care
- Stewardship Shift to Topical Therapies
- Emerging Bacterial Tolerance to Silver Ions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Chemical mechanisms retained 45.12% of the anti-biofilm wound dressings market in 2025 on the back of mature silver and iodine technologies that hospitals trust for broad-spectrum cover. Physical strategies, such as structured foams that shear microbial films, hold a middle share for patients needing exudate control. Yet biological platforms are carving space at a 9.86% CAGR. Enzymatic disruptors like recombinant Tarumase digest fibrin, collagen, and elastin-the scaffolds that stabilize biofilms-overcoming the penetration limits of many chemicals.
Second-generation dressings now blend biological and chemical modes. A single substrate may release PHMB for immediate bactericidal action and a protease for matrix breakdown, delivering a one-two punch that clinicians can deploy without double dressing changes. Integrated mechanisms lower nursing hours, a key cost driver in chronic-care wards, and they future-proof portfolios against emerging silver tolerance. Because reimbursement codes reward evidence-based outcomes, suppliers that validate multi-mechanism efficacy are pulling formulary preference away from single-mode incumbents.
Alginate fibers commanded 39.21% of revenue in 2025 due to high absorptive capacity and gentle gel formation that does not strip fragile tissue during changes. Their calcium-rich lattice also binds ionic silver, making alginate a favored carrier for antimicrobial release. Foam dressings remain widespread for moderate exudate because of cushioning and cost advantages, while thin hydrogels serve niche rehydration roles.
Hydrocolloids are on track for a 9.58% CAGR. New formulations impregnate hydrophobic particles that breach biofilms and subsequently swell to seal the wound, limiting environmental contamination. Manufacturers extend wear time to seven days, which reduces change frequency and nursing labor. Nanofiber mats and electrospun membranes are gaining clinical trial traction, but production scale remains a hurdle. Bacterial cellulose, harvested through green fermentation, is entering value-based procurement lists because it is biodegradable and naturally antimicrobial-aligning with hospital sustainability mandates.
Complete Report Scope:
- By Mechanism
- Physical
- Chemical
- Biological
- By Dressing Material
- Foam
- Hydrogel
- Hydrocolloid
- Alginate
- Film & Membrane
- Nanofiber / Electrospun
- Bacterial Cellulose
- By Active Antimicrobial Agent
- Silver-based
- Iodine-based
- Polyhexanide (PHMB)
- Honey / Natural Bio-actives
- Chitosan & Other Biopolymers
- Metal-oxide Nanoparticles
- By Wound Type
- Chronic Wounds
- Diabetic Foot Ulcers
- Pressure Ulcers
- Venous Leg Ulcers
- Other Chronic Wounds
- Acute Wounds
- Surgical / Traumatic Wounds
- Burns
- Chronic Wounds
- By End User
- Hospitals & Clinics
- Ambulatory Surgical Centers
- Home Healthcare Settings
- Military & Emergency Care
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America continued to lead, delivering 41.02% of 2025 revenue as payers reimbursed advanced dressings and hospitals adopted digital wound surveillance. The region hosts the largest concentration of trials and has clear coding pathways such as the 2025 CMS updates that clarify coverage for skin substitutes . The United States Food and Drug Administration's re-classification proposal is expected to tighten evidence standards, favoring companies with robust clinical datasets.
Europe offers a sophisticated regulatory environment shaped by the EU Medical Device Regulation 2017/745, which imposes traceability and performance reporting . Environmental stewardship drives hospitals to pilot biodegradable and metal-free platforms. The European Wound Management Association updates consensus documents that influence clinician purchasing. Germany and France run national tender systems rewarding suppliers that can document both efficacy and waste reduction.
Asia-Pacific displayed the highest momentum, expanding at an 10.62% CAGR through 2031. China's domestic bandage output and hospital modernisation lower price points, widening access. Japan's super-aged society prioritises home wound care solutions that reduce caregiver burden. India's production-linked incentives for medical devices lure multinational partners seeking cost-efficient capacity. Australia highlights the economic toll of chronic wounds, boosting reimbursement for advanced dressings through state health plans.
- 3M
- Smiths Group
- ConvaTec Group plc
- Molnlycke Health Care
- Coloplast
- B. Braun
- Urgo Medical
- Medline Industries
- Integra LifeSciences
- Imbed Biosciences
- Lohmann & Rauscher
- Argentum Medical
- KCI (Acelity)
- Hartmann Group
- DermaRite Industries
- Silverlon (Argentum)
- Genadyne Biotechnologies
- Kerecis
- Covalon Technologies
- Medtronic
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of chronic wounds
- 4.2.2 Surge in surgical procedures
- 4.2.3 Product innovation in advanced wound care
- 4.2.4 Reimbursement support for antimicrobial dressings
- 4.2.5 Stewardship shift from systemic to topical therapies
- 4.2.6 AI-enabled digital wound platforms accelerating adoption
- 4.3 Market Restraints
- 4.3.1 High product cost vs. conventional dressings
- 4.3.2 Regulatory ambiguity for combination dressings
- 4.3.3 Emerging bacterial tolerance to silver ions
- 4.3.4 Environmental disposal concerns for nano-dressings
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD Million)
- 5.1 By Mechanism
- 5.1.1 Physical
- 5.1.2 Chemical
- 5.1.3 Biological
- 5.2 By Dressing Material
- 5.2.1 Foam
- 5.2.2 Hydrogel
- 5.2.3 Hydrocolloid
- 5.2.4 Alginate
- 5.2.5 Film & Membrane
- 5.2.6 Nanofiber / Electrospun
- 5.2.7 Bacterial Cellulose
- 5.3 By Active Antimicrobial Agent
- 5.3.1 Silver-based
- 5.3.2 Iodine-based
- 5.3.3 Polyhexanide (PHMB)
- 5.3.4 Honey / Natural Bio-actives
- 5.3.5 Chitosan & Other Biopolymers
- 5.3.6 Metal-oxide Nanoparticles
- 5.4 By Wound Type
- 5.4.1 Chronic Wounds
- 5.4.1.1 Diabetic Foot Ulcers
- 5.4.1.2 Pressure Ulcers
- 5.4.1.3 Venous Leg Ulcers
- 5.4.1.4 Other Chronic Wounds
- 5.4.2 Acute Wounds
- 5.4.2.1 Surgical / Traumatic Wounds
- 5.4.2.2 Burns
- 5.4.1 Chronic Wounds
- 5.5 By End User
- 5.5.1 Hospitals & Clinics
- 5.5.2 Ambulatory Surgical Centers
- 5.5.3 Home Healthcare Settings
- 5.5.4 Military & Emergency Care
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 3M
- 6.3.2 Smith+Nephew
- 6.3.3 ConvaTec Group plc
- 6.3.4 Molnlycke Health Care AB
- 6.3.5 Coloplast A/S
- 6.3.6 B. Braun SE
- 6.3.7 Urgo Medical
- 6.3.8 Medline Industries LP
- 6.3.9 Integra LifeSciences
- 6.3.10 Imbed Biosciences
- 6.3.11 Lohmann & Rauscher
- 6.3.12 Argentum Medical
- 6.3.13 KCI (Acelity)
- 6.3.14 Hartmann Group
- 6.3.15 DermaRite Industries
- 6.3.16 Silverlon (Argentum)
- 6.3.17 Genadyne Biotechnologies
- 6.3.18 Kerecis
- 6.3.19 Covalon Technologies
- 6.3.20 Medtronic Plc
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

