PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117286

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117286
Thrust Vector Control - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the thrust vector control market size is expected to grow from USD 14.39 billion in 2025 to USD 15.67 billion in 2026 and is forecasted to reach USD 23.83 billion by 2031 at an 8.74% CAGR over 2026-2031.
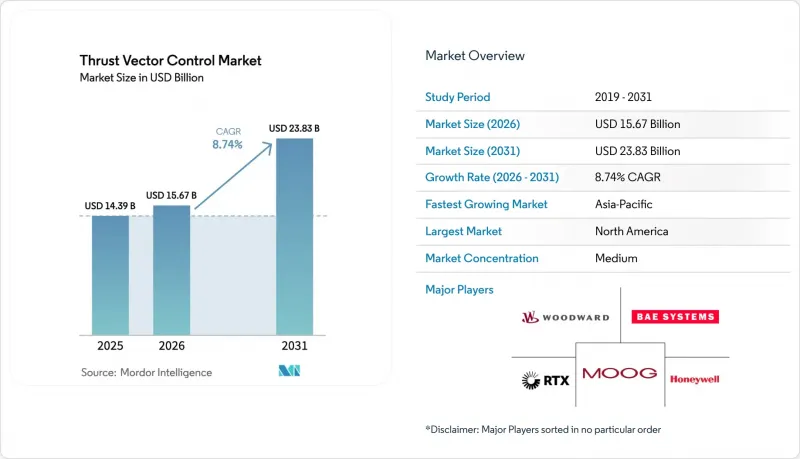
This report is Segmented by Application (Launch Vehicles, Satellites, Missiles, and Combat Aircraft), End User (Defense and Space Agencies), Technology (Gimbal Nozzle, Flex Nozzle, Thrusters, and Rotating Nozzle), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Thrust Vector Control Market Trends and Insights
Rising Launch-Vehicle Cadence and Small-Sat Demand
Global launch operations scaled to record levels in 2024 and then accelerated through 2025, with SpaceX conducting 165 orbital missions that accounted for the bulk of US activity and driving steady demand for thrust vector control systems and spares across first- and second-stage systems. Chinese commercial launch firms advanced reusable methane-fueled vehicles, and program milestones set in 2025 and 2026 signaled a region-wide shift toward reusable platforms that intensify actuator duty cycles and ground turnaround work. Reusability has increased post-flight inspections and component refurbishment, which increases the lifetime value for thrust vector control providers as launch frequency rises and fleets age. Large constellation programs such as Project Kuiper have booked launch capacity across multiple providers, which underpins long-range demand for vectoring hardware on both heavy-lift and medium-lift vehicles used to seed orbit planes at pace. This scale introduces more exacting requirements for actuator responsiveness and thermal resilience, especially for rapid relight and precision landing maneuvers in reusable operations. The thrust vector control market benefits from this cadence-driven expansion because higher flight rates and reflight targets increase the installed base, the maintenance loop, and the need for digital control upgrades over time.
Missile Fleet Modernization in Major Defense Budgets
Munitions and missile defense recapitalization programs are scaling through multi-year procurements and capacity expansions, creating stable demand for guidance, control, and thrust vectoring subsystems across air defense, cruise missiles, and interceptors. Global military expenditure rose meaningfully in 2024, and public budgets in 2025 and 2026 have prioritized standoff strike, integrated air and missile defense, and long-range fires, which pull through actuation hardware and control electronics. Japan approved its largest defense budget to date for fiscal 2026, allocating significant funds to standoff missile capability, including domestic Type-12 surface-to-ship missiles, which sustains demand for vectoring, fin actuation, and control units across production lots. Prime contractors have formalized framework agreements to accelerate output of critical munitions, with production targets reaching into the thousands per year across multiple lines, supporting supplier tooling, workforce expansion, and long-lead material contracts for thrust vector control components. This procurement tempo underscores the value of modularity and common interfaces for actuators and control cards, enabling adaptation across families of missiles with minimal redesign, thereby shortening qualification cycles and reducing unit cost over time. As these modernization waves continue, the thrust vector control market captures growth from both new starts and retrofit programs that upgrade legacy inventories to meet new range, maneuverability, and survivability requirements.
High Qualification and Certification Cost
Human spaceflight and national security programs impose rigorous standards, driving extensive verification and validation test campaigns for propulsion vectoring systems that add time and expense to development. NASA's Aerospace Safety Advisory Panel highlighted structural and process challenges in developmental programs, reinforcing the need for strong systems engineering oversight and safety assurance, which can increase cost and delay certification for complex actuation and control elements. Commercial cargo and crew programs impose strict requirements on hardware and software integration, telemetry, and fault management, resulting in detailed documentation and qualification artifacts for thrust vector control components. FAA oversight in commercial human spaceflight adds another layer of safety processes, mishap review requirements, and return-to-flight conditions that affect propulsion vectoring systems and associated command software. These combined demands can stress smaller suppliers that lack large compliance teams, prompting them to partner with primes that already maintain mature quality systems and certification pathways. As a result, incumbents have an advantage in capturing high-assurance programs, while challengers must fund significant non-recurring engineering and qualification work before entering serial production. This cost intensity acts as a structural headwind for broad-based entry in the thrust vector control market.
Other drivers and restraints analyzed in the detailed report include:
- Reusable Rockets Amplifying TVC Maintenance Cycles
- Commercial Space-Tourism and Private Crewed-Mission Boom
- Stringent Reliability/Safety Thresholds in Human-Rated Flight
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Launch vehicles accounted for 48.73% of the thrust vector control market share in 2025, driven by reusable booster fleets and high-cadence constellation deployments. Reusability has increased lifecycle demand for actuators and vectoring hardware by enabling more maintenance cycles per vehicle. High launch rates in the US in 2025 highlighted the need for actuator reliability across repeated landings and rapid relights. Parallel developments in China with recoverable methane vehicles indicate a multi-regional opportunity for ruggedized TVC actuation and control electronics. These trends enhance the installed base, supporting predictive maintenance solutions and deeper integration of telemetry for health monitoring across thrust vector control subsystems.
Satellites are the fastest-growing application, with the thrust vector control market size for satellites projected to grow at a 10.68% CAGR from 2026 to 2031. Orbit-raising, station-keeping, and collision avoidance drive unit demand for control thrusters and precise actuation. The increasing number of active spacecraft boosts the need for reaction control systems and small thrusters. Human spaceflight logistics and cargo vehicles also influence vectoring content tied to rendezvous and docking maneuvers. As satellite volumes grow, standardization and modularity in vectoring components support common spares and lower total cost of ownership, strengthening the value proposition for operators renewing or expanding fleets.
Complete Report Scope:
- By Application
- Launch Vehicles
- Satellites
- Missiles
- Combat Aircraft
- By End User
- Defense
- Space Agencies
- By Technology
- Gimbal Nozzle
- Flex Nozzle
- Thrusters
- Rotating Nozzle
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 46.38% of the thrust vector control market share in 2025, supported by a large defense industrial base, high research and procurement outlays, and the world's highest orbital cadence led by commercial providers. SpaceX executed 165 orbital launches in 2025 and widened the installed base of reusable first stages, which require rigorous actuator maintenance and frequent inspections, thereby supporting recurring demand for electromechanical subsystems and gimbal units. The US defense procurement in 2026 focuses on missile defense, standoff strike, and hypersonic development, sustaining orders for fin actuation and nozzle vectoring. NASA programs and commercial cargo initiatives continue to anchor supplier roadmaps, as Dream Chaser's pre-flight milestones in late 2025 signaled progress toward first orbital operations, which require reliable vectoring for orbital maneuvering and reentry stability.
Asia-Pacific is projected to register the fastest growth, with the thrust vector control market in the region expanding at a 9.77% CAGR through 2031. National programs focus on reusable launch vehicles, military inventories, and sovereign satellite constellations. Chinese commercial firms reported progress on vertical recovery and planned orbital test flights through 2026, signaling demand for ruggedized vectoring systems. Japan's record defense budget for fiscal 2026 emphasizes standoff missile capability and domestic production, elevating the need for fin actuation and nozzle vectoring content.
Europe continues to invest in space resilience and dual-use capabilities, creating opportunities for thrust vector control suppliers across launch, satellites, and defense applications. The European Space Agency advanced navigation and resilience efforts, while manufacturers delivered hardware for reusable-launcher landing legs and vectoring systems to support test campaigns. In the Middle East and Africa, defense spending growth and ambitions in space contribute to a rising addressable base for vectoring and control solutions, supported by regional procurement programs and new satellite initiatives.
- Honeywell International Inc.
- Moog Inc.
- RTX Corporation
- Woodward, Inc.
- BAE Systems plc
- SABCA SA
- JASC Corporation
- Wickman Spacecraft & Propulsion Company
- Northrop Grumman Corporation
- Lockheed Martin Corporation
- Space Exploration Technologies Corp.
- Nammo AS
- IHI Corporation
- Safran S.A.
- Israel Aerospace Industries Ltd.
- Almatech SA
- Sierra Space Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising launch-vehicle cadence and small-sat demand
- 4.2.2 Missile fleet modernization in major defense budgets
- 4.2.3 Reusable rockets amplifying TVC maintenance cycles
- 4.2.4 Hypersonic weapons race among the US, China, and Russia
- 4.2.5 Commercial space-tourism and private crewed-mission boom
- 4.2.6 Transition from hydraulic to all-electric actuators
- 4.3 Market Restraints
- 4.3.1 High qualification and certification cost
- 4.3.2 Stringent reliability/safety thresholds in human-rated flight
- 4.3.3 Supply bottlenecks in high-temperature composite nozzles
- 4.3.4 Tightening export-control regimes on dual-use propulsion tech
- 4.4 Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Launch Vehicles
- 5.1.2 Satellites
- 5.1.3 Missiles
- 5.1.4 Combat Aircraft
- 5.2 By End User
- 5.2.1 Defense
- 5.2.2 Space Agencies
- 5.3 By Technology
- 5.3.1 Gimbal Nozzle
- 5.3.2 Flex Nozzle
- 5.3.3 Thrusters
- 5.3.4 Rotating Nozzle
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 United Kingdom
- 5.4.2.2 France
- 5.4.2.3 Germany
- 5.4.2.4 Russia
- 5.4.2.5 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 United Arab Emirates
- 5.4.5.1.2 Saudi Arabia
- 5.4.5.1.3 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Honeywell International Inc.
- 6.4.2 Moog Inc.
- 6.4.3 RTX Corporation
- 6.4.4 Woodward, Inc.
- 6.4.5 BAE Systems plc
- 6.4.6 SABCA SA
- 6.4.7 JASC Corporation
- 6.4.8 Wickman Spacecraft & Propulsion Company
- 6.4.9 Northrop Grumman Corporation
- 6.4.10 Lockheed Martin Corporation
- 6.4.11 Space Exploration Technologies Corp.
- 6.4.12 Nammo AS
- 6.4.13 IHI Corporation
- 6.4.14 Safran S.A.
- 6.4.15 Israel Aerospace Industries Ltd.
- 6.4.16 Almatech SA
- 6.4.17 Sierra Space Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

