PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117413

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117413
Solar Powered EV Charging Station - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the solar powered EV charging station market size was valued at USD 26.31 billion in 2025 and estimated to grow from USD 30.23 billion in 2026 to reach USD 60.57 billion by 2031, at a CAGR of 14.91% during the forecast period (2026-2031).
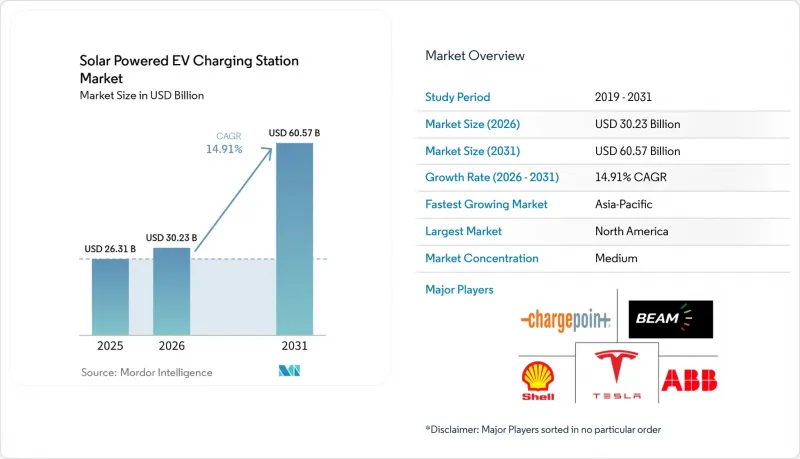
This report is Segmented by Type (Small and Medium Solar Charging Station, Large Solar Charging Station), Application (Household and Commercial/Public), Station Type (On-Grid Solar Charging Station, Off-Grid Solar Charging Station), Component (EV Charger Hardware, Solar PV Array, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Solar Powered EV Charging Station Market Trends and Insights
Declining Levelized Cost of Solar PV
Solar modules are expected to continue declining in cost, positioning on-site generation significantly below retail tariffs. Depot operators managing fleets of electric vans have seen their positive net present value expand across more U.S. states. In the U.S. Southwest, combining bifacial arrays with single-axis trackers boosts capacity factors, reducing payback periods even without tax credits. However, installations situated in northern latitudes still depend on feed-in premiums, creating a two-tier cost structure. Additionally, oversized battery storage, accounting for a significant percentage of daily load, provides a buffer against demand charges, which can constitute a substantial portion of commercial bills in regions like New York and Germany.
Grid-Congestion Surcharges Driving Behind-the-Meter Generation
PJM congestion fees have increased significantly, prompting site hosts to pivot to self-generation by deploying solar-powered EV charging stations to bypass overloaded substations. Meanwhile, California utilities introduced non-bypassable charges per kilowatt-hour, amplifying the disparity between grid imports and on-site solar. Europe is also experiencing strain: Spain is facing extended wait times for renewables, and Germany curtailed a portion of its solar output during peak hours. This has accelerated the adoption of micro-grids, particularly in logistics hubs. In New York City, delays in interconnection have driven demand for containerized solar pods that can be energized without utility approval. The financial incentives are especially compelling in areas where grid reinforcement costs are substantial per site.
Inter-Day Solar Intermittency and Need for Oversized Storage
Operators in regions with moderate sunlight are compelled to oversize batteries due to the misalignment of evening charging peaks and midday PV output. This oversizing results in an additional capital expenditure per kWh. In Germany, the solar capacity factor during winter means a significant portion of demand depends on the grid supply. While lithium-iron-phosphate chemistries, which constitute a substantial share of U.S. co-located projects, mitigate degradation, they still experience round-trip losses. In sub-Saharan Africa, extended cloudy periods necessitate reliance on diesel backup, casting doubt on the region's zero-emission assertions.
Other drivers and restraints analyzed in the detailed report include:
- Government Net-Metering and IRA-Like Incentives
- Rapid Uptake of Workplace Charging Programs
- Land-Use Permitting Bottlenecks in Urban Areas
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large stations above 150 kW are set to grow at 15.22% annually, eclipsing the 58.12% revenue held by sub-150 kW sites in 2025. The market for solar-powered EV charging stations at large depots is set to grow significantly. This growth is largely fueled by logistics fleets increasingly demanding higher charge rates. ChargePoint has introduced the Express Solo, which significantly reduces capital expenditure (capex). This innovation paves the way for megawatt-class hubs, making them feasible for major players like Amazon and UPS. Due to economies of scale in components, capex is considerably lower for higher-rated installations compared to smaller ones.
While larger stations are on the rise, smaller units continue to cater to residential and light-commercial demands, with AC units being adequate for overnight charging. SolarEdge's ONE charger directly channels surplus rooftop energy to the EV, bypassing the need for batteries. This innovation is particularly enticing for households that dominate the market. However, as larger builds face tightening regulatory scrutiny-especially with California's CEQA reviews kicking in for certain installations-some of the anticipated scale advantages are offset. On a brighter note, modular systems like Siemens' SICHARGE Flex allow operators to kick off with a smaller setup and gradually expand, simplifying the permitting process.
Households accounted for 64.33% of 2025 revenue, yet commercial and public deployments are forecast to grow 16.92% per year. The solar-powered EV charging station market is projected to grow significantly. Key drivers include employer mandates and Title 24 codes, while "charging-as-a-service" contracts help sidestep capital expenditure hurdles. In tariff-heavy states, workplace canopies accommodating large numbers of stalls achieve high internal rates.
Residential adoption is bolstered by IRA tax credits and KfW rebates in Germany. However, urban residents without driveways often rely on public or employer chargers. Bidirectional home units, like Enphase's IQ, offer resilience in grids prone to outages, making them appealing to urbanites in the U.K. and U.S. While commercial sites benefit from peak shaving and ancillary services, homeowners primarily value retail bill savings, which may temper future growth rates.
Complete Report Scope:
- By Type
- Small and Medium Solar Charging Station (Less than 150 kW)
- Large Solar Charging Station (More than 150 kW)
- By Application
- Household
- Commercial/Public
- By Station Type
- On-Grid Solar Charging Station
- Off-Grid Solar Charging Station
- By Component
- EV Charger Hardware
- Solar PV Array
- Battery Energy-Storage System (BESS)
- Power Conversion and Controls
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- South Africa
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East and Africa
- North America
Geography Analysis
North America contributed 38.92% of 2025 revenue, buoyed by IRA incentives that slashed capital requirements and led to a robust pipeline. The region successfully integrated substantial storage capacity and has ambitions to further increase it. California's congestion fees, alongside NEM 3.0, have nudged operators towards integrated solar-plus-storage sites. However, it's noteworthy that only a few states currently offer remuneration for V2G exports. Highlighting a significant demand gap, Canada faces a shortfall in workplace chargers. Meanwhile, Tesla and PG&E's pilot projects underscore the industry's readiness for bidirectional flow.
Asia-Pacific is the fastest-growing region, with a 15.86% CAGR. China, eyeing a significant target for chargers, has already increased its count. Additionally, the nation has seen a commendable uptick in the average power of public chargers. In India, while PM E-DRIVE has earmarked funds for numerous stations, the actual rollout is lagging. BYD's flash charger, with an impressive number of units already deployed, is setting new speed standards in Tier-1 cities. Japan and South Korea are advancing workplace charger rollouts, while Southeast Asia is leaning towards off-grid pods to address unreliable grid conditions.
Europe's future in the EV charging landscape is closely tied to grid integration efforts. Germany has set an ambitious goal for chargers, while France has committed substantial subsidies. However, challenges persist as Spain and Italy grapple with delays in deploying their solar-powered EV charging stations. On a brighter note, directives like ISO 15118-20 and EU building regulations are poised to catalyze workplace growth. In the U.K., with millions of households lacking home parking, there's a burgeoning demand for public solar hubs. Additionally, BMW and E.ON's collaborative pilots are investing annually in V2G frequency services.
In South America, Brazil witnessed a staggering surge in fast-charger installations, now reaching numerous municipalities. BYD is not only expanding its footprint with flash chargers but is also setting up a plant in Argentina. This facility is projected to significantly amplify the nation's current network. Furthermore, containerized solar pods are being deployed in rural provinces, effectively sidestepping the challenges posed by unstable grids.
In the Middle East and Africa, installations are strategically concentrated in regions with high solar irradiance. The UAE and Saudi Arabia are showcasing their commitment by deploying sites in prominent tourist hubs. In South Africa, persistent load shedding has accelerated the adoption of off-grid solutions. Despite nascent policy frameworks, networks such as Enzi in Kenya and ABB's Terra 360 are gaining traction, signaling growing momentum in the region.
- ABB Ltd.
- Beam Global
- Tesla Inc.
- ChargePoint, Inc.
- Siemens AG
- Shell plc
- Tritium
- Delta Electronics
- Schneider Electric
- SolarEdge
- Enphase Energy
- Wallbox
- Alfen N.V.
- EVgo
- Volta Charging
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Declining Levelized Cost of Solar PV
- 4.2.2 Grid-Congestion Surcharges Driving Behind-the-Meter Generation
- 4.2.3 Government Net-Metering and IRA-Like Incentives
- 4.2.4 Rapid Uptake of Workplace Charging Programs
- 4.2.5 Vehicle-to-Everything (V2X) Monetization Potential
- 4.2.6 Emergence of Containerized, Pre-Fab Solar Charging Pods
- 4.3 Market Restraints
- 4.3.1 Inter-Day Solar Intermittency and Need for Oversized Storage
- 4.3.2 Land-Use Permitting Bottlenecks in Urban Areas
- 4.3.3 Tariff Uncertainty for Bidirectional Export to Grid
- 4.3.4 Raw-Material Price Volatility for Li-ion ESS
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Type
- 5.1.1 Small and Medium Solar Charging Station (Less than 150 kW)
- 5.1.2 Large Solar Charging Station (More than 150 kW)
- 5.2 By Application
- 5.2.1 Household
- 5.2.2 Commercial/Public
- 5.3 By Station Type
- 5.3.1 On-Grid Solar Charging Station
- 5.3.2 Off-Grid Solar Charging Station
- 5.4 By Component
- 5.4.1 EV Charger Hardware
- 5.4.2 Solar PV Array
- 5.4.3 Battery Energy-Storage System (BESS)
- 5.4.4 Power Conversion and Controls
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 South Africa
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Saudi Arabia
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Beam Global
- 6.4.3 Tesla Inc.
- 6.4.4 ChargePoint, Inc.
- 6.4.5 Siemens AG
- 6.4.6 Shell plc
- 6.4.7 Tritium
- 6.4.8 Delta Electronics
- 6.4.9 Schneider Electric
- 6.4.10 SolarEdge
- 6.4.11 Enphase Energy
- 6.4.12 Wallbox
- 6.4.13 Alfen N.V.
- 6.4.14 EVgo
- 6.4.15 Volta Charging
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

