PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117454

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117454
Automotive Fluid Transfer System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
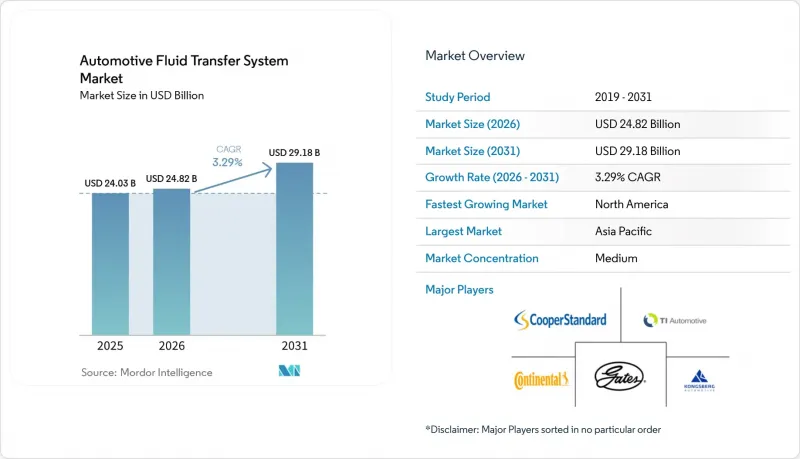
According to Mordor Intelligence, the automotive fluid transfer system market size is expected to increase from USD 24.03 billion in 2025 to USD 24.82 billion in 2026 and reach USD 29.18 billion by 2031, growing at a 3.29% CAGR over 2026-2031.
This report is Segmented by System Type (Fuel Transfer Systems, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Propulsion Type (Internal Combustion Engine, Battery Electric Vehicle, and More), Component Type (Hoses, Tubing, and More), Distribution Channel (OEM and Aftermarket), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Fluid Transfer System Market Trends and Insights
Rapid BEV/HEV Sales Growth Creating Multi-Loop Thermal-Management Fluid Circuits
Battery-electric and hybrid platforms now integrate multi-loop coolant networks that link battery cold plates, power-electronics chillers, and cabin HVAC modules. China's new GB rules, effective January 2026, mandate thermal optimization for vehicles above 2 tonnes, cementing demand for variable-speed electric pumps and low-permeation hoses. Tesla's recent dual-mode patent demonstrates how secondary CO2 loops improve low-temperature charging. Tier-1 suppliers answer with modular coolant manifolds that slash leak points and expedite assembly. As BEV ranges edge higher, quick-disconnect couplings rated for dielectric fluids are rapidly standardizing across new platforms.
Tightening Emission and Fuel-Economy Norms Accelerating Adoption of DPF/SCR Fluid Lines
Euro 7 took effect for new light-duty vehicle types on 1 July 2025. It lowers NOx ceilings and extends durability to 200,000 km, obliging OEMs to specify heated urea hoses capable of -28 °C service. The U.S. EPA's 2025 inducement update likewise enforces in-cab warnings and speed derates when DEF quality sags. India's BS-VII draft mirrors Euro 7 with real-driving emissions tracking, driving retrofits across legacy truck fleets. Collectively, these measures are entrenching high-grade SCR and DPF circuits worldwide.
ICE Phase-Out Targets Curbing Long-Term Demand for Fuel and Oil Transfer Lines
The EU's 2035 CO2 mandate and California's ZEV roadmap discourage new ICE investments, shrinking the addressable pool for gasoline and diesel lines. Automakers redirect R&D toward battery-thermal innovation, signaling a gradual sunset for conventional fuel plumbing. Suppliers hedging with BEV-centric offerings are better positioned, while aftermarket inventories of legacy fuel hoses risk obsolescence as scrappage schemes accelerate.
Other drivers and restraints analyzed in the detailed report include:
- Turbo-GDI Engine Proliferation Raising Demand for High-Temperature Oil and Coolant Lines
- Smart Hoses With Embedded Fluid-Quality Sensors Enabling Predictive Maintenance
- Volatile PA-12 Supply Inflating High-Performance Polymer Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fuel transfer systems remain the largest sub-segment, capturing 27.34% share in 2025, reflecting their ubiquity across gasoline and diesel platforms. Even so, coolant circuits are expanding at a 3.91% CAGR, propelled by the shift to multi-loop thermal-management architectures in battery-electric and hybrid vehicles. Automakers are integrating battery cold plates, power-electronics chillers, and cabin HVAC loops, all of which depend on high-performance hoses, pumps, and quick connectors. Tier-1 suppliers respond with modular coolant manifolds that cut leak paths and simplify assembly, while material specialists develop low-conductivity elastomers for dielectric fluids.
Platform redesigns under Euro 7 and comparable regulations further accelerate the pivot toward advanced coolant routing. Engineers are replacing belt-driven pumps with smart, variable-speed electric units that optimize thermal loads without sapping driveline efficiency. At the same time, direct-immersion battery cooling patents hint at an eventual reduction in discrete hoses, driving experimentation with molded composite channels inside pack enclosures. Suppliers hedge by offering interchangeable fittings that serve both glycol-water and new dielectric formulations. This flexibility positions them to capture value as OEMs iterate battery strategies over the decade.
Passenger cars accounted for 62.84% of the market size in 2025 because of their sheer production volume across global assembly lines. Nevertheless, medium and heavy commercial vehicles are forecasted to record a 4.73% CAGR as depot charging, telematics, and stricter emissions rules collide. Fleets retrofitting diesel trucks with selective catalytic reduction and particulate filter plumbing provide an immediate aftermarket lift. In parallel, long-haul electric trucks require dielectric quick-connects rated for megawatt-class charging, opening a premium niche for high-spec connectors. These factors together explain why commercial platforms, though numerically smaller than cars, command growing engineering attention.
Urban logistics growth adds another layer of complexity. Light commercial vans toggle between internal-combustion and battery-electric powertrains depending on duty cycle, so their fluid architectures must support both low-viscosity oils and sophisticated coolant loops. Bus operators in Asia and Europe are adopting hydrogen or battery solutions for zero-emission zones, requiring 700-bar hydrogen lines and stack coolers. Component makers that can tailor hose assemblies for vibration, road-salt exposure, and 24-hour duty cycles gain an edge with fleet buyers. This service-orientation differentiates them from car-centric competitors focused mainly on launch-year volume.
Complete Report Scope:
- By System Type
- Fuel Transfer Systems
- Oil Transfer Systems
- Brake Fluid Systems
- Transmission Fluid Systems
- Coolant Transfer Systems
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Medium and Heavy Commercial Vehicles (M&HCVs)
- Buses and Coaches
- By Propulsion Type
- Internal Combustion Engine (ICE)
- Battery Electric Vehicle (BEV)
- Plug-in Hybrid Electric Vehicle (PHEV)
- Hybrid Electric Vehicle (HEV)
- Fuel-Cell Electric Vehicle (FCEV)
- By Component Type
- Hoses
- Tubing
- Connectors
- Clamps
- Reservoirs
- Pumps
- Others
- By Distribution Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific led the automotive fluid transfer system market with 48.87% revenue in 2025. China's January 2026 GB standards hard-wire thermal management, ensuring continuous demand for low-permeation coolant and DEF lines. India's April 2026 BS-VII launch compels retrofits of DPF and SCR hoses across freight fleets. Japan and South Korea prioritize hydrogen bus corridors, generating early orders for 700-bar fuel lines. Tier-1 firms cluster extrusion and compounding plants near resin suppliers, curbing freight costs and import duties.
North America is forecasted to clock the swiftest 4.17% CAGR through 2031. The U.S. EPA's 2025 heavy-duty inducement rules trigger fleet-wide upgrades of DEF plumbing. Megawatt charging pilots along interstate corridors accelerate demand for dielectric quick-connects capable of gigawatt-class pulse loads. Canada's ZEV mandate pushes OEMs to localize battery-thermal supply chains, while Mexico's cost-competitive plants absorb reshored hose programs freed from Asian tariffs.
Europe faces an ICE phase-out debate, but Euro 7's July 2025 milestones anchor near-term fluid-line upgrades. Heated urea circuits and 200,000-km durability thresholds lift specification floors. Germany remains a production hub, exporting multilayer nylon-aluminum brake tubing to global platforms. The United Kingdom aligns with Euro 7 from November 2026 onward, extending compliant component demand across the continent.
- Cooper-Standard Holdings Inc.
- TI Automotive (TI Fluid Systems)
- Continental AG (ContiTech)
- Gates Corporation
- Kongsberg Automotive
- Akwel Group
- Hutchinson SA
- Tristone Flowtech
- Lander Automotive
- Castello Italia
- Parker Hannifin Corporation
- Sanoh Industrial Co., Ltd.
- Delfingen
- Eaton Corporation
- Kuriyama Holdings Corporation
- Transfer Oil S.p.A.
- Toyoda Gosei
- Manuli Hydraulics
- Trelleborg AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid BEV/HEV Sales Growth Creating Multi-Loop Thermal-Management Fluid Circuits
- 4.2.2 Tightening Emission and Fuel-Economy Norms Accelerating Adoption of DPF/SCR Fluid Lines
- 4.2.3 Turbo-GDI Engine Proliferation Raising Demand for High-Temperature Oil and Coolant Lines
- 4.2.4 Smart Hoses With Embedded Fluid-Quality Sensors Enabling Predictive Maintenance
- 4.2.5 Laser-Welded Multilayer Nylon-Aluminum Brake Tubing Enabling 30% Weight Reduction
- 4.2.6 Megawatt Depot Charging for Electric Trucks Driving Dielectric-Coolant Quick-Connect Systems
- 4.3 Market Restraints
- 4.3.1 ICE Phase-Out Targets Curbing Long-Term Demand for Fuel and Oil Transfer Lines
- 4.3.2 Volatile PA-12 Supply Inflating High-Performance Polymer Costs
- 4.3.3 Low Replacement Rate Limiting Aftermarket Revenue
- 4.3.4 Direct-Immersion Battery Cooling Eliminating Discrete Coolant Hoses in Next-Gen EVs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By System Type
- 5.1.1 Fuel Transfer Systems
- 5.1.2 Oil Transfer Systems
- 5.1.3 Brake Fluid Systems
- 5.1.4 Transmission Fluid Systems
- 5.1.5 Coolant Transfer Systems
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles (LCVs)
- 5.2.3 Medium and Heavy Commercial Vehicles (M&HCVs)
- 5.2.4 Buses and Coaches
- 5.3 By Propulsion Type
- 5.3.1 Internal Combustion Engine (ICE)
- 5.3.2 Battery Electric Vehicle (BEV)
- 5.3.3 Plug-in Hybrid Electric Vehicle (PHEV)
- 5.3.4 Hybrid Electric Vehicle (HEV)
- 5.3.5 Fuel-Cell Electric Vehicle (FCEV)
- 5.4 By Component Type
- 5.4.1 Hoses
- 5.4.2 Tubing
- 5.4.3 Connectors
- 5.4.4 Clamps
- 5.4.5 Reservoirs
- 5.4.6 Pumps
- 5.4.7 Others
- 5.5 By Distribution Channel
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 Spain
- 5.6.3.4 Italy
- 5.6.3.5 France
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 India
- 5.6.4.2 China
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Egypt
- 5.6.5.5 South Africa
- 5.6.5.6 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Cooper-Standard Holdings Inc.
- 6.4.2 TI Automotive (TI Fluid Systems)
- 6.4.3 Continental AG (ContiTech)
- 6.4.4 Gates Corporation
- 6.4.5 Kongsberg Automotive
- 6.4.6 Akwel Group
- 6.4.7 Hutchinson SA
- 6.4.8 Tristone Flowtech
- 6.4.9 Lander Automotive
- 6.4.10 Castello Italia
- 6.4.11 Parker Hannifin Corporation
- 6.4.12 Sanoh Industrial Co., Ltd.
- 6.4.13 Delfingen
- 6.4.14 Eaton Corporation
- 6.4.15 Kuriyama Holdings Corporation
- 6.4.16 Transfer Oil S.p.A.
- 6.4.17 Toyoda Gosei
- 6.4.18 Manuli Hydraulics
- 6.4.19 Trelleborg AB
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

