PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117466

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117466
Autonomous Construction Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2025 - 2030)
According to Mordor Intelligence, the autonomous construction equipment market size stood at USD 5.31 billion in 2025 and is forecast to climb to USD 9.49 billion by 2030, advancing at a 12.32% CAGR.
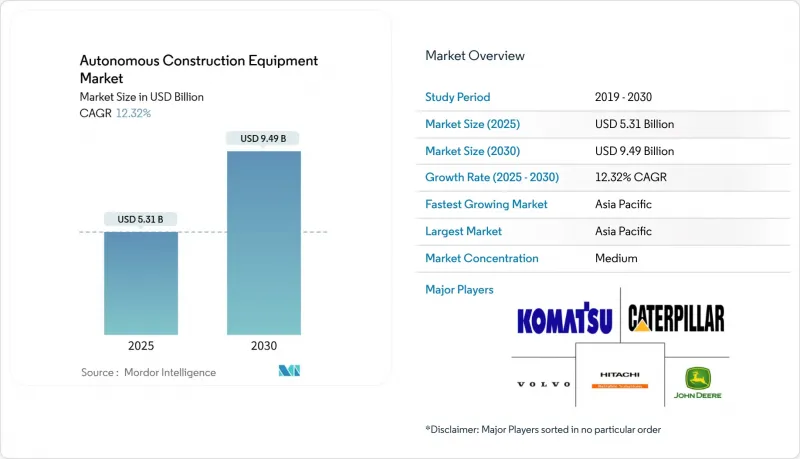
This report is Segmented by Level of Automation (Semi-Autonomous and Fully Autonomous), Equipment Type (Earthmoving and More), Propulsion Type (Internal Combustion and More), Equipment Size (Heavy (Above 11 T) and More), Power Output (Up To 250 HP and More), Application, Sales Channel, and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Autonomous Construction Equipment Market Trends and Insights
Labor-shortage Driven ROI Focus on Automation
Construction faces a projected 2.2 million-worker gap by 2026 in North America, elevating unmanned systems from optional upgrades to business-continuity necessities. Contractors deploying autonomous excavators cut reliance on two to three operators per shift and avoid overtime premiums. Continuous 24/7 operation improves asset utilization and compresses project timelines, enhancing bid competitiveness. Insurance savings accrue as exposure to work-site accidents falls. Compliance with updated ANSI B11 and UL 4600 standards boosts confidence among risk-averse project owners.
OEM Retrofit Kits Slashing Capital Outlay
Retrofit autonomy packages cut implementation costs 40-60% compared with new equipment purchases. Trimble-ready hardware on Liebherr PR 776 dozers illustrates factory-integrated mounting points that preserve warranties and speed field activation. Rental fleets value machine-agnostic 3D control systems that travel across brands, avoiding vendor lock-in. Lower upfront spend hastens technology trials by small contractors. Retrofit pathways also extend the service life of mixed fleets, smoothing the transition toward fully autonomous deployments in the autonomous construction equipment market.
Fragmented Job-site Topography Limiting GNSS/LiDAR Reliability
Urban reconstruction and multi-level excavations produce obstructed signals that diminish autonomous positioning accuracy. Liebherr's GPS-independent wheel loader uses 3D environmental sensing to navigate in tunnels where satellite access fails. Dynamic terrain changes force real-time map updates that tax onboard processing. Defense-grade sensor fusion offers a workaround yet raises system cost, inhibiting widespread use beyond premium projects.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Battery-cost Decline Enabling Electrification
- AI-enabled Multi-machine Orchestration
- Unharmonized Safety Regulations Across Jurisdictions Delaying Approvals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Semi-autonomous machines delivered 69.75% of 2024 revenue as contractors favored operator-assisted functions for immediate productivity gains with limited risk. Fully autonomous systems, however, are forecast to capture the fastest 17.83% CAGR as regulatory clarity improves and early pilots prove reliability. Integrated command platforms now let a single supervisor oversee multiple unmanned assets, compressing labor budgets. These gains align with owner demands for shorter schedules and predictable costs.
The fully autonomous cohort benefits from advances in perception sensors and fail-safe architectures that meet ANSI B11 safety requirements. Caterpillar's MineStar Command demonstrates scalable autonomy migrating from iron-ore mines to aggregates quarries. Early adopters report extended duty cycles and reduced idle fuel burn. Adoption barriers center on upfront integration complexity and the training required for remote supervisors rather than equipment operators.
Earthmoving equipment retained 47.18% market share in 2024 owing to entrenched autonomous haulage systems and motor graders across mining and highway projects. Compact tools, conversely, will post a 13.42% CAGR as autonomy penetrates skid steers, plate compactors, and material handlers popular on urban and utilities work sites. These smaller assets excel in confined areas where large machinery cannot maneuver, reducing rework and traffic disruption. Expanding model availability from mainstream OEMs keeps upfront prices in check, drawing interest from midsized contractors that lack mega-project budgets.
The autonomous construction equipment market size for compact tools remains modest yet accelerates as retrofit kits become brand-agnostic and easier to finance. Multi-machine site concepts already showcase coordinated tasks among mini-excavators, robotic track loaders, and automated compactors. Broader accessibility rests on streamlined safety certification and dealer support capable of servicing mixed fleets. Increased rental availability further lowers entry barriers by bundling maintenance, software updates, and operator onboarding.
Internal-combustion engines held 74.36% share in 2024, but battery-electric units are projected to surge at a 19.26% CAGR on the back of emissions mandates and total-cost savings. The autonomous construction equipment market share attributable to battery-electric machines improves yearly as public-private charging infrastructure spreads and batteries hit sub-USD 70/kWh pricing. Electric drivetrains deliver instant torque and precise speed modulation that simplify algorithmic control loops, making them a natural partner for autonomy. Rising diesel costs and corporate decarbonization pledges add financial impetus to conversion programs.
Instant torque enables smoother path-following, while regenerative braking extends runtime and trims maintenance cycles compared with diesel hydraulics. Hydrogen fuel-cell trials progress in heavy wheel loaders where battery mass proves restrictive, though commercialization remains several years away. Hybrid hydraulic systems serve as an interim step, allowing mixed fuel and electric operation during the infrastructure transition. Collectively, these propulsion options widen the technology toolkit available to fleet planners facing varied duty cycles and site constraints.
Complete Report Scope:
- By Level of Automation
- Semi-Autonomous
- Fully Autonomous
- By Equipment Type
- Earthmoving
- Material Handling
- Concrete and Road Machinery
- Light / Compact Tools
- By Propulsion Type
- Internal Combustion
- Hybrid Hydraulic
- Battery-Electric
- Hydrogen Fuel-Cell
- By Equipment Size
- Heavy (Above 11 t)
- Medium (6 to 11 t)
- Compact (Below 6 t)
- By Power Output
- Up to 250 HP
- 250 to 500 HP
- Above 500 HP
- By Application
- Infrastructure
- Residential and Commercial Construction
- Mining and Quarrying
- Oil and Gas / Pipelines
- Industrial and Manufacturing
- By Sales Channel
- New Equipment
- Rental
- Used / Refurbished
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Nigeria
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific dominated the autonomous construction equipment market with 45.13% revenue in 2024, anchored by China's battery-swap excavators, Japan's precision sensors, and South Korea's electronics supply chain. Regional governments finance smart-city and high-speed rail projects that mandate productivity gains and emissions cuts. However, the 12.51% regional CAGR trails the region's pace because adoption saturates quickly in mature sub-sectors. Divergent national standards add compliance overhead and slow pan-regional fleet sharing.
North America's 12.42% CAGR arises from critical skilled-labor shortages and clearer safety frameworks. U.S. states such as Nevada permit live site testing, accelerating commercialization cycles. Federal infrastructure funding includes carbon-reduction scoring, nudging public contractors toward electric-autonomous packages. Canada's tender evaluations already award points for zero-operator equipment, making autonomy a differentiator on mega-projects. Supply-chain resilience initiatives also drive local manufacturing of battery packs and sensor modules.
Europe is projected to post a robust CAGR, driven by Green Public Procurement rules that factor whole-life carbon into bid scoring. Nations like the Netherlands use CO2 Performance Ladder incentives to reward low-emission job sites, pushing contractors to integrate electric-autonomous fleets. Fragmented safety certification across EU states complicates cross-border deployments, but ISO-aligned guidance is tightening. Early electrification pilots in cities such as Eindhoven validate emission-free autonomous diggers on municipal works, setting templates for broader rollouts.
- Caterpillar Inc.
- Komatsu Ltd.
- Deere & Company
- Volvo Construction Equipment
- Hitachi Construction Machinery
- Liebherr Group
- CNH Industrial
- JCB Ltd.
- DEVELON (HD Hyundai Infracore)
- Hyundai Construction Equipment
- Wirtgen Group
- Bobcat Company
- Sandvik AB
- Epiroc AB
- Trimble Inc.
- Topcon Corp.
- Built Robotics
- SafeAI
- Autonomous Solutions Inc. (ASI)
- XCMG
- Sany Heavy Industry
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Labor-shortage Driven ROI Focus on Automation
- 4.2.2 OEM Retrofit Kits Slashing Cap-ex vs. New Buys (After-market Autonomy)
- 4.2.3 Rapid Battery-cost Decline Enabling Heavy Equipment Electrification
- 4.2.4 Carbon-linked Project Tender Scores in Europe and Canada Favouring Zero-operator Sites
- 4.2.5 AI-enabled Multi-machine Fleet Orchestration Boosts Productivity 25 to 30%
- 4.2.6 Defence-funded Sensor Fusion Spilling Over to Construction OEMs
- 4.3 Market Restraints
- 4.3.1 Fragmented Job-site Topography Limiting GNSS/LiDAR Reliability
- 4.3.2 Unharmonized Safety Regulations Across US-States/EU-27 Delaying Approvals
- 4.3.3 Data-ownership Disputes Between EPCs, OEMs and Tech Suppliers
- 4.3.4 Scarcity of High-capacity, Ruggedised Battery Packs (Over 600 kWh) Until 2026
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Level of Automation
- 5.1.1 Semi-Autonomous
- 5.1.2 Fully Autonomous
- 5.2 By Equipment Type
- 5.2.1 Earthmoving
- 5.2.2 Material Handling
- 5.2.3 Concrete and Road Machinery
- 5.2.4 Light / Compact Tools
- 5.3 By Propulsion Type
- 5.3.1 Internal Combustion
- 5.3.2 Hybrid Hydraulic
- 5.3.3 Battery-Electric
- 5.3.4 Hydrogen Fuel-Cell
- 5.4 By Equipment Size
- 5.4.1 Heavy (Above 11 t)
- 5.4.2 Medium (6 to 11 t)
- 5.4.3 Compact (Below 6 t)
- 5.5 By Power Output
- 5.5.1 Up to 250 HP
- 5.5.2 250 to 500 HP
- 5.5.3 Above 500 HP
- 5.6 By Application
- 5.6.1 Infrastructure
- 5.6.2 Residential and Commercial Construction
- 5.6.3 Mining and Quarrying
- 5.6.4 Oil and Gas / Pipelines
- 5.6.5 Industrial and Manufacturing
- 5.7 By Sales Channel
- 5.7.1 New Equipment
- 5.7.2 Rental
- 5.7.3 Used / Refurbished
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Rest of North America
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 United Kingdom
- 5.8.3.3 France
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.3.6 Sweden
- 5.8.3.7 Rest of Europe
- 5.8.4 Asia-Pacific
- 5.8.4.1 China
- 5.8.4.2 India
- 5.8.4.3 Japan
- 5.8.4.4 South Korea
- 5.8.4.5 Indonesia
- 5.8.4.6 Rest of Asia-Pacific
- 5.8.5 Middle East and Africa
- 5.8.5.1 Saudi Arabia
- 5.8.5.2 United Arab Emirates
- 5.8.5.3 Turkey
- 5.8.5.4 South Africa
- 5.8.5.5 Nigeria
- 5.8.5.6 Egypt
- 5.8.5.7 Rest of Middle East and Africa
- 5.8.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 Deere & Company
- 6.4.4 Volvo Construction Equipment
- 6.4.5 Hitachi Construction Machinery
- 6.4.6 Liebherr Group
- 6.4.7 CNH Industrial
- 6.4.8 JCB Ltd.
- 6.4.9 DEVELON (HD Hyundai Infracore)
- 6.4.10 Hyundai Construction Equipment
- 6.4.11 Wirtgen Group
- 6.4.12 Bobcat Company
- 6.4.13 Sandvik AB
- 6.4.14 Epiroc AB
- 6.4.15 Trimble Inc.
- 6.4.16 Topcon Corp.
- 6.4.17 Built Robotics
- 6.4.18 SafeAI
- 6.4.19 Autonomous Solutions Inc. (ASI)
- 6.4.20 XCMG
- 6.4.21 Sany Heavy Industry
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

