PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117495

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117495
Rayon Fibers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the rayon fibers market size is expected to increase from USD 22.17 billion in 2025 to USD 23.65 billion in 2026 and reach USD 32.52 billion by 2031, and is expected to grow at a CAGR of 6.58% over 2026-2031.
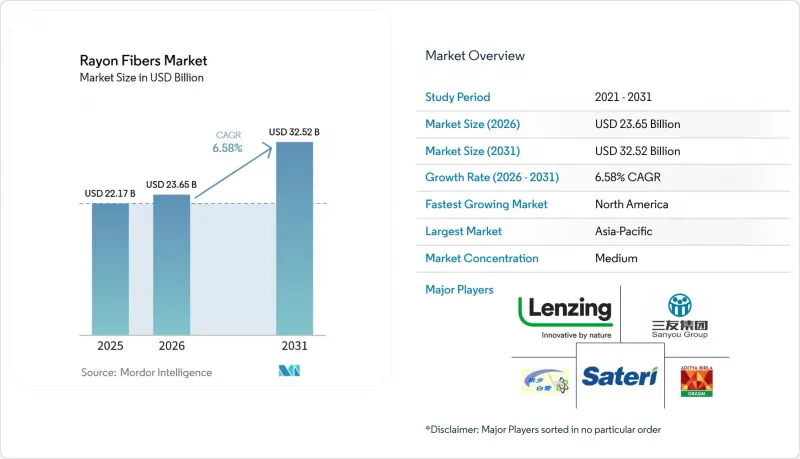
This report is Segmented by Product Type (Viscose Rayon, Lyocell, and More), Fiber Form (Staple Fiber and Filament Fiber), Application (Apparel, Home Textiles, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Rayon Fibers Market Trends and Insights
Rising Demand for Sustainable and Biodegradable Fibers
The rayon fibers market is benefiting from greater buyer focus on fiber biodegradability and reduced dependence on fossil-derived materials. Concerns over synthetic microplastic contamination are prompting sustainability teams to incorporate fiber selection into formal sourcing standards, rather than treating it as a voluntary brand commitment. The market is also seeing a clearer distinction between conventional viscose and closed-loop lyocell, as buyers now evaluate chemical intensity and solvent recovery as separate criteria rather than grouping all regenerated cellulosics together. Birla Cellulose's Livaeco Lyocell, with up to 99.7% solvent recovery and 100% Forest Stewardship Council (FSC)-certified wood pulp, illustrates how closed-loop processing and documented sourcing are becoming purchasing criteria for premium cellulosics. As procurement standards tighten, this demand pattern is extending beyond apparel into home textiles and hygiene applications, where traceable raw materials are increasingly important.
Expansion of Lyocell and Modal Fiber Production Capacity
The rayon fibers market is shifting as lyocell production moves from specialty-scale output to larger, more standardized volumes. Global lyocell capacity exceeded 1.3 million tons by 2025, and Sateri's lyocell capacity reached 600,000 metric tons across four sites in 2026 following the start of production at its Yutai facility in Shandong province. Grasim Industries Limited operates 890,000 tons per annum (TPA) of cellulosic staple fiber at 97% utilization in fiscal year 2026 and has approved a Phase II lyocell expansion at Harihar for INR 3,094 crore (USD 324 million), building toward 210,000 TPA of total lyocell capacity upon completion of Phase I and Phase II. This shift is expected to result in lower unit costs and broader adoption in mid-market apparel categories that had previously considered lyocell too expensive. Modal is also expected to benefit, as buyers increasingly apply tiered sourcing policies that place viscose, modal, and lyocell on a defined scale of cost and sustainability performance.
Carbon Disulfide and Effluent Compliance Raising Production Costs
The rayon fibers market faces a cost challenge in conventional viscose production, as CS2 recovery and sulfur-related treatment systems require sustained investment. The U.S. Environmental Protection Agency regulates effluent discharge from viscose rayon plants under the Organic Chemicals, Plastics, and Synthetic Fibers Effluent Guidelines, keeping pollution control closely tied to plant economics. Asia Pacific Rayon's 2025 EU Best Available Techniques (BAT) Assessment Report showed that advanced abatement systems can reduce sulfur-to-air emissions below 20 kg per ton of fiber to meet EU BAT benchmarks, but this level of control requires capital that not every mid-scale producer can sustain. The rayon fibers market also recorded a notable development in Europe when Kelheim Fibres closed operations as of March 31, 2026, after insolvency proceedings failed to secure a viable long-term solution. The Zero Discharge of Hazardous Chemicals (ZDHC) MMCF Guidelines broaden compliance expectations across regenerated cellulose value chains, meaning cost pressure is no longer limited to a narrow group of viscose producers.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Eco-Friendly Fashion Initiatives
- Increasing Use of Regenerated Cellulose Fibers Across Sectors
- Environmental Regulations Governing Viscose Production Methods
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Viscose rayon held 67.38% of the rayon fibers market share in 2025, reflecting its low-cost position, the scale of wet-spinning processes, and wide compatibility with standard spinning and finishing equipment across Asian textile hubs. The rayon fibers market continues to rely on viscose as the volume base because it aligns better with the economics of mass apparel and home textiles than higher-priced regenerated cellulosics. Modal occupied a middle tier between commodity viscose and premium lyocell, with its softer hand-feel and higher moisture absorption supporting use in intimate apparel, sportswear, and premium bedding. Lyocell was the fastest-growing product type, with an 8.52% CAGR through 2031, supported by brand sustainability requirements, the appeal of its closed-loop process, and a narrowing cost gap with viscose as new capacity comes online.
Cuprammonium rayon retained a niche role, mainly in the Japanese luxury apparel segment, where ultra-fine filament characteristics support silk-like drape and surface finish. High tenacity rayon and super high tenacity rayon remained tied to industrial uses such as tire cord reinforcement, industrial belting, and filtration fabrics, where tensile performance and thermal stability matter more than softness. The rayon fibers market is separating more clearly between a large viscose base that supports scale and a smaller lyocell segment that is capturing premium growth. Birla Cellulose's Livaeco Lyocell, made with up to 99.7% solvent recovery and 100% Forest Stewardship Council (FSC)-certified wood pulp, raises the sustainability benchmark that product portfolios in the rayon fibers market increasingly need to meet.
Complete Report Scope:
- By Product Type
- Viscose Rayon
- Modal Rayon
- Lyocell
- Cuprammonium Rayon
- High Tenacity Rayon
- Super High Tenacity Rayon
- Other Product Types
- By Fiber Form
- Staple Fiber
- Filament Fiber
- By Application
- Apparel
- Home Textiles
- Industrial Textiles
- Medical Textiles
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 62.44% of the global rayon fibers market in 2025, making it the largest region for both production and consumption. China remained the largest single production base, with Tangshan Sanyou, Sateri, and Yibin Grace Group operating at multi-hundred-thousand-ton annual scales. India also played a notable role, as Grasim Industries operated 890,000 tons per annum (TPA) of cellulosic staple fiber at 97% utilization in fiscal year 2026, indicating strong demand and limited spare capacity. Japan remained smaller in volume but relevant in specialty filament and cuprammonium applications tied to luxury apparel and fine drape. South Korea contributed downstream spinning capacity, while Vietnam, Bangladesh, and Indonesia continued to absorb greater volumes of Chinese and Indian fiber through garment assembly networks.
North America is projected to grow at a 7.13% CAGR through 2031, making it the fastest-growing region in the rayon fibers market. Growth is driven less by large domestic fiber output and more by sourcing shifts toward certified sustainable cellulosics. Lenzing's 2025 launch of VEOCEL lyocell-based hygiene products in North America with Edgewell Personal Care demonstrated that premium nonwovens can enter categories long dominated by fossil-derived materials. Mexico is also becoming more relevant, as nearshoring under the United States-Mexico-Canada Agreement (USMCA) framework supports rayon-based garment assembly for U.S. brands seeking shorter supply chains.
Europe represented a meaningful share of global rayon fiber demand in 2025, with the market shaped by fashion, hygiene nonwovens, and sustainability compliance requirements. The EU textiles policy agenda is directing brand procurement toward certified cellulosic fibers with stronger traceability and process documentation. Germany and the United Kingdom remained the largest national markets in Europe, combining strong textile demand with concentrated fashion retail activity. South America, led by Brazil and Argentina, remains a smaller market but is building demand through urbanization and investment in textile manufacturing. The Middle East and Africa also remain early-stage targets for Asian exporters seeking to diversify beyond established intra-Asia trade routes.
- Asia Pacific Rayon Limited
- Bohi Industry
- CHTC Helon
- Grasim Industries Limited
- Kelheim Fibres GmbH
- Lenzing AG
- Sateri
- Tangshan Sanyou Group Xingda Chemical Fibre Co., Ltd.
- Xinxiang Bailu Chemical Fibre Group Co., Ltd.
- Yibin Grace Group
- Yibin Grace Group
- Zhejiang Fulida Holding Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for sustainable and biodegradable fibers
- 4.2.2 Increasing consumption in apparel and home textiles
- 4.2.3 Expansion of lyocell and modal fiber production
- 4.2.4 Growth of eco-friendly fashion initiatives
- 4.2.5 Increasing use of regenerated cellulose fibers as alternatives to synthetic fibers
- 4.3 Market Restraints
- 4.3.1 Carbon Disulfide And Effluent Compliance Raise Operating Costs
- 4.3.2 Environmental regulations governing viscose production
- 4.3.3 High capital investment for advanced lyocell manufacturing
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Viscose Rayon
- 5.1.2 Modal Rayon
- 5.1.3 Lyocell
- 5.1.4 Cuprammonium Rayon
- 5.1.5 High Tenacity Rayon
- 5.1.6 Super High Tenacity Rayon
- 5.1.7 Other Product Types
- 5.2 By Fiber Form
- 5.2.1 Staple Fiber
- 5.2.2 Filament Fiber
- 5.3 By Application
- 5.3.1 Apparel
- 5.3.2 Home Textiles
- 5.3.3 Industrial Textiles
- 5.3.4 Medical Textiles
- 5.3.5 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Asia Pacific Rayon Limited
- 6.4.2 Bohi Industry
- 6.4.3 CHTC Helon
- 6.4.4 Grasim Industries Limited
- 6.4.5 Kelheim Fibres GmbH
- 6.4.6 Lenzing AG
- 6.4.7 Sateri
- 6.4.8 Tangshan Sanyou Group Xingda Chemical Fibre Co., Ltd.
- 6.4.9 Xinxiang Bailu Chemical Fibre Group Co., Ltd.
- 6.4.10 Yibin Grace Group
- 6.4.11 Yibin Grace Group
- 6.4.12 Zhejiang Fulida Holding Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

