PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117503

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117503
Cellular Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the cellular glass market size is projected to be USD 2.07 billion in 2025, USD 2.14 billion in 2026, and reach USD 2.84 billion by 2031, and is expected to grow at a CAGR of 5.82% from 2026 to 2031.
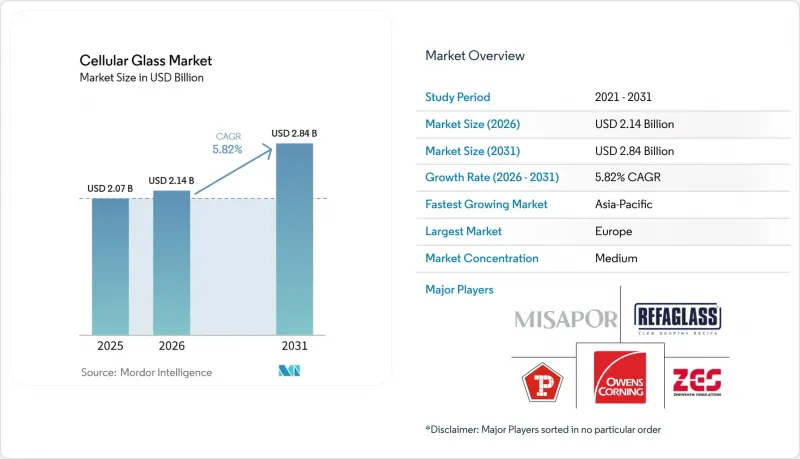
This report is Segmented by Product Type (Blocks and Shells and Foam Glass Gravels), Application (Industrial Insulation, Building and Construction, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Cellular Glass Market Trends and Insights
Rising Demand for Fire-Resistant Insulation Materials
Fire performance is a key reason the cellular glass market continues to gain specification support in regulated construction environments. Cellular glass is classified as A1 non-combustible under EN 13501-1, placing it among a narrow group of insulation materials that can meet strict fire requirements without additional chemical treatment or fire-retardant systems. Project teams in the United States, Europe, and other major building markets are giving greater attention to facade and assembly fire performance during early design review. Once a project fire strategy requires a non-combustible solution, substitution risk decreases because many polymer-based alternatives no longer qualify on equal terms. This pattern is supporting the cellular glass market in commercial buildings, industrial plants, and dense urban projects where code compliance and long-term risk management carry more weight than lower upfront insulation costs.
Increasing Adoption in Green Building and Net-Zero Construction Projects
Green building frameworks are providing the cellular glass market with a steady source of demand, as material selection now carries greater weight in certification-led commercial projects. Cellular glass suits these projects because it is commonly produced from waste glass cullet and avoids petrochemicals, blowing agents, and volatile organic compounds in the finished material profile. GLAVEL strengthened this position with third-party-verified environmental documentation for foamed glass aggregate and a Declare label, giving architects clearer lifecycle and material health information during specification. Certifying architects often influence insulation choices in premium commercial projects before contractors compare installed bids. As a result, the cellular glass market is gaining traction in projects where transparent material documentation, recycled content, and indoor environmental quality carry procurement value.
Higher Initial Cost Compared to Conventional Insulation Alternatives
High upfront cost remains a key commercial restraint on the cellular glass market. The manufacturing process relies on energy-intensive glass melting and tightly controlled foaming cycles, which keep delivered costs above those of mineral wool, expanded polystyrene, and polyisocyanurate in many project comparisons. This is most relevant in residential and light commercial construction, where buyers typically compare materials on initial installed cost per unit area rather than total service-life economics. Price sensitivity is high in South America, Southeast Asia, and parts of Eastern Europe, where local production capacity is also limited. As a result, the cellular glass market in these regions remains concentrated in industrial plants and high-value commercial projects, where buyers are more willing to pay for moisture resistance, fire safety, and long service life.
Other drivers and restraints analyzed in the detailed report include:
- Growing Preference for Sustainable and Energy-Efficient Building Solutions
- Increasing Retrofit and Renovation Activities in Mature-Market Building Stock
- Fragility and Risk of Mechanical Damage During Transportation and Installation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Blocks and Shells held 58.72% of the cellular glass market share in 2025, reflecting the central role of formed products in the cellular glass market. Their market position stems from flat-roof systems, below-grade waterproofing, and industrial insulation for pipes, tanks, and equipment, where pre-shaped geometry reduces field cutting and allows for more controlled installation. This advantage is particularly relevant in cryogenic projects, as storage tanks and transfer systems require dimensional stability under repeated thermal cycling between ambient and sub-zero service conditions. Blocks and Shells are also well established in specifications that prioritize fire performance, moisture resistance, and long service life.
Foam Glass Gravels are projected to grow at a 6.73% CAGR through 2031, making this the fastest-growing product form in the cellular glass market. Growth is driven by sub-slab insulation, road embankments, frost-heave mitigation, and civil works, where the loose aggregate format combines drainage, insulation, and lightweight fill in a single layer. This opens the cellular glass market to civil engineering and infrastructure buyers that historically did not source traditional insulation products. GLAVEL's Environmental Product Declaration stated that its foam glass gravel, produced from 100% post-consumer recycled glass using renewable energy, carried 55% lower embodied carbon than conventional foam board assemblies. Foamit Group also expanded its facility in Forssa in late 2025, increasing small-grain cellular glass production capacity to above 100,000 cubic meters annually.
Complete Report Scope:
- By Product Type
- Blocks and Shells
- Foam Glass Gravels
- By Application
- Building and Construction
- Industrial Insulation
- Chemical and Petrochemical
- Oil & Gas
- Energy & Power
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Europe held 36.92% of the cellular glass market share in 2025, maintaining its leading position. This is supported by strict energy codes, a well-established manufacturing base, and a renovation cycle that favors materials with reliable thermal and moisture performance. Germany, France, and the United Kingdom remain the main demand centers. Germany stands out in particular, as financing support and high-performance building standards have created a durable premium segment for foundation and flat-roof insulation. The Energy Performance of Buildings Directive (EPBD) requirement for national renovation plans by December 2026 further strengthens the regional market by converting a larger portion of the existing building stock into a regulated demand pool rather than a discretionary one. Owens Corning's June 2025 investment announcement for its FOAMGLAS plant in Klasterec, Czech Republic, which targets a 50% increase in production capacity with commissioning in Q2 2026, reflects how suppliers are positioning for continued European demand in the cellular glass market.
Asia-Pacific is projected to grow at a CAGR of 6.52% through 2031, making it the fastest-growing regional market for cellular glass. China, India, South Korea, and Japan are driving this growth through a combination of LNG import infrastructure expansion, industrial insulation requirements, and commercial construction activity. China and India are significant markets, as regasification terminal additions are directly increasing demand for cryogenic storage tank insulation, transfer piping insulation, and related low-temperature equipment. Japan and South Korea add further demand through hydrogen infrastructure plans and shipbuilding-linked LNG activity, broadening the industrial use base beyond standard commercial construction.
South America, the Middle East, and Africa remain smaller regional markets for cellular glass. Demand in these regions is tied to petrochemical, LPG, LNG, and major infrastructure investment rather than routine building activity alone. Brazil and Argentina lead South American demand, though price sensitivity and limited local production keep the region dependent on imports, which increase the landed cost of an already premium material. In the Middle East and Africa, Saudi Arabia is a notable market as Vision 2030 projects and energy-efficient construction requirements are driving demand for durable thermal materials with proven long-term performance. The UAE also supports regional demand through LNG and petrochemical expansion, with industrial insulation remaining the primary entry point for broader adoption.
- Anhui Huichang New Material Co., Ltd.
- Earthstone International LLC
- GEOCELL Schaumglas GmbH
- Glapor Werk Mitterteich GmbH
- GLAVEL, Inc.
- Jahan Ayeg Pars Company
- Liaver GmbH and Co. KG
- MISAPOR
- Owens Corning
- POLYDROS,S.A.
- REFAGLASS s.r.o.
- Steinbach Schaumglas GmbH and Co. KG
- STES-Vladimir
- Uusioaines Oy
- Zhejiang Dehe Insulation Technology Co., Ltd.
- ZHEJIANG ZHENSHEN INSULATION TECHNOLOGY CORP.LTD.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Fire-Resistant and High-Performance Thermal Insulation
- 4.2.2 Increasing Adoption in Cryogenic and Low-Temperature Applications
- 4.2.3 Growing Preference for Sustainable and Recyclable Insulation Materials
- 4.2.4 Increasing Retrofit and Renovation Activities Across Industrial and Commercial Buildings
- 4.2.5 Rising Demand for Moisture-Resistant Insulation in High-Humidity Environments
- 4.3 Market Restraints
- 4.3.1 Higher Initial Cost Compared to Conventional Insulation Materials
- 4.3.2 Limited Awareness and Adoption Among Small and Medium-Sized Contractors
- 4.3.3 Fragility and Risk of Damage During Transportation and Installation
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Blocks and Shells
- 5.1.2 Foam Glass Gravels
- 5.2 By Application
- 5.2.1 Building and Construction
- 5.2.2 Industrial Insulation
- 5.2.3 Chemical and Petrochemical
- 5.2.4 Oil & Gas
- 5.2.5 Energy & Power
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Russia
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Anhui Huichang New Material Co., Ltd.
- 6.4.2 Earthstone International LLC
- 6.4.3 GEOCELL Schaumglas GmbH
- 6.4.4 Glapor Werk Mitterteich GmbH
- 6.4.5 GLAVEL, Inc.
- 6.4.6 Jahan Ayeg Pars Company
- 6.4.7 Liaver GmbH and Co. KG
- 6.4.8 MISAPOR
- 6.4.9 Owens Corning
- 6.4.10 POLYDROS,S.A.
- 6.4.11 REFAGLASS s.r.o.
- 6.4.12 Steinbach Schaumglas GmbH and Co. KG
- 6.4.13 STES-Vladimir
- 6.4.14 Uusioaines Oy
- 6.4.15 Zhejiang Dehe Insulation Technology Co., Ltd.
- 6.4.16 ZHEJIANG ZHENSHEN INSULATION TECHNOLOGY CORP.LTD.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

