PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118875

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118875
Medical Ceramics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the medical ceramics market size was valued at USD 19.62 billion in 2025 and is estimated to grow from USD 20.95 billion in 2026 to reach USD 28.91 billion by 2031, at a CAGR of 6.65% during the forecast period (2026-2031).
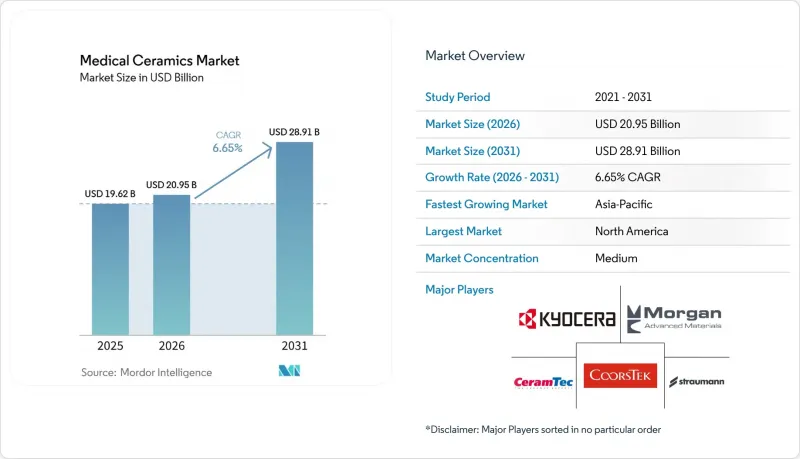
This report is Segmented by Material (Bioinert Ceramics, Bioactive Ceramics, and More), Application (Dental, Orthopedic, Cardiovascular, and Plastic Surgery), End-User Industry (Hospitals and Clinics, Ambulatory Surgical Centers, Specialty Centers), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Ceramics Market Trends and Insights
Increasing Demand for Orthopedic and Dental Ceramic Implants
Demand for orthopedic and dental ceramic implants is driven by factors beyond population aging. Joint replacement and dental procedures require materials with established clinical performance in demanding applications. Ceramic bearing systems and dental restorations remain relevant where wear resistance and biocompatibility influence treatment choices. The medical ceramics market also benefits when lower procedure costs broaden patient access for those who previously deferred treatment. Reimbursement and procurement policies affect whether hospitals select ceramic components or competing materials. This combination of procedure volume, payment structures, and clinical requirements supports sustained demand across orthopedic and dental care in the medical ceramics market.
Growing Adoption of Patient-Specific Ceramic Implants Through Advanced Manufacturing Technologies
Patient-specific ceramic implants are moving beyond a narrow premium use case as digital design and manufacturing workflows develop. Tampere University reported in 2025 that 3D-printed bioceramic scaffolds with 400-micrometer pores and 45% porosity could replicate cancellous bone architecture with clinically relevant fidelity. Such design control can support bone regeneration applications that require anatomy-specific structures. Integrated development and production capabilities reduce handoffs between material developers, designers, and manufacturers. ISO 13485:2016 quality management certification also simplifies procurement for suppliers of patient-specific systems. The medical ceramics market therefore rewards manufacturers that pair customization capabilities with documented process control and stable quality systems.
High Costs Associated with Regulatory Approval, Material Testing, and Cleanroom Manufacturing
Regulatory compliance creates a significant cost burden for smaller and emerging ceramic manufacturers. MedTech Europe reported that Medical Device Regulation (MDR) certification costs increased by up to 100% for nearly all manufacturers surveyed, compared with the former Medical Device Directive. The association also found that maintenance and recertification costs over five years were expected to exceed initial fees by 50%. Larger integrated companies can distribute these expenses across broader portfolios, while focused innovators carry them against narrower revenue bases. Cleanroom requirements add capital costs for bioactive and piezoceramic products with tight contamination limits. The medical ceramics market faces higher entry barriers as U.S. and European requirements increase demands for biocompatibility, wear testing, and traceability across development programs.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Use of Additive Manufacturing in Medical Ceramics Production
- Advancements in Bioactive Surface Engineering for Enhanced Osseointegration and Tissue Regeneration
- Limited Long-Term Clinical Evidence for Emerging Bio-Ceramic Materials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bioresorbable ceramics are projected to grow at the fastest pace, with an 8.33% CAGR through 2031. These materials can reduce the need for revision procedures in bone-defect and spinal-fusion applications when degradation and tissue formation remain well-matched. Bioinert ceramics held 57.83% of the medical ceramics market share in 2025, as alumina, zirconia, and related composites have long clinical records in arthroplasty and dental prosthetics. Their position in the medical ceramics market rests on durability data for ceramic-on-ceramic and ceramic-on-polyethylene bearing systems. Bioactive ceramics, including hydroxyapatite and calcium silicate, serve distinct roles in bone-graft substitution and implant coatings.
Piezoceramics remain specialized materials for ultrasonic surgical tools, intravascular lithotripsy catheters, and implantable sensors. Their selection depends mainly on device performance requirements rather than implant preference. The segment is shifting from passive structural materials toward interfaces designed to support biological activity. A 2025 study reported that calcium phosphate cement modified for fast shaping, biodegradation control, and microenvironment modulation improved osseointegration and bone regeneration in preclinical work. Bioinert suppliers can respond through bioactive surface layers that retain established mechanical performance while adding regenerative functions.
Complete Report Scope:
- By Material
- Bioinert Ceramics
- Bioactive Ceramics
- Bioresorbable Ceramics
- Piezoceramics
- By Application
- Dental
- Orthopedic
- Cardiovascular
- Plastic Surgery
- By End-User Industry
- Hospitals and Clinics
- Ambulatory Surgical Centers
- Specialty Centers
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
North America accounted for 38.22% of the medical ceramics market share in 2025. The region benefits from mature orthopedic and dental procedure capacity, reimbursement support for ceramic bearing systems, and a dense network of medical device and specialist component suppliers. MatOrtho's ReCerf all-ceramic hip resurfacing system received European CE marking in July 2025, following an earlier FDA Breakthrough Device Designation, and uses CeramTec's BIOLOX delta material. This progression reflects the region's importance for clinical validation and early commercialization of advanced ceramic systems. Canada contributes demand through orthopedic program expansion, while Mexico benefits from private-pay dental implant activity in urban areas.
Europe holds a significant position in the market, supported by Germany's depth in high-performance technical ceramics and medical technology manufacturing. SPECTARIS reported that Germany's medical technology sector included nearly 1,500 manufacturers, generated EUR 41.3 billion (~USD 47.03 billion) in revenue in 2024, and accounted for 16% of exports to Asian markets. Medical Device Regulation (MDR) maintenance and recertification costs are putting pressure on smaller European specialists and encouraging consolidation. South American demand is concentrated in Brazil and Argentina, while the Middle-East and Africa remain early-stage markets, constrained by financing limitations and specialist care capacity.
Asia-Pacific is projected to be the fastest-growing medical ceramics market, with a CAGR of 7.81% through 2031. Population aging, localized manufacturing policies, and healthcare capacity expansion are driving demand across major regional economies. The market also benefits from growing public and private treatment capacity. Japan's established regulatory framework, India's domestic device development, and South Korea's dental ceramics capabilities offer varied routes to regional growth. Suppliers in the Asia-Pacific medical ceramics market are still required to meet high standards for biocompatibility, traceability, and reproducible materials processing.
- 3M
- Ceramaret SA
- CeramTec GmbH
- CoorsTek Inc.
- Institut Straumann AG
- Ivoclar Vivadent
- KYOCERA Corporation
- Morgan Advanced Materials plc
- NGK Spark Plug Co., Ltd.
- Nishimura Advanced Ceramics Co., Ltd.
- Precision Ceramics Limited
- Rauschert GmbH
- Saint-Gobain Ceramics
- Tosoh Corporation
- Zimmer Biomet Holdings, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for Orthopedic and Dental Ceramic Implants
- 4.2.2 Growing Adoption of Patient-Specific Ceramic Implants Through Advanced Manufacturing Technologies
- 4.2.3 Expanding Use of Additive Manufacturing in Medical Ceramics Production
- 4.2.4 Advancements in Bioactive Surface Engineering for Enhanced Osseointegration and Tissue Regeneration
- 4.2.5 Growing Demand for Miniaturized Piezoceramic Components in Advanced Medical Devices
- 4.3 Market Restraints
- 4.3.1 High Costs Associated with Regulatory Approval, Material Testing, and Cleanroom Manufacturing
- 4.3.2 Limited Long-Term Clinical Evidence for Emerging Bioceramic Materials
- 4.3.3 Dependence on High-Purity Raw Materials and Specialized High-Temperature Processing Equipment
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material
- 5.1.1 Bioinert Ceramics
- 5.1.2 Bioactive Ceramics
- 5.1.3 Bioresorbable Ceramics
- 5.1.4 Piezoceramics
- 5.2 By Application
- 5.2.1 Dental
- 5.2.2 Orthopedic
- 5.2.3 Cardiovascular
- 5.2.4 Plastic Surgery
- 5.3 By End-User Industry
- 5.3.1 Hospitals and Clinics
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Specialty Centers
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Ceramaret SA
- 6.4.3 CeramTec GmbH
- 6.4.4 CoorsTek Inc.
- 6.4.5 Institut Straumann AG
- 6.4.6 Ivoclar Vivadent
- 6.4.7 KYOCERA Corporation
- 6.4.8 Morgan Advanced Materials plc
- 6.4.9 NGK Spark Plug Co., Ltd.
- 6.4.10 Nishimura Advanced Ceramics Co., Ltd.
- 6.4.11 Precision Ceramics Limited
- 6.4.12 Rauschert GmbH
- 6.4.13 Saint-Gobain Ceramics
- 6.4.14 Tosoh Corporation
- 6.4.15 Zimmer Biomet Holdings, Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

