PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118924

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118924
Hospital At Home - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the hospital at home market size was valued at USD 39 billion in 2025 and is estimated to grow from USD 42.08 billion in 2026 to reach USD 61.55 billion by 2031, at a CAGR of 7.90% during the forecast period (2026-2031).
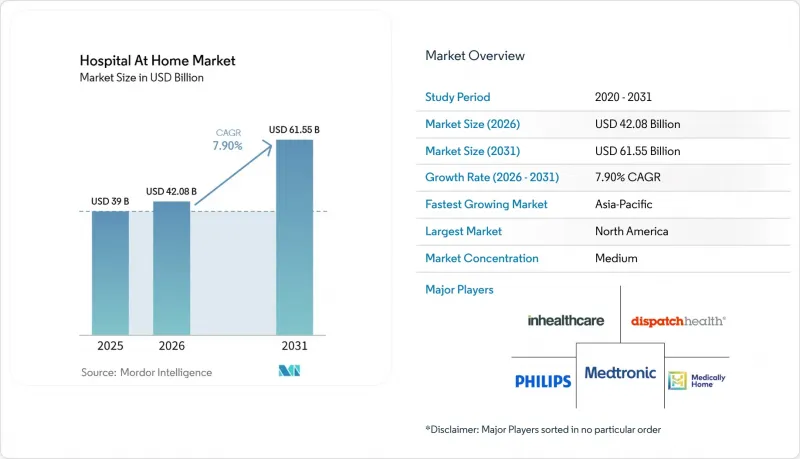
This report is Segmented by Component (Equipment and Devices; Software and Services), Service Type, Care Model, Delivery Mode, Patient Demographic (Adults; Pediatric; Older Adults), Indication, Care Provider, and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). Market Forecasts are in Value (USD).
Global Hospital At Home Market Trends and Insights
Aging Population and Rising Multimorbidity
Demand in the hospital at home market remains closely linked to population aging and the rising number of patients with multiple chronic conditions. The United Nations projects that the global population aged 65 years and above will reach 1.6 billion by 2050. These patients often require frequent care episodes and face higher risks during extended inpatient stays, including delirium, reduced mobility, and hospital-acquired infections. Singapore's MICHome model reported a 23% lower cost per episode with equivalent clinical outcomes, supporting policy interest in home-based acute care.
Hospital Capacity Constraints and Bed Shortages
Inpatient capacity pressure strengthened the business case for delivering hospital-level care at home. Average US acute hospital occupancy exceeded 85% by late 2024, while demand continued to pressure beds in urban and suburban facilities. DispatchHealth and Saint Francis Health System launched a joint venture in Tulsa in February 2026, with a virtual unit designed to scale to 40 concurrent patients. Germany's AOK Krankenhaus-Report 2026 found that 56% of current inpatient services could shift to ambulatory or home settings, while 11% of emergency department admissions could be managed without inpatient admission.
Workforce Shortages and Limited Clinical Coverage
Workforce shortages remained a key operating constraint in the hospital at home market in 2026. HRSA projected shortages of 108,960 registered nurses and 245,950 licensed practical nurses by 2038, while non-metropolitan areas faced a projected registered nurse gap of 11%, compared with 2% in metropolitan areas.The Commonwealth Fund reported that home care agencies turned away more than 25% of patients referred for home care due to staffing gaps.
These shortages particularly affected high-acuity and rural patients, as they required reliable clinical coverage and rapid escalation pathways. Home health agencies also reported frontline turnover of 70% to 80%, increasing recruitment costs and disrupting visit schedules. Tele-hospitalist models supported by community paramedics may reduce local staffing pressure, but reimbursement and credentialing rules still required greater standardization.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Value-Based and Episode-Based Reimbursement
- Hospital-at-Home Command Centers and AI-Enabled Escalation
- Reimbursement and Regulatory Uncertainty
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Equipment and Devices held 64.55% of the hospital at home market in 2025. This category includes remote patient monitoring devices, diagnostic equipment, connectivity tools, medication delivery systems, and infusion equipment. Continuous monitoring devices collect heart rate, oxygen saturation, and respiratory rate data for command-center review. The component remains essential as hospital-at-home programs require dependable clinical equipment and secure data transmission.
Software and Services is the fastest-growing component, with the hospital at home market size for this segment projected to register a 9.15% CAGR during 2026-2031. The category includes hospital-at-home software platforms, clinical command-center software, telehealth services, implementation support, consulting, and managed services. Health systems that completed early device deployments during 2023 and 2024 are now investing more in workflow tools to coordinate visits, document care, manage alerts, and monitor patient progress. Philips partnered with Southern NSW Local Health District in December 2025 to deploy its Respiree wearable monitoring solution for acute care in the home.
Acute Care at Home accounted for 33.56% of the hospital at home market share in 2025. The service covers acute conditions such as chronic obstructive pulmonary disease exacerbations, pneumonia, cellulitis, heart failure, sepsis, and other eligible cases. CMS designed the Acute Hospital Care at Home waiver for acute-level admissions that providers can safely manage outside inpatient facilities. This model helps hospitals deliver inpatient-equivalent services while preserving physical bed capacity.
Chronic Disease Management at Home is projected to record an 8.80% CAGR from 2026 to 2031. The increasing prevalence of long-term conditions and contracts that reward lower total treatment costs support chronic care programs. Home-based management can reduce travel needs, support coordinated follow-up, and help care teams identify deterioration earlier. Mayo Clinic's Cancer CARE Beyond Walls study presented phase-2 feasibility data at ASCO 2025 on home-based cancer therapy compared with standard in-clinic care and reported safety and patient-preference benefits.
Early-Supported Discharge commanded 56.77% of the hospital at home market share in 2025. The model serves patients who have already received hospital assessment and can complete recovery at home with clinical support. It is established across United Kingdom virtual wards, Australian Hospital in the Home programs, and Singapore's MIC@Home model. Singapore's NUHS@Home reported a 23% lower cost per episode in the input.
Admission Avoidance is forecast to expand at a 10.45% CAGR through 2031. This model assesses eligible patients in emergency departments, primary care settings, or referral pathways before an inpatient admission occurs. It can generate greater cost savings by intervening earlier in the care journey, but it requires rapid triage, home-readiness assessment, logistics planning, and care-team deployment. DispatchHealth and Saint Francis Health System designed their Tulsa program around this model, targeting deployment within 30 minutes across a 20-mile service radius.
Complete Report Scope:
- By Component
- Equipment and Devices
- Remote Patient Monitoring Devices
- Diagnostic and Point-of-Care Devices
- Connectivity and Communication Equipment
- Medication Delivery and Infusion Equipment
- Software and Services
- Hospital-at-Home Software Platforms
- Clinical Command Center Software
- Telehealth and Virtual Care Services
- Implementation, Consulting, and Managed Services
- Equipment and Devices
- By Service Type
- Acute Care at Home
- Chronic Disease Management at Home
- Post-Acute and Transitional Care
- Palliative Care and Hospice Care
- Rehabilitation Services
- By Care Model
- Admission Avoidance
- Early-Supported Discharge
- Hybrid Admission Avoidance and Early-Supported Discharge
- Virtual Ward Model
- By Delivery Mode
- Remote Monitoring and Telehealth
- In-Person Home Visits
- Hybrid Virtual and In-Person Care
- By Patient Demographic
- Adult Patients
- Pediatric Patients
- Older Adults
- By Indication
- Cardiovascular Conditions
- Respiratory Diseases
- Infectious Diseases
- Neurological Conditions
- Orthopedic and Post-Surgical Recovery
- Renal and Metabolic Conditions
- Oncology and Immunocompromised Care
- Other Clinical Indications
- By Care Provider
- Hospitals and Health Systems
- Home Health Agencies
- Primary Care and Physician Groups
- Private Hospital-at-Home Providers
- Health Plans and Integrated Delivery Networks
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 42.45% of the global hospital at home market in 2025, supported by the U.S. CMS policy framework, established insurance systems, and a strong base of technology-enabled care providers. The Consolidated Appropriations Act of 2026 extended the Acute Hospital Care at Home waiver through September 30, 2030, giving providers a longer investment horizon. U.S. programs remained concentrated in metropolitan areas due to better staffing, technology, and emergency response availability, while nursing shortages, limited community paramedic credentialing, and reimbursement gaps constrained rural expansion. Canada advanced virtual ward programs through provincial health systems, while Mexico showed growth potential despite limited private insurance penetration and home-care infrastructure.
Europe remained an expanding but diverse part of the hospital at home market, with the United Kingdom operating one of the region's most established virtual ward systems. NHS Greater Glasgow and Clyde partnered with Doccla in April 2025 to deploy 1,000 virtual ward beds through a phased three-year program, while Scotland had committed to 2,000 national virtual ward beds by the end of 2026. Philips' Region Stockholm agreement highlighted rising interest in long-term regional contracts for remote monitoring and hospital-at-home technology. Germany remained a substantial opportunity, although cross-sector reimbursement reform, nursing licensing requirements, and data protection rules continued to limit broader adoption.
Asia-Pacific was the fastest-growing regional segment, with the hospital at home market size projected to grow at a 9.45% CAGR from 2026 to 2031. Singapore's MIC@Home program expanded across public hospitals and treated nearly 7,000 patients while saving more than 42,000 hospital bed-days by late 2024. The National University Health System planned to expand to 400 virtual ward beds by 2030, while Australia supported Hospital in the Home growth through health-district partnerships and connected patient monitoring. The Middle East and Africa remained at an earlier stage despite digital infrastructure investments by Gulf Cooperation Council health systems, while South American expansion centered on Brazil and Argentina.
- Addus HomeCare Corporation
- Air Liquide S.A.
- Amedisys
- Aveanna Healthcare Holdings Inc.
- B. Braun
- Baxter
- Best Buy Co., Inc.
- Biofourmis, Inc.
- DispatchHealth Management, LLC
- Doccla Limited
- Enhabit, Inc.
- GE HealthCare Technologies Inc.
- Huma Therapeutics Limited
- Inhealthcare Limited
- Koninklijke Philips
- Liva Healthcare A/S
- Medically Home Group, Inc.
- Medtronic
- Microsoft
- Option Care Health, Inc.
- Oracle
- Siemens Healthineers
- Teladoc Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Population and Rising Multimorbidity
- 4.2.2 Hospital Capacity Constraints and Bed Shortages
- 4.2.3 Expansion of Value-Based and Episode-Based Reimbursement
- 4.2.4 Patient Preference for Care in the Home
- 4.2.5 Hospital-at-Home Command Centers and AI-Enabled Escalation
- 4.2.6 Home Infrastructure Readiness as a New Eligibility Filter
- 4.3 Market Restraints
- 4.3.1 Workforce Shortages and Limited Clinical Coverage
- 4.3.2 Reimbursement and Regulatory Uncertainty
- 4.3.3 Unequal Broadband, Housing, and Caregiver Availability
- 4.3.4 Liability, Escalation, and Patient-Safety Risk in the Home
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Component
- 5.1.1 Equipment and Devices
- 5.1.1.1 Remote Patient Monitoring Devices
- 5.1.1.2 Diagnostic and Point-of-Care Devices
- 5.1.1.3 Connectivity and Communication Equipment
- 5.1.1.4 Medication Delivery and Infusion Equipment
- 5.1.2 Software and Services
- 5.1.2.1 Hospital-at-Home Software Platforms
- 5.1.2.2 Clinical Command Center Software
- 5.1.2.3 Telehealth and Virtual Care Services
- 5.1.2.4 Implementation, Consulting, and Managed Services
- 5.1.1 Equipment and Devices
- 5.2 By Service Type
- 5.2.1 Acute Care at Home
- 5.2.2 Chronic Disease Management at Home
- 5.2.3 Post-Acute and Transitional Care
- 5.2.4 Palliative Care and Hospice Care
- 5.2.5 Rehabilitation Services
- 5.3 By Care Model
- 5.3.1 Admission Avoidance
- 5.3.2 Early-Supported Discharge
- 5.3.3 Hybrid Admission Avoidance and Early-Supported Discharge
- 5.3.4 Virtual Ward Model
- 5.4 By Delivery Mode
- 5.4.1 Remote Monitoring and Telehealth
- 5.4.2 In-Person Home Visits
- 5.4.3 Hybrid Virtual and In-Person Care
- 5.5 By Patient Demographic
- 5.5.1 Adult Patients
- 5.5.2 Pediatric Patients
- 5.5.3 Older Adults
- 5.6 By Indication
- 5.6.1 Cardiovascular Conditions
- 5.6.2 Respiratory Diseases
- 5.6.3 Infectious Diseases
- 5.6.4 Neurological Conditions
- 5.6.5 Orthopedic and Post-Surgical Recovery
- 5.6.6 Renal and Metabolic Conditions
- 5.6.7 Oncology and Immunocompromised Care
- 5.6.8 Other Clinical Indications
- 5.7 By Care Provider
- 5.7.1 Hospitals and Health Systems
- 5.7.2 Home Health Agencies
- 5.7.3 Primary Care and Physician Groups
- 5.7.4 Private Hospital-at-Home Providers
- 5.7.5 Health Plans and Integrated Delivery Networks
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 Europe
- 5.8.2.1 Germany
- 5.8.2.2 United Kingdom
- 5.8.2.3 France
- 5.8.2.4 Italy
- 5.8.2.5 Spain
- 5.8.2.6 Rest of Europe
- 5.8.3 Asia-Pacific
- 5.8.3.1 China
- 5.8.3.2 India
- 5.8.3.3 Japan
- 5.8.3.4 Australia
- 5.8.3.5 South Korea
- 5.8.3.6 Rest of Asia-Pacific
- 5.8.4 Middle East and Africa
- 5.8.4.1 GCC
- 5.8.4.2 South Africa
- 5.8.4.3 Rest of Middle East and Africa
- 5.8.5 South America
- 5.8.5.1 Brazil
- 5.8.5.2 Argentina
- 5.8.5.3 Rest of South America
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Addus HomeCare Corporation
- 6.3.2 Air Liquide S.A.
- 6.3.3 Amedisys, Inc.
- 6.3.4 Aveanna Healthcare Holdings Inc.
- 6.3.5 B. Braun SE
- 6.3.6 Baxter International Inc.
- 6.3.7 Best Buy Co., Inc.
- 6.3.8 Biofourmis, Inc.
- 6.3.9 DispatchHealth Management, LLC
- 6.3.10 Doccla Limited
- 6.3.11 Enhabit, Inc.
- 6.3.12 GE HealthCare Technologies Inc.
- 6.3.13 Huma Therapeutics Limited
- 6.3.14 Inhealthcare Limited
- 6.3.15 Koninklijke Philips N.V.
- 6.3.16 Liva Healthcare A/S
- 6.3.17 Medically Home Group, Inc.
- 6.3.18 Medtronic plc
- 6.3.19 Microsoft Corporation
- 6.3.20 Option Care Health, Inc.
- 6.3.21 Oracle Corporation
- 6.3.22 Siemens Healthineers AG
- 6.3.23 Teladoc Health, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

