PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118985

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118985
Traumatic Brain Injury Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the traumatic brain injury treatment market size is projected to expand from USD 2.15 billion in 2025 and USD 2.30 billion in 2026 to USD 3.20 billion by 2031, registering a CAGR of 6.88% between 2026 to 2031.
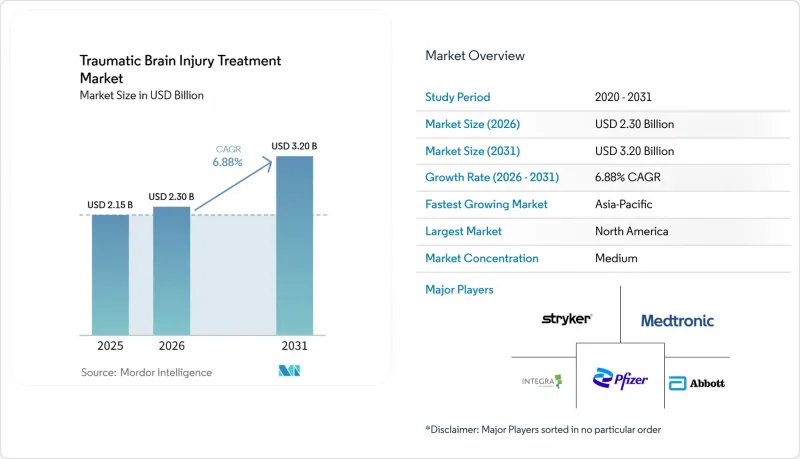
This report Segments the Industry Into by Treatment Type (Immediate Emergency Care, and More), Care Phase (Prehospital and Emergency Stabilization, and More), Patient Age (Pediatric Patients, and More), Cause of Injury (Falls, and More), End User (Hospitals and Trauma Centers, and More), Distribution Channel, and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Traumatic Brain Injury Treatment Market Trends and Insights
Rising TBI Incidence From Falls, Road Traffic, and Sports Injuries
The traumatic brain injury treatment market draws its most stable demand from the volume of new injuries. In the United States, 68,663 TBI-related deaths were recorded in 2023. Falls accounted for nearly half of TBI-related hospitalizations nationally. Sports participation and concussion protocols bring more mild injuries into documented clinical care. Better awareness and helmet use can reduce mortality while increasing the number of survivors needing continued care.
Expansion of Neurocritical Care and Trauma Networks
The traumatic brain injury treatment market benefits when hospitals build more capable trauma and neurocritical care services. Designated trauma centers increase the intensity of acute triage and treatment after severe injury. The Brain Trauma Foundation guidelines support intracranial pressure monitoring and structured sedation-analgesia management in severe TBI care. These practices support demand for monitoring catheters, osmolar diuretics, and vasoactive medicines. A January 2025 study found that intensivist-led catheter placement reduced intracranial hypertension exposure time compared with neurosurgeon-managed placement. The wider use of protocol-driven neuro-ICU care can extend device and medication use into less established settings.
Absence of Broadly Approved Disease-Modifying Pharmacotherapies
The traumatic brain injury treatment market, therefore, remains centered on symptom control, supportive medicines, surgery, monitoring, and rehabilitation. SHINKEI Therapeutics completed its Phase 2 SHINKEITBI trial for MR-301, an intravenous amantadine HCl formulation. The program is preparing for an End-of-Phase 2 FDA meeting on a potential Phase 3 design. Current prescribing remains dispersed across generic and off-label products, which limits pricing power for most participants. A TBI-specific disease-modifying treatment could rapidly change the competitive balance because the unmet need is significant. Until then, pharmacological revenue remains below the level associated with proprietary, approved therapies.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Adoption of Objective Mild TBI Assessment
- Growth of Long-Term Neurorehabilitation and Survivorship Care
- Heterogeneous Injury Phenotypes and Weak Trial Endpoint Consistency
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Medications held 41.25% of the traumatic brain injury treatment market share in 2025. Osmolar diuretics, anti-seizure medicines, sedatives, antidepressants, antipsychotics, and stimulants support acute and chronic care. Their broad use reflects the need to manage intracranial pressure, seizures, agitation, mood symptoms, and sleep issues. Immediate emergency care and surgery address the most severe presentations. Decompressive craniectomy, hematoma evacuation, and intracranial pressure diversion are intensive episodes of care. Their utilization is limited by the share of patients with injuries severe enough to require intervention. Hospitals remain central because these procedures require specialized teams and equipment.
Rehabilitation therapies are projected to grow at a 7.54% CAGR through 2031. Physical, cognitive, speech, and neuropsychological therapies address deficits that can persist for years after injury. The traumatic brain injury treatment market size for rehabilitation expands as more patients survive the acute phase. Digital therapy, virtual reality, robotics-assisted rehabilitation, and adaptive programs are being used to support engagement and measurable recovery.
Acute hospital and neurocritical care held 43.95% of the market share in 2025. Intracranial pressure monitoring, sedation, neurosurgical access, and multimodal monitoring make inpatient treatment resource-intensive. The acute setting manages the period in which rapid stabilization can prevent further neurological harm. Prehospital and emergency stabilization provide the first entry point into this care pathway. Advanced trauma life support protocols guide early assessment and transport decisions. Field assessment and biomarker testing may improve triage before hospital arrival. The traumatic brain injury treatment market remains strongly tied to hospital capability during this stage.
Chronic outpatient and community care is forecast to grow at a 8.02% CAGR through 2031. Better survival and reimbursement for ambulatory management are shifting patients after recovery into longer-term services. Veterans with TBI may require continuing management for cognitive, psychiatric, and pain-related symptoms. Post-acute inpatient rehabilitation remains important for patients with moderate and severe injuries. These patients often need intensive therapy before returning to community settings. This mix increases the importance of coordinated transitions between hospital, rehabilitation, clinic, and home care providers.
Complete Report Scope:
- By Treatment Type
- Immediate Emergency Care
- Medications
- Diuretics and Hyperosmolar Agents
- Anti-Seizure Drugs
- Analgesics and Sedatives
- Antidepressants and Anxiolytics
- Antipsychotics and Neuropsychiatric Treatments
- Hemostatic Agents
- Stimulants and Dopaminergic Agents
- Other Medications
- Surgery
- Decompressive Craniectomy
- Hematoma Evacuation
- Cranioplasty and Skull-Fracture Repair
- Intracranial Pressure Diversion and Drainage
- Minimally Invasive and Image-Guided Neurosurgery
- Rehabilitation Therapies
- Physical and Occupational Therapy
- Speech, Language and Swallowing Therapy
- Cognitive Rehabilitation
- Neuropsychological and Behavioral Therapy
- Spasticity Management
- Other Rehabilitation Therapies
- By Care Phase
- Prehospital and Emergency Stabilization
- Acute Hospital and Neurocritical Care
- Post-Acute Inpatient Rehabilitation
- Chronic Outpatient and Community Care
- By Patient Age
- Pediatric Patients
- Adolescent Patients
- Adult Patients
- Geriatric Patients
- By Cause of Injury
- Falls
- Motor Vehicle Traffic Injuries
- Sports and Recreational Injuries
- Occupational and Industrial Injuries
- Military and Blast-Related Injuries
- Assault and Violence-Related Injuries
- Other Traumatic Causes
- By End User
- Hospitals and Trauma Centers
- Neurology and Neurosurgery Clinics
- Ambulatory Care Centers
- Home Care and Community Care
- Other End Users
- By Distribution Channel
- Hospital Pharmacies
- Retail and Independent Pharmacies
- Specialty Pharmacies
- Direct Institutional Procurement
- Online and Digital Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 41.63% of the global traumatic brain injury treatment market revenue in 2025. The region benefits from dense trauma networks, extensive acute care coverage, and early use of biomarker diagnostics. The FDA clearance of Abbott's whole-blood TBI test supported point-of-care assessment for mild injuries. The United States contributes the largest regional revenue base. More than 485,000 TBI cases among service members since 2000 support a lasting demand in military and veterans' health systems. Remote monitoring reimbursement also supports outpatient and home care after discharge.
Asia-Pacific is forecast to grow at a 8.22% CAGR through 2031. Japan approved Akuugo conditionally in August 2024, granted full approval in October 2025, and listed it under National Health Insurance in May 2026. SanBio is targeting 20-30 specialized treatment centers for early deployment. Japan also has academic research programs exploring cerebrovascular neuroprotection in TBI models. East Asia recorded 9.52 million prevalent TBI cases in 2021, with China representing a large share of regional volume. India's trauma care expansion and road injury burden support future demand, while lower-cost monitoring and diagnostics may be important in other emerging regions.
Europe has established clinical standards across Germany, the United Kingdom, France, Italy, and Spain. National neurosurgery guidance and EMA frameworks influence treatment protocols. French guidelines released in 2025 covered the acute management of adult and pediatric TBI. The guidance supports continued investment in monitoring, surgical, and hemostatic products. A January 2026 published German study identified 122.5 days as an optimal interval between decompressive craniectomy and cranioplasty for reducing postoperative complications. Central and Eastern Europe have a higher TBI burden than Western Europe. This gap points to unmet need and room for broader treatment access.
- Cellvation, Inc.
- Dr. Reddy's Laboratories
- Hope Biosciences LLC
- Integra LifeSciences
- Ipsen Pharma SAS
- Medtronic
- Merz Therapeutics GmbH
- Oragenics, Inc.
- Oxeia Biopharmaceuticals, Inc.
- Pfizer
- SanBio Co., Ltd.
- SHINKEI Therapeutics, Inc.
- Stryker
- Sun Pharmaceuticals Industries
- Supernus Pharmaceuticals
- Teva Pharmaceutical Industries
- veriNOS Pharmaceuticals GmbH
- Viatris
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising TBI Incidence From Falls, Road Traffic, and Sports Injuries
- 4.2.2 Expansion of Neurocritical Care and Trauma Networks
- 4.2.3 Increasing Adoption of Objective Mild TBI Assessment
- 4.2.4 Growth of Long-Term Neurorehabilitation and Survivorship Care
- 4.2.5 Biomarker-Guided and Precision TBI Management
- 4.2.6 Intranasal, Cell-Based, and Neuroprotective Pipeline Innovation
- 4.3 Market Restraints
- 4.3.1 Absence of Broadly Approved Disease-Modifying Pharmacotherapies
- 4.3.2 Heterogeneous Injury Phenotypes and Weak Trial Endpoint Consistency
- 4.3.3 Time-Critical Treatment Windows and Delayed Care Pathways
- 4.3.4 Specialist, Rehabilitation and Advanced Monitoring Capacity Gaps
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Treatment Type
- 5.1.1 Immediate Emergency Care
- 5.1.2 Medications
- 5.1.2.1 Diuretics and Hyperosmolar Agents
- 5.1.2.2 Anti-Seizure Drugs
- 5.1.2.3 Analgesics and Sedatives
- 5.1.2.4 Antidepressants and Anxiolytics
- 5.1.2.5 Antipsychotics and Neuropsychiatric Treatments
- 5.1.2.6 Hemostatic Agents
- 5.1.2.7 Stimulants and Dopaminergic Agents
- 5.1.2.8 Other Medications
- 5.1.3 Surgery
- 5.1.3.1 Decompressive Craniectomy
- 5.1.3.2 Hematoma Evacuation
- 5.1.3.3 Cranioplasty and Skull-Fracture Repair
- 5.1.3.4 Intracranial Pressure Diversion and Drainage
- 5.1.3.5 Minimally Invasive and Image-Guided Neurosurgery
- 5.1.4 Rehabilitation Therapies
- 5.1.4.1 Physical and Occupational Therapy
- 5.1.4.2 Speech, Language and Swallowing Therapy
- 5.1.4.3 Cognitive Rehabilitation
- 5.1.4.4 Neuropsychological and Behavioral Therapy
- 5.1.4.5 Spasticity Management
- 5.1.4.6 Other Rehabilitation Therapies
- 5.2 By Care Phase
- 5.2.1 Prehospital and Emergency Stabilization
- 5.2.2 Acute Hospital and Neurocritical Care
- 5.2.3 Post-Acute Inpatient Rehabilitation
- 5.2.4 Chronic Outpatient and Community Care
- 5.3 By Patient Age
- 5.3.1 Pediatric Patients
- 5.3.2 Adolescent Patients
- 5.3.3 Adult Patients
- 5.3.4 Geriatric Patients
- 5.4 By Cause of Injury
- 5.4.1 Falls
- 5.4.2 Motor Vehicle Traffic Injuries
- 5.4.3 Sports and Recreational Injuries
- 5.4.4 Occupational and Industrial Injuries
- 5.4.5 Military and Blast-Related Injuries
- 5.4.6 Assault and Violence-Related Injuries
- 5.4.7 Other Traumatic Causes
- 5.5 By End User
- 5.5.1 Hospitals and Trauma Centers
- 5.5.2 Neurology and Neurosurgery Clinics
- 5.5.3 Ambulatory Care Centers
- 5.5.4 Home Care and Community Care
- 5.5.5 Other End Users
- 5.6 By Distribution Channel
- 5.6.1 Hospital Pharmacies
- 5.6.2 Retail and Independent Pharmacies
- 5.6.3 Specialty Pharmacies
- 5.6.4 Direct Institutional Procurement
- 5.6.5 Online and Digital Channels
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Cellvation, Inc.
- 6.3.2 Dr. Reddy's Laboratories Limited
- 6.3.3 Hope Biosciences LLC
- 6.3.4 Integra LifeSciences Holdings Corporation
- 6.3.5 Ipsen Pharma SAS
- 6.3.6 Medtronic plc
- 6.3.7 Merz Therapeutics GmbH
- 6.3.8 Oragenics, Inc.
- 6.3.9 Oxeia Biopharmaceuticals, Inc.
- 6.3.10 Pfizer Inc.
- 6.3.11 SanBio Co., Ltd.
- 6.3.12 SHINKEI Therapeutics, Inc.
- 6.3.13 Stryker Corporation
- 6.3.14 Sun Pharmaceutical Industries Limited
- 6.3.15 Supernus Pharmaceuticals, Inc.
- 6.3.16 Teva Pharmaceutical Industries Ltd.
- 6.3.17 veriNOS Pharmaceuticals GmbH
- 6.3.18 Viatris Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

