PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119029

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119029
Automotive Silicone - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive silicone market size was estimated at USD 2.64 billion in 2025 and is estimated to grow from USD 2.81 billion in 2026 to reach USD 3.98 billion by 2031, at a CAGR of 7.21% during the forecast period (2026-2031).
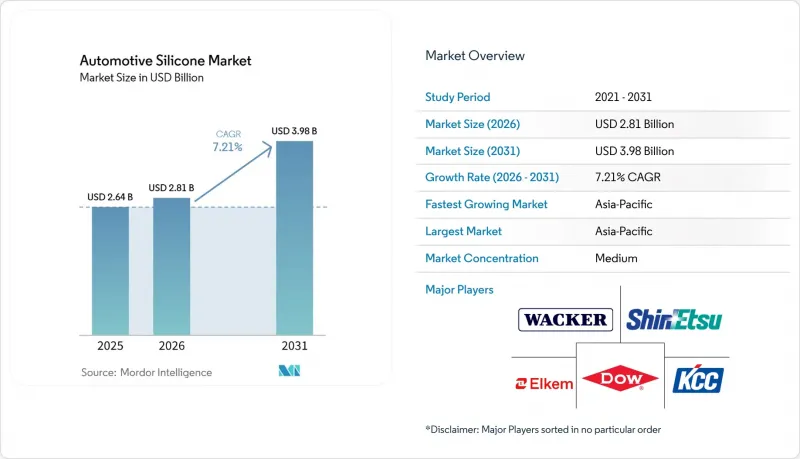
This report is Segmented by Product Type (Silicone Elastomers, Silicone Adhesives and Sealants, and More), Vehicle Type (Hatchback and Sedan, SUV, and More), Application (Powertrain and Engine Components, Electrical and Electronics, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Silicone Market Trends and Insights
Growing Electric Vehicle Production Driving Demand for High-Voltage Sealing Solutions
The shift to 800V electric vehicle architecture has raised sealing requirements for batteries, connectors, and power electronics. Conventional Ethylene Propylene Diene Monomer (EPDM) rubber compounds have limitations in applications that require durable electrical insulation at higher temperatures and voltages. Dow introduced DOWSIL EG-4175 Silicone Gel in September 2025 for systems transitioning from 400V to 800V, with a stated temperature capability of 180°C. The automotive silicone market has a growing need for grades that reduce the risks of thermal degradation, partial discharge, and electrical tracking. Low-permittivity and platinum-cured formulations can address these demands in high-voltage hardware. These requirements favor suppliers that can meet qualification standards for battery and power-electronics applications.
Stringent Thermal Management and Fire Safety Requirements in Automotive Electronics
Battery thermal runaway mitigation requires several protective functions within the same battery pack. Silicone materials can serve as ceramifying foams, fire barriers, potting gels, and high-consistency rubber coatings. Wacker Chemie presented ELASTOSIL R 531/60 in October 2025, stating that it can operate continuously at 205°C and form a ceramic layer at 800°C to 1,000°C. Evonik described TEGO Therm coatings for battery housings as sprayable, fire-resistant, and suitable for complex three-dimensional surfaces. European Commission guidance published in February 2025 supports layered fire-containment approaches for electric vehicles in covered parking areas. The automotive silicone market benefits when vehicle manufacturers opt for integrated material systems rather than single-barrier materials.
Volatility in Silicone Raw Material Prices and Supply Chain Concentration
Automotive silicone formulators are exposed to changes in silicone feedstock availability and pricing, particularly those without integrated upstream material positions. Supply disruptions can create price movements that compress margins when suppliers cannot pass costs to vehicle customers quickly. Silicon metal capacity requires long construction timelines and environmental approvals, which can delay supply responses. This limits buyer flexibility when supply is concentrated. As a result, the automotive silicone market remains exposed to short-term procurement and margin pressure.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Adoption of Lightweight and Multi-Material Vehicle Architectures
- Rising Use of Silicone Materials for Enhanced Durability in Powertrain and Underbody Applications
- Growing Competition from Alternative Elastomers and Polymer Materials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone elastomers held 38.75% of the automotive silicone market share in 2025, making them the largest product category. They are used in gaskets, O-rings, hoses, and powertrain seals that require low compression set performance and heat resistance above 150°C. Adhesives and sealants are forecast to grow at 8.63% CAGR from 2026 to 2031, the highest rate among the listed product types. Cell-to-pack battery designs require materials that exclude moisture, provide electrical isolation, and support thermal management. The automotive silicone market benefits when these functions are combined in fewer components.
Silicone fluids support damping mechanisms and connector lubrication, while resins can form fire-barrier laminates for battery covers. Gels and foam protect and encapsulate vibration-sensitive electronics. Restrictions on D4, D5, and D6 cyclic siloxanes are influencing reformulation in fluids and adhesives. Dow announced a USD 100 million investment in specialty silicone manufacturing in June 2026, including engineered silicone materials capacity in Songjiang and Fukui, expected to come online in 2026. As a result, the automotive silicone market is placing greater emphasis on high-purity adhesives and gels for automotive electronics.
Complete Report Scope:
- By Product Type
- Silicone Elastomers
- Silicone Adhesives and Sealants
- Silicone Fluids
- Silicone Resins
- Silicone Gels and Foams
- By Vehicle Type
- Hatchback and Sedan
- SUV
- Light Commercial Vehicles (LCV)
- Heavy Commercial Vehicles (HCV)
- By Application
- Powertrain and Engine Components
- Electrical and Electronics
- Interior Applications
- Exterior Applications
- Thermal Management Systems
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 45.72% of the automotive silicone market share in 2025 and is expected to grow at a CAGR of 8.51% through 2031, making it both the largest and fastest-growing regional market. China drives demand for battery-grade sealing and thermal interface materials through its large base of new-energy vehicle production. Japan and South Korea contribute to regional innovation through companies such as Shin-Etsu Chemical and KCC Silicone. KCC Silicone's collaboration with Hyundai MOBIS in July 2025 highlighted the role of Korean OEM co-development in the automotive silicone market.
North America holds a significant position in the market, supported by the United States' Tier 1 automotive supply base and domestic battery manufacturing investment. In September 2025, Henkel completed an expansion of its Brandon, South Dakota, facility, doubling its production area to 6,500 square meters for thermal management materials and adhesives. Henkel also opened its North America Battery Application Center in Madison Heights, Michigan, in September 2025. These investments brought technical development and material supply closer to OEM engineering teams. Mexico contributes to demand as part of the North American vehicle assembly network under the United States-Mexico-Canada Agreement (USMCA).
Europe's automotive silicone market is supported by fleet-average CO2 regulations that encourage electrification and increase demand for battery sealing materials. Germany remains a key co-development location for OEMs, Tier 1 suppliers, and specialty material producers. Elkem's recycling research provides European suppliers with a potential technical advantage in end-of-life silicone processing. South America, the Middle-East, and Africa represent smaller demand centers, with lower silicone content per vehicle reflecting lower electric vehicle adoption rates in these regions.
- 3M
- Dow
- Elkem ASA
- Evonik Industries AG
- H.B. Fuller Company
- Henkel AG and Co. KGaA
- KCC Corporation
- Momentive
- Novagard
- Reiss Manufacturing, Inc.
- Rogers Corporation
- Shin-Etsu Chemical Co., Ltd.
- Sika AG
- Siltech Corporation
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Electric Vehicle Production Driving Demand for High-Voltage Sealing Solutions
- 4.2.2 Stringent Thermal Management and Fire Safety Requirements in Automotive Electronics
- 4.2.3 Increasing Adoption of Lightweight and Multi-Material Vehicle Architectures
- 4.2.4 Rising Use of Silicone Materials for Enhanced Durability in Powertrain and Underbody Applications
- 4.2.5 Growing Adoption of Low-Volatile Silicone Materials in ADAS and Advanced Automotive Electronics
- 4.3 Market Restraints
- 4.3.1 Volatility in Silicone Raw Material Prices and Supply Chain Concentration
- 4.3.2 Growing Competition from Alternative Elastomers and Polymer Materials
- 4.3.3 Challenges Associated with Recycling and End-of-Life Management of Silicone Components
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Silicone Elastomers
- 5.1.2 Silicone Adhesives and Sealants
- 5.1.3 Silicone Fluids
- 5.1.4 Silicone Resins
- 5.1.5 Silicone Gels and Foams
- 5.2 By Vehicle Type
- 5.2.1 Hatchback and Sedan
- 5.2.2 SUV
- 5.2.3 Light Commercial Vehicles (LCV)
- 5.2.4 Heavy Commercial Vehicles (HCV)
- 5.3 By Application
- 5.3.1 Powertrain and Engine Components
- 5.3.2 Electrical and Electronics
- 5.3.3 Interior Applications
- 5.3.4 Exterior Applications
- 5.3.5 Thermal Management Systems
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Dow
- 6.4.3 Elkem ASA
- 6.4.4 Evonik Industries AG
- 6.4.5 H.B. Fuller Company
- 6.4.6 Henkel AG and Co. KGaA
- 6.4.7 KCC Corporation
- 6.4.8 Momentive
- 6.4.9 Novagard
- 6.4.10 Reiss Manufacturing, Inc.
- 6.4.11 Rogers Corporation
- 6.4.12 Shin-Etsu Chemical Co., Ltd.
- 6.4.13 Sika AG
- 6.4.14 Siltech Corporation
- 6.4.15 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

