PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119143

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119143
Neonatal Thermoregulation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the neonatal thermoregulation market is projected to expand from USD 1.29 billion in 2025 and USD 1.37 billion in 2026 to USD 2.03 billion by 2031, registering a CAGR of 8.13% between 2026 and 2031.
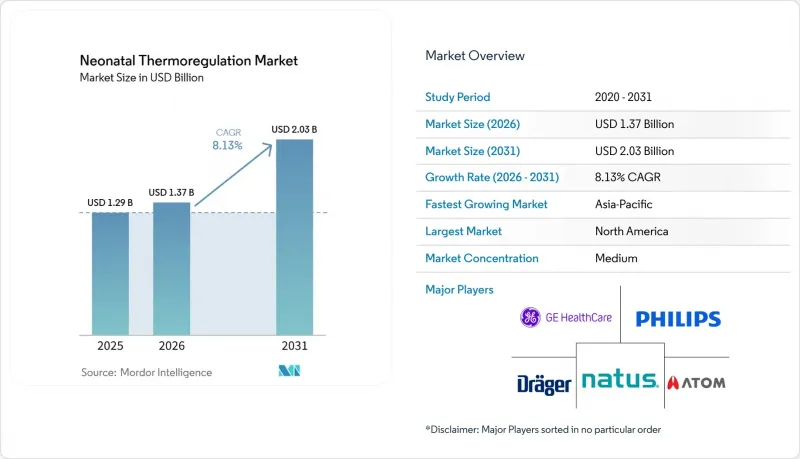
This report is Segmented by Product Type (Incubators, Radiant Warmers, and More), Technology (Servo-Controlled Systems, Air-Based Systems, and More), Application (Hypothermia Management, and More), End-User (Hospitals, Neonatal Intensive Care Units, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Value (USD).
Global Neonatal Thermoregulation Market Trends and Insights
Rising Preterm Births and Low Birth Weight Incidence
Preterm birth remains one of the clearest long-run demand anchors for the neonatal thermoregulation market because temperature stability is essential for infant survival in the first days of care. WHO and UNICEF estimates show that 13.4 million preterm births were recorded annually, which means close to 1 in 10 live births worldwide were premature. A 2025 meta-analysis reported neonatal mortality at 8 per 100 preterm births overall and 40 per 100 among extremely preterm infants, which keeps procurement demand for thermal care equipment difficult to defer. The geographic burden has shifted more heavily toward South Asia and Sub-Saharan Africa, where the installed base for advanced thermoregulation remains underserved and where the neonatal thermoregulation market still has room to widen beyond its traditional high-income base.
Shift Toward Servo-Controlled Closed-Loop Thermoregulation
The neonatal thermoregulation market is moving toward servo-controlled systems because clinical teams want tighter temperature control and less operator-dependent variability in fragile infants. Evidence from 2024 showed the feasibility and safety of servo-controlled thermoregulation in preterm infants at 34 to 35 weeks of gestational age, which broadens the clinical case beyond only the smallest infants. This shift matters commercially because hospitals that once relied on lower-cost open-care systems are now under more pressure to upgrade as guidelines and procurement standards become stricter. The 2024 amendments tied to IEC 60601-2-19 and IEC 60601-2-21 also raise the engineering and certification bar for manufacturers, which favors vendors that already operate within structured compliance systems. The neonatal thermoregulation market is therefore shifting from pure hardware competition toward platforms that can manage temperature, support documentation, and connect with hospital information systems.
High Capital Cost of Advanced Incubators and Warmers
The neonatal thermoregulation market still faces a clear volume constraint because advanced closed-loop incubators are expensive for public hospitals in high-burden countries. Government tender ceilings in parts of South Asia and Sub-Saharan Africa often push buyers toward lower-specification systems, which can reduce uptake of devices with integrated monitoring, humidity control, and alarm redundancy. This creates a split structure inside the neonatal thermoregulation market where premium systems are concentrated in level-III urban NICUs while district hospitals continue to depend on simpler devices. The result is margin pressure for global vendors because the fastest-growing demand pools often remain the most price sensitive. Leasing and pay-per-use models are starting to appear in parts of Asia, but adoption is still uneven and not yet broad enough to remove this pricing barrier across the neonatal thermoregulation market.
Other drivers and restraints analyzed in the detailed report include:
- NICU Capacity Expansion in High-Burden Health Systems
- Demand for Portable Warmers in Transport and Referral Networks
- Kangaroo Mother Care and Low-Tech Thermal Care Substitution for Stable Neonates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Incubators held 40.13% of revenue in 2025, which kept them as the largest product category in the neonatal thermoregulation market because they remain central to enclosed microenvironment management for very low-birth-weight and extremely preterm infants. The 2026 implementation deadlines linked to IEC 60601-2-19 and IEC 60601-2-21 are also pushing parts of the installed base toward compliance-led replacement, which supports ongoing purchasing in the neonatal thermoregulation industry. Radiant warmers remained the second-largest product segment because open-access use in delivery rooms and resuscitation settings still matters where clinicians need thermal support without interrupting procedures.
Temperature monitoring devices are forecasted to grow at 8.24% CAGR through 2031, which makes them the fastest-growing product category in the neonatal thermoregulation market. Heated mattresses and pads are also gaining relevance in transport scenarios where radiant heat may be less practical under battery and mobility constraints. The neonatal thermoregulation market is therefore broadening at the product level from core warming hardware toward sensor-rich platforms that can extend monitoring value across more care environments.
Servo-controlled systems held 39.22% of technology-segment revenue in 2025, which kept them in the lead across the neonatal thermoregulation market because tighter thermal control is increasingly treated as a baseline standard in higher-acuity NICUs. The 2024 compliance amendments also reinforced the position of these systems by raising the performance and safety expectations attached to closed-loop control. Air-based systems still remain common in lower-acuity and budget-constrained facilities because their simpler design keeps acquisition costs lower.
Hybrid closed-loop systems are forecasted to grow at 9.16% CAGR through 2031, which gives them the fastest expansion path in the neonatal thermoregulation market. Hospitals are increasingly specifying platforms that combine radiant, convective, and conductive heat sources under a single feedback architecture because that reduces manual intervention and smooths thermal control. The neonatal thermoregulation market is therefore shifting technologically toward integrated systems that can support both routine warming and specialized cooling without forcing hospitals into separate workflows.
Complete Report Scope:
- By Product Type
- Incubators
- Radiant Warmers
- Heated Mattresses and Pads
- Temperature Monitoring Devices
- Thermal Blankets and Mattresses
- Infant Warmers
- Other Product Types
- By Technology
- Servo-Controlled Systems
- Air-Based Systems
- Water-Based Systems
- Hybrid Closed-Loop Systems
- By Application
- Hypothermia Management
- Normal Thermoregulation
- Hyperthermia Management
- Neonatal Intensive Care
- Postnatal Care
- By End-User
- Hospitals
- Neonatal Intensive Care Units
- Specialty Clinics
- Homecare Settings
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 46.36% of the neonatal thermoregulation market share in 2025, which kept it as the largest regional contributor because the United States has a dense tertiary NICU network, stronger reimbursement support, and active replacement cycles. Canada adds volume through provincial purchasing systems, while Mexico supports more mid-tier demand at lower average selling prices. Europe remains an important region for the neonatal thermoregulation market because established NICU networks across Germany, the United Kingdom, France, Italy, and Spain continue to buy devices that can meet tighter evidence and compliance expectations. The 2026 implementation deadlines around IEC amendments are also creating a compliance-led upgrade cycle across parts of Europe beyond the normal replacement pattern.
Asia-Pacific is forecasted to grow at 10.24% CAGR through 2031, which makes it the fastest-expanding region in the neonatal thermoregulation market. The main support comes from NICU expansion in India, provincial upgrades in China, and strong demand in Japan for higher-specification neonatal systems. The region also has more room for first-time procurement because large parts of the installed base remain below the sophistication seen in North America and Western Europe. Japan has already shown how fast adoption can move when products match workflow needs closely, especially in transport and referral use cases. The neonatal thermoregulation market in the rest of Asia-Pacific is also being widened by hospital investment in countries such as Vietnam, Indonesia, and Thailand, where budget limits still favor mid-tier platforms.
The Middle East and Africa present a split picture in the neonatal thermoregulation market because Gulf countries are investing in premium NICU infrastructure while much of Sub-Saharan Africa remains constrained by affordability and donor-linked purchasing. This leaves a strong clinical need in place, but it slows conversion into premium device demand where preterm birth burdens are high, and procurement budgets are thin. South America is led by Brazil and Argentina, with Brazil benefiting from local manufacturing that supports a cost-competitive regional supply. The rest of South America, including Colombia and Chile, offers a smaller but improving opportunity as urban hospitals continue to invest in neonatal care capacity.
- Atom Medical
- Bistos Co., Ltd.
- Cobams S.r.l.
- Dragerwerk
- Fanem Ltda.
- Fisher & Paykel Healthcare
- GE Healthcare
- Ginevri Srl
- Inspiration Healthcare Group plc
- International Biomedical, Ltd.
- Koninklijke Philips
- Masimo
- Medicor Elektronika Zrt.
- Medtronic
- Natus Medical
- Neonatech Medical Devices Pvt. Ltd.
- Ningbo David Medical Device
- Phoenix Medical Systems
- Pluss Advanced Technologies Pvt. Ltd.
- Vyaire Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Preterm Births and Low Birth Weight Incidence
- 4.2.2 Shift Toward Servo-Controlled Closed-Loop Thermoregulation
- 4.2.3 NICU Capacity Expansion in High-Burden Health Systems
- 4.2.4 Infection Control and Thermal Stability Prioritization in Delivery Rooms
- 4.2.5 Demand for Portable Warmers in Transport and Referral Networks
- 4.2.6 Microprocessor Supply Risk Driving Platform Redesign and Local Sourcing
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of Advanced Incubators and Warmers
- 4.3.2 Clinical Workflow Dependence on Skilled Biomedical Maintenance
- 4.3.3 Regulatory Approval and Recertification Burden
- 4.3.4 Kangaroo Mother Care and Low-Tech Thermal Care Substitution for Stable Neonates
- 4.4 Supply/Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Incubators
- 5.1.2 Radiant Warmers
- 5.1.3 Heated Mattresses and Pads
- 5.1.4 Temperature Monitoring Devices
- 5.1.5 Thermal Blankets and Mattresses
- 5.1.6 Infant Warmers
- 5.1.7 Other Product Types
- 5.2 By Technology
- 5.2.1 Servo-Controlled Systems
- 5.2.2 Air-Based Systems
- 5.2.3 Water-Based Systems
- 5.2.4 Hybrid Closed-Loop Systems
- 5.3 By Application
- 5.3.1 Hypothermia Management
- 5.3.2 Normal Thermoregulation
- 5.3.3 Hyperthermia Management
- 5.3.4 Neonatal Intensive Care
- 5.3.5 Postnatal Care
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Neonatal Intensive Care Units
- 5.4.3 Specialty Clinics
- 5.4.4 Homecare Settings
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 Atom Medical Corporation
- 6.3.2 Bistos Co., Ltd.
- 6.3.3 Cobams S.r.l.
- 6.3.4 Dragerwerk AG & Co. KGaA
- 6.3.5 Fanem Ltda.
- 6.3.6 Fisher & Paykel Healthcare Ltd
- 6.3.7 GE HealthCare
- 6.3.8 Ginevri Srl
- 6.3.9 Inspiration Healthcare Group plc
- 6.3.10 International Biomedical, Ltd.
- 6.3.11 Koninklijke Philips N.V.
- 6.3.12 Masimo Corporation
- 6.3.13 Medicor Elektronika Zrt.
- 6.3.14 Medtronic plc
- 6.3.15 Natus Medical Incorporated
- 6.3.16 Neonatech Medical Devices Pvt. Ltd.
- 6.3.17 Ningbo David Medical Device Co., Ltd.
- 6.3.18 Phoenix Medical Systems Pvt Ltd
- 6.3.19 Pluss Advanced Technologies Pvt. Ltd.
- 6.3.20 Vyaire Medical, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

