PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119320

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119320
RAN Vendor Selection Benchmarking - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the RAN vendor selection benchmarking market size is projected to expand from USD 36.84 billion in 2025 to USD 37.54 billion in 2026, and to USD 42.32 billion by 2031, registering a CAGR of 2.43% between 2026 and 2031.
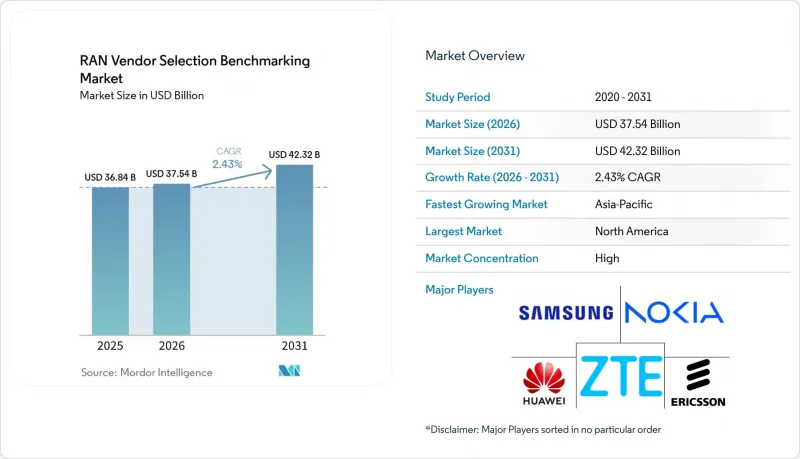
This report is Segmented by Offering (Hardware, Software, and Services), RAN Architecture (Traditional RAN, and More), Technology Generation (2G and 3G, 4G LTE, and 5G), Component (Radio Units, Distributed Units, and More), Deployment (Indoor, Outdoor, and More), End User (Telecom Operators, Enterprises, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global RAN Vendor Selection Benchmarking Market Trends and Insights
5G Standalone Rollouts in Emerging Regions
Commercial 5G standalone deployments are creating demand for new radio units, upgraded basebands, and standalone core integration. The Global Mobile Suppliers Association reported 95 operators with commercial 5G standalone services in April 2026. Emerging markets offer suppliers new opportunities as many operators move beyond non-standalone upgrades to full network modernization. These projects often favor vendors that can provide radio, software, integration, and operational support within a single delivery plan. Standalone availability still has to translate into service adoption and enterprise revenue, which keeps operators focused on coverage quality and practical monetization. The RAN Vendor Selection Benchmarking Market therefore benefits when suppliers can link standalone network investment to capacity, automation, and new service requirements.
Virtualized and Open RAN Adoption
Virtualized RAN adoption is changing how operators compare suppliers, as software capabilities now matter alongside radio performance. Open interfaces can broaden technical choice, but operators still seek tested combinations with clear accountability for support. Samsung and Orange Group expanded their vRAN and Open RAN partnership in Europe in 2026, following earlier pilots, indicating that operators are moving from trials to broader deployments. Vodafone had also selected Samsung for virtualized RAN and Open RAN work across European markets. These agreements show that integrated vRAN delivery can be more attractive than a fully disaggregated stack when operators need proven interoperability. The RAN Vendor Selection Benchmarking Market is consequently rewarding suppliers that combine cloud-native functions with clear responsibility for integration and performance.
High Radio Access Network Capital Intensity and Long Payback Periods
Radio access upgrades require substantial upfront investment, while the commercial return can take several years to develop. Operators in mature markets are therefore scrutinizing projects that cannot show a clear capacity, cost, or revenue benefit. Large macro-site upgrades also require work on power, transport, installation, and maintenance, which raises the full cost beyond the radio equipment itself. This favors established suppliers with a record of delivering complex networks at scale. It also extends sales cycles for smaller vendors that must demonstrate reliability before obtaining large contracts. The RAN Vendor Selection Benchmarking Market remains constrained when operators defer broad upgrades and prioritize targeted investments with faster payback.
Other drivers and restraints analyzed in the detailed report include:
- Private 5G and Industrial Connectivity Requirements
- Brownfield Network Modernization and Supplier Diversification
- Cybersecurity, Sovereignty, and Supply-Chain Qualification Burden
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware held 61.84% of the RAN Vendor Selection Benchmarking Market share in 2025 because macro expansion and Massive MIMO deployments require physical radio and baseband equipment. Radio hardware remains necessary for coverage, capacity, and 5G standalone upgrades. Operators still evaluate hardware suppliers on energy use, footprint, radio performance, and installation requirements. Hardware contracts also commonly include deployment and support services that add to total contract value. The RAN Vendor Selection Benchmarking Market size for hardware is driven by the continued modernization of public networks and the need to replace aging equipment.
Software is projected to grow at a 3.61% CAGR through 2031, the highest rate among offering types. AI-RAN subscriptions, cloud-native management platforms, and rApp-based optimization tools are shifting some spending toward recurring contracts. Ericsson launched its AI in RAN software subscription in June 2026 for use with deployed basebands and radios. Services remain important because migration, integration, and network optimization continue after equipment is installed. Suppliers that can combine software with integration support are better positioned for brownfield transformation programs. This mix gives operators more ways to improve an installed network without replacing every radio unit.
Traditional RAN accounted for 72.41% of the RAN Vendor Selection Benchmarking Market share in 2025, reflecting its large installed base across China, mature Asian markets, and the Americas. Integrated systems remain familiar to network operations teams and are often simpler to support. Many operators continue to select traditional architectures where predictable performance and single-vendor accountability are central priorities. Existing site configurations, operational tools, and trained workforces also support the continued use of traditional RAN. The large traditional base means suppliers must maintain their established portfolios even as they invest in newer platforms.
Virtualized RAN is projected to grow at a 4.37% CAGR through 2031, the fastest rate across architecture types. It moves more baseband functions into software that runs on commercial hardware, enabling feature updates and more flexible resource use. Rakuten Symphony completed interoperability testing of Samsung's vRAN and vCore on its cloud-native platform in March 2026. Centralized RAN offers an intermediate option for operators that want pooled processing but are not ready for full virtualization. Procurement teams increasingly review standards conformance, integration capability, and lifecycle support before selecting a virtualized architecture. This transition allows suppliers to compete on software, automation, and cloud operations rather than radio hardware alone.
Complete Report Scope:
- By Offering
- Hardware
- Software
- Services
- By RAN Architecture
- Traditional RAN
- Centralized RAN
- Virtualized RAN
- By Technology Generation
- 2G and 3G
- 4G LTE
- 5G
- By Component
- Radio Units
- Distributed Units
- Centralized Units
- Baseband Units
- Other Components
- By Deployment
- Indoor
- Outdoor
- Other Deployments
- By End User
- Telecom Operators
- Enterprises
- Smart Cities and Public Sector
- Defense and Security Organizations
- Industrial and Manufacturing Organizations
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 34.12% of the RAN Vendor Selection Benchmarking Market share in 2025, supported by earlier 5G investment, cloud RAN work, and AI-enabled radio trials. AT&T and Ericsson demonstrated AI-native Link Adaptation on a Cloud RAN stack powered by Intel Xeon 6 SoC in March 2026. The region's activity moderated after the heavy 5G buildout cycle, which makes targeted upgrades more likely than broad nationwide replacement programs. Security rules and the FCC Covered List also shape Supplier selection.
Asia-Pacific is projected to grow at a 3.63% CAGR through 2031, making it the fastest-growing geographic segment. India, Indonesia, Bangladesh, and Malaysia are in the active stages of 5G investment, while Australia, Japan, and South Korea continue to advance their network capabilities. Rakuten Mobile operates a large open vRAN network in Japan, and its 2026 work with Rakuten Symphony and 1Finity shows continued investment in open and cloud-native designs. China remains an important volume market, but the first phase of its 5G buildout has matured. The RAN Vendor Selection Benchmarking Market has varied opportunities across the region because national investment cycles and supplier preferences differ widely.
Europe, the Middle East, and Africa are important locations for replacement projects and new open-architecture deployments. Nokia agreed a 5-year RAN arrangement with Telefonica Germany that includes Cloud RAN and AI-powered management capabilities. Ericsson became Virgin Media O2's primary RAN partner through a 5-year extension in March 2026. Saudi Arabia hosted an O-RAN-neutral-host indoor 4G and 5G small-cell deployment at the King Abdullah Financial District. Africa is still at an earlier stage of standalone deployment, while fixed wireless access is supporting near-term 5G use.
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson (publ)
- Nokia Corporation
- ZTE Corporation
- Samsung Electronics Co., Ltd.
- Fujitsu Limited
- NEC Corporation
- Airspan Networks Holdings LLC
- Mavenir Systems, LLC
- Parallel Wireless, Inc.
- JMA Wireless, Inc.
- Comba Telecom Systems Holdings Limited
- Radisys Corporation
- Rakuten Symphony Singapore Pte. Ltd.
- Baicells Technologies Co., Ltd.
- Sercomm Corporation
- Alpha Networks Inc.
- Dali Wireless, Inc.
- Casa Systems, Inc.
- Airspan Networks Inc.
- 1Finity
- Viavi Solutions
- Wind River Systems
- SynaXG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G Standalone Rollouts in Emerging Regions
- 4.2.2 Virtualized and Open RAN Adoption
- 4.2.3 Private 5G and Industrial Connectivity Requirements
- 4.2.4 Brownfield Network Modernization and Supplier Diversification
- 4.2.5 AI-RAN Optimization for Capacity and Energy Economics
- 4.2.6 Open-Interface Compliance Becoming a Procurement Gate
- 4.3 Market Restraints
- 4.3.1 High Radio Access Network Capital Intensity and Long Payback Periods
- 4.3.2 Cybersecurity, Sovereignty, and Supply-Chain Qualification Burden
- 4.3.3 Multi-Vendor Accountability Gaps in Operational Support
- 4.3.4 Edge-Site Power and Thermal Constraints
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By RAN Architecture
- 5.2.1 Traditional RAN
- 5.2.2 Centralized RAN
- 5.2.3 Virtualized RAN
- 5.3 By Technology Generation
- 5.3.1 2G and 3G
- 5.3.2 4G LTE
- 5.3.3 5G
- 5.4 By Component
- 5.4.1 Radio Units
- 5.4.2 Distributed Units
- 5.4.3 Centralized Units
- 5.4.4 Baseband Units
- 5.4.5 Other Components
- 5.5 By Deployment
- 5.5.1 Indoor
- 5.5.2 Outdoor
- 5.5.3 Other Deployments
- 5.6 By End User
- 5.6.1 Telecom Operators
- 5.6.2 Enterprises
- 5.6.3 Smart Cities and Public Sector
- 5.6.4 Defense and Security Organizations
- 5.6.5 Industrial and Manufacturing Organizations
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Chile
- 5.7.2.4 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Australia
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East
- 5.7.5.1 United Arab Emirates
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 Qatar
- 5.7.5.4 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Egypt
- 5.7.6.3 Nigeria
- 5.7.6.4 Rest of Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Huawei Technologies Co., Ltd.
- 6.4.2 Telefonaktiebolaget LM Ericsson (publ)
- 6.4.3 Nokia Corporation
- 6.4.4 ZTE Corporation
- 6.4.5 Samsung Electronics Co., Ltd.
- 6.4.6 Fujitsu Limited
- 6.4.7 NEC Corporation
- 6.4.8 Airspan Networks Holdings LLC
- 6.4.9 Mavenir Systems, LLC
- 6.4.10 Parallel Wireless, Inc.
- 6.4.11 JMA Wireless, Inc.
- 6.4.12 Comba Telecom Systems Holdings Limited
- 6.4.13 Radisys Corporation
- 6.4.14 Rakuten Symphony Singapore Pte. Ltd.
- 6.4.15 Baicells Technologies Co., Ltd.
- 6.4.16 Sercomm Corporation
- 6.4.17 Alpha Networks Inc.
- 6.4.18 Dali Wireless, Inc.
- 6.4.19 Casa Systems, Inc.
- 6.4.20 Airspan Networks Inc.
- 6.4.21 1Finity
- 6.4.22 Viavi Solutions
- 6.4.23 Wind River Systems
- 6.4.24 SynaXG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

