PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119326

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119326
Calcined-Clay Cement Rheology Modifiers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the calcined-Clay cement rheology modifiers market size was valued at USD 286.42 million in 2025 and is estimated to grow from USD 301.74 million in 2026 to reach USD 393.06 million by 2031, at a CAGR of 5.43% during the forecast period (2026-2031).
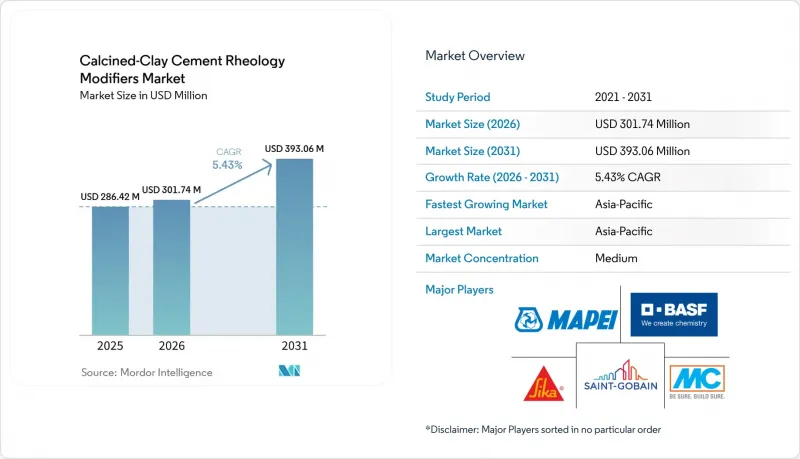
This report is Segmented by Product Type (Lignosulfonate-Based Modifiers and More), Function (Water Reduction and More), Calcined-Clay Cement Type (Metakaolin-Based Cement and More), Application (Ready-Mix Concrete and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Calcined-Clay Cement Rheology Modifiers Market Trends and Insights
Expansion Of Low-Carbon Cement Standards and Procurement
Public procurement requirements are shortening the adoption path for Limestone Calcined Clay Cement (LC3)-compatible admixtures by directly incorporating lower-carbon cement into project specifications and funding conditions. Ireland requires public bodies to specify low-carbon cement from September 2024 and mandates whole-life-cycle greenhouse gas assessments for exchequer-funded projects above EUR 10 million (~USD 11.54 million) from January 2026. Canada's Housing Infrastructure Fund links major projects to a 10% reduction in embodied carbon from ready-mix concrete relative to regional baselines, underscoring the importance of mix designs that can be documented and delivered consistently. Germany's 2025 Draft Procurement Acceleration Act established a route for climate-related cement procurement requirements, while ISO 21930 and EN 15804+A2 requirements reinforce the use of verified environmental product information in European supply chains. The Global Cement and Concrete Association introduced an 8-tier carbon rating framework in April 2025, providing procurement teams with a common basis for comparing lower-carbon cement and concrete products. These measures support the Calcined-Clay Cement Rheology Modifiers market because LC3 mixes require admixture systems that meet performance requirements, maintain placement reliability, and support carbon-related documentation.
Commercial Scale-Up of LC3 Production
LC3 production is moving from demonstration projects to industrial capacity, increasing the number of cement plants that require compatible rheology-modifier packages. By mid-2026, 35 industrial-scale plants were operating worldwide, another 35 were under construction, and installed capacity had reached 15 million tons per year. CIMPOR Global commissioned a 1,500-tons-per-day calcined-clay line in Souselas, Portugal, in 2026, demonstrating that large-scale production is no longer confined to a small group of early projects. JK Cement began commercial LC3 production at its Mangrol works in Rajasthan in July 2025 for infrastructure projects in Maharashtra, Gujarat, and Madhya Pradesh. Each new kiln commission requires ready-mix operators to qualify admixture packages against the new binder, evaluate local raw materials, and validate the required workability period. This process creates demand for testing, technical support, and repeat product validation within the Calcined-Clay Cement Rheology Modifiers market. The 2026 Cape Town conference reflected this shift from research toward wider industrial deployment.
Rapid Slump Loss from Reactive Clay Surface Generation
Rapid slump loss remains a major technical constraint to commercial LC3 use because the same clay chemistry that supports lower-clinker cement can shorten the period during which concrete remains workable. Elevated aluminate reactivity can promote ettringite formation and strong PCE adsorption, reducing the polymer available to disperse particles in the mix and causing a rapid loss of fluidity. Delayed addition, PCE-LDH nanocomposites, and phosphoric acid co-modifiers can help retain flow, but they add formulation steps, testing requirements, and cost. The problem is more pronounced in India and the Middle-East, where high ambient temperatures accelerate the loss of workable consistency during transport and placement. Smaller ready-mix producers may lack the dosing controls, laboratory capacity, and technical support needed for reliable field use. Mix verification and environmental product declaration requirements can add further qualification work for suppliers serving the calcined-clay cement rheology modifiers market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Ready-Mix and High-Performance Concrete Usage
- Clay-Source-Specific Polymer Formulation Demand
- Variability in Clay Mineralogy and Porosity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PCE-based modifiers held 40.72% of the calcined-clay cement rheology modifiers market share in 2025 and are forecast to grow at a 6.02% CAGR through 2031. This position reflects the need for high-efficiency dispersion in LC3 systems. HPEG-based polymers can outperform MPEG- and IPEG-based variants in calcined-clay cement across several tested formulations. This distinction is significant because the polymer hierarchy used in ordinary Portland cement does not always apply to calcined-clay binders. In LC3-50 systems, PCE dosage can be materially higher than in ordinary Portland cement mixtures. Higher dosage supports PCE revenue even when cement output does not grow at the same rate.
China's GB/T 8076-2025 standard takes effect in August 2026 and tightens performance criteria for concrete admixtures. The standard favors advanced PCE formulations over older naphthalene sulfonate products. Lignosulfonate-based modifiers continue to play a role in price-sensitive markets where lower raw material costs guide purchasing decisions. Cellulose ether-based products primarily serve to modify viscosity and enhance water retention in mortars and grouts. Other products include naphthalene sulfonate, acrylic-based, and hybrid chemistries, which face pressure from formaldehyde controls and PCE performance in high supplementary-cementitious-material blends. The calcined-clay cement rheology modifiers market is therefore shifting toward polymer designs that can match a defined clay source and performance target.
Water reduction accounted for 42.35% of the calcined-clay cement rheology modifiers market size in 2025. Calcined clay increases water demand as clinker substitution rises, making water reduction a basic requirement for many LC3 mix designs. A 2024 study reported that water demand can be up to 18% higher than ordinary Portland cement at 40% clay substitution. Viscosity modification is important in self-compacting concrete and mortars, where LC3's higher cohesiveness requires careful control. Anti-segregation and setting-time-control products also serve printing applications that require a narrow placement window. These functions provide suppliers with several routes into the calcined-clay cement rheology-modifier market beyond simple water reduction.
Workability enhancement and flow retention are forecast to grow at a 6.18% CAGR through 2031. They address the logistics interval after mixing, not only the initial spread of concrete. The 2026 Palava City fieldwork showed that a specialized PCE and phosphoric acid modifier were needed to retain workability for 3 hours. Water-reduction products are commonly evaluated against dosage cost and initial fluidity. Flow-retention products are evaluated against a reliable time window at the placement site. Suppliers that can document this result using a customer's local clay may convert a standard admixture sale into a more durable technical service relationship.
Complete Report Scope:
- By Product Type
- Polycarboxylate Ether (PCE)-Based Modifiers
- Lignosulfonate-Based Modifiers
- Cellulose Ether-Based Modifiers
- Others (Naphthalene Sulfonate, Acrylic-Based, Specialty Modifiers)
- By Function
- Water Reduction
- Workability Enhancement and Flow Retention
- Viscosity Modification
- Others (Anti-Segregation, Setting Time Control)
- By Calcined-Clay Cement Type
- LC3 (Limestone Calcined Clay Cement)
- Metakaolin-Based Cement
- Calcined Kaolinite-Based Cement
- Others (Emerging Calcined-Clay Cement Blends)
- By Application
- Ready-Mix Concrete
- Precast Concrete
- Mortars and Grouts
- 3D Printing Concrete
- Others (Shotcrete, Infrastructure Concrete)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 41.57% of the Calcined-Clay Cement Rheology Modifiers market share in 2025 and is forecast to grow at a 6.26% CAGR through 2031. India is scaling up LC3 production in line with IS 18189:2023. JK Cement started commercial LC3 production at Mangrol in July 2025 for projects in Maharashtra, Gujarat, and Madhya Pradesh. China's GB/T 8076-2025 standard took effect in August 2026 and supports the transition to higher-performance admixtures. Japan is studying amine-type admixtures for limestone-calcined clay cement, including methyldiethanolamine for carbonation resistance. South Korea and Indonesia add demand through infrastructure programs with stricter durability requirements.
North America and Europe are significant markets due to regulations that promote the disclosure, reduction, and qualification of embodied carbon. Canada requires embodied-carbon disclosure for concrete from September 2025, and its Public Transit Fund requires reductions in ready-mix concrete for major projects from 2026 to 2027. Europe's EN 197-5 recognizes CEM II/C-M (Q-LL), an LC3-compatible cement type. Australia's 2025 New South Wales Low Carbon Concrete Requirement and the ACT policy use performance-based public procurement. EU Implementing Regulation 2026/718 adds a sustainability dimension to procurement for major infrastructure contracts.
South America, the Middle-East, and Africa remain smaller regions but offer distinct project opportunities. In Ghana, the April 2025 commissioning of the Supacem LC3 facility and Heidelberg Materials and CBI Ghana's 400,000-tons-per-year flash calciner strengthened West Africa's calcined-clay production base. Ghana's GS PAS 5:2024 permits clinker content as low as 35%, supporting local LC3 investment. Brazil is expanding research on LC3 through federal universities. Saudi Arabia and the United Arab Emirates are linking construction programs to lower-carbon material requirements. The Calcined-Clay Cement Rheology Modifiers market in these regions depends on local testing capacity, product qualification, and reliable supply of suitable clay.
- Arkema
- BASF
- Chembond Chemicals Limited
- Dow
- Enaspol a.s.
- Fosroc, Inc.
- GCP Applied Technologies Inc.
- Kao Corporation
- Mapei S.p.A.
- MC-Bauchemie
- MUHU (China) Construction Materials Co., Ltd.
- RPM International Inc.
- Saint-Gobain
- Sika AG
- Sobute New Materials Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Low-Carbon Cement Standards and Procurement
- 4.2.2 Commercial Scale-Up of LC3 Production
- 4.2.3 Rising Ready-Mix and High-Performance Concrete Usage
- 4.2.4 Clay-Source-Specific Polymer Formulation Demand
- 4.2.5 Digital and Automated Admixture Dosing
- 4.2.6 Rheology Requirements in 3D-Printed and Specialty Concrete
- 4.3 Market Restraints
- 4.3.1 Rapid Slump Loss from Reactive Clay Surface Generation
- 4.3.2 Variability in Clay Mineralogy and Porosity
- 4.3.3 Higher Admixture Dosage and Formulation Cost
- 4.3.4 Incomplete Standards and Qualification Pathways
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Polycarboxylate Ether (PCE)-Based Modifiers
- 5.1.2 Lignosulfonate-Based Modifiers
- 5.1.3 Cellulose Ether-Based Modifiers
- 5.1.4 Others (Naphthalene Sulfonate, Acrylic-Based, Specialty Modifiers)
- 5.2 By Function
- 5.2.1 Water Reduction
- 5.2.2 Workability Enhancement and Flow Retention
- 5.2.3 Viscosity Modification
- 5.2.4 Others (Anti-Segregation, Setting Time Control)
- 5.3 By Calcined-Clay Cement Type
- 5.3.1 LC3 (Limestone Calcined Clay Cement)
- 5.3.2 Metakaolin-Based Cement
- 5.3.3 Calcined Kaolinite-Based Cement
- 5.3.4 Others (Emerging Calcined-Clay Cement Blends)
- 5.4 By Application
- 5.4.1 Ready-Mix Concrete
- 5.4.2 Precast Concrete
- 5.4.3 Mortars and Grouts
- 5.4.4 3D Printing Concrete
- 5.4.5 Others (Shotcrete, Infrastructure Concrete)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 Chembond Chemicals Limited
- 6.4.4 Dow
- 6.4.5 Enaspol a.s.
- 6.4.6 Fosroc, Inc.
- 6.4.7 GCP Applied Technologies Inc.
- 6.4.8 Kao Corporation
- 6.4.9 Mapei S.p.A.
- 6.4.10 MC-Bauchemie
- 6.4.11 MUHU (China) Construction Materials Co., Ltd.
- 6.4.12 RPM International Inc.
- 6.4.13 Saint-Gobain
- 6.4.14 Sika AG
- 6.4.15 Sobute New Materials Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

