PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119563

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119563
Asbestos - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the asbestos market size is expected to grow from USD 1.13 billion in 2025 to USD 1.16 billion in 2026 and is forecast to reach USD 1.35 billion by 2031 at 3.01% CAGR over 2026-2031.
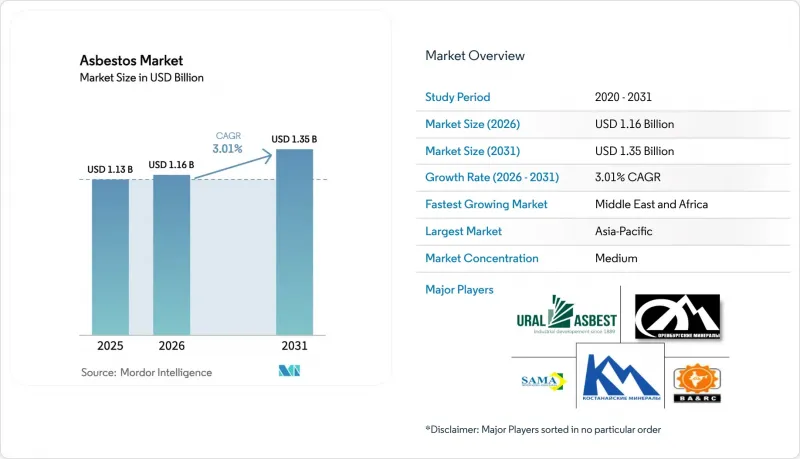
This report is Segmented by Type (Chrysotile, Amosite, Crocidolite, Tremolite, Actinolite, and Anthophyllite), Application (Building Materials, Electrical Insulation, Friction Products, Packaging, Gaskets, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Asbestos Market Trends and Insights
Rapid infrastructure growth in APAC and Africa sustaining low-cost asbestos cement demand
Large-scale housing and transport programs across India, China, Nigeria, and Ethiopia continue to favor asbestos cement because of its price advantage and ready supply. India imported 361,164 tonnes in 2019-2020, mainly from Russia, to feed roof and pipe projects that dominate affordable housing. Chinese construction firms expanding into Ethiopia and Angola often specify asbestos cement sheets for rural schools and warehouses, reinforcing demand corridors that link Asian producers with African builders. Nigeria's construction sector historically consumed more than 1 million tons across multiple projects, indicating an entrenched user base that still values the material's durability. WHO warns that asbestos-related diseases cause 125,000 annual deaths worldwide, yet governments prioritizing cost control continue to approve imports. This infrastructure-led demand underpins the asbestos market even as global bans intensify.
Rising retrofit and repair activity in legacy asbestos-built stock
Millions of roofs, water mains, and wallboards installed before bans now require upkeep, prompting steady demand for encapsulation coatings, removal services, and replacement panels. Specialized contractors invest in negative-pressure enclosures, HEPA filtration, and certified disposal, which pushes startup costs to USD 150,000 and beyond according to industry surveys. The United States consumed 110 tons of chrysotile from stockpiles in 2024, entirely for maintenance in chlor-alkali plants that still rely on asbestos diaphragms. Latvia's 2024 pilot removal scheme exhausted its budget months early, underscoring the latent workload in older housing stock. These retrofit activities extend the asbestos market life cycle while fostering the parallel growth of alternative materials that can slot into existing fittings without design changes.
Acceleration of national bans (e.g., EPA 2024 US chrysotile phase-out)
The United States outlawed chrysotile imports in March 2024 and set phased conversion deadlines that extend through 2037 for specialty uses. Mexico's Congress advanced a blanket prohibition in January 2024, widening the no-use zone across North America. More than 60 countries now enforce full bans, and multilateral bodies such as WHO continue to promote substitution initiatives. The chlor-alkali sector alone faces USD 2.8 billion to USD 3.4 billion in conversion costs under the updated rule set. As each major economy implements restrictions, suppliers lose market access, compressing global consumption and redirecting fiber toward fewer permissive destinations.
Other drivers and restraints analyzed in the detailed report include:
- Cost advantage of chrysotile over synthetic substitutes for chlor-alkali diaphragms
- Weak enforcement of asbestos bans in high-growth emerging economies
- Escalating litigation and insurance costs for producers and downstream users
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Chrysotile captured 94.23% of asbestos market share in 2025 because builders, automakers, and chlor-alkali operators favor its flexible fibers and relative availability. Russia accounted for 48% of global mine output in 2025, followed by Kazakhstan, Brazil, and China, yet sanctions and logistics issues trimmed Russian exports from 65% to 48% since 2020. Tremolite exhibited a 3.16% CAGR through 2031, the fastest within the asbestos market, due to specialized metallurgical and heat-shield applications where substitutes remain costly. EPA's 2024 ban removed chrysotile access to the lucrative United States, signaling that amphibole types could inherit a residual share only in jurisdictions without bans. As more countries align with WHO recommendations, type demand will splinter into narrow geographic niches, making supply more volatile.
Many producers already segment inventory by destination. Russian mines channel premium chrysotile grades to India and China, whereas mid-grade fiber moves to Africa and Latin America where construction standards are lower. In contrast, amphibole demand is now almost entirely research-driven, with universities and material science firms ordering micro quantities for controlled experiments in filtration and high-temperature ceramics. Such shifts illustrate a bifurcated asbestos market that simultaneously contracts in volume yet persists in high-precision pockets.
Complete Report Scope:
- By Type
- Chrysotile
- Amosite
- Crocidolite
- Tremolite
- Actinolite
- Anthophyllite
- By Application
- Building Materials
- Electrical Insulation
- Friction Products
- Packaging
- Gaskets
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 70.62% of asbestos market revenue in 2025, led by India's position as the world's top importer at 44% of global volume. The region employed about 300,000 workers across more than 100 plants, creating economic inertia that resists health-based reforms. China remained both a major consumer and producer, and public health projections forecast 15,000 annual asbestos disease deaths by 2035, underscoring the social costs of continued use. Indonesia, Vietnam, and the Philippines also retain permissive rules, funneling fiber from Russian and Kazakhstan mines into roofing and piping lines. These factors cement Asia-Pacific's dominance in the asbestos market even as international advocacy builds against it.
North America underwent structural change after the United States banned chrysotile in 2024. Domestic consumption fell to 110 tons sourced entirely from legacy stockpiles, and chlor-alkali plants must complete membrane conversions by 2037. Canada, once a significant producer, now exports almost all mined asbestos to Asia but faces external pressure to shutter operations. Mexico's draft ban would seal off the final regional outlet, consolidating a continental moratorium that influences global trade lanes. Litigation remains the region's defining legacy burden, with billions in outstanding claims that squeeze balance sheets across the construction, industrial gas, and consumer goods sectors.
Europe maintains a zero-tolerance policy on new asbestos use, having implemented bans across member states in the 1990s. Legacy remediation now dominates activity, including the removal of insulating boards from schools and public buildings. The European Commission still grants narrow derogations for low-voltage chlor-alkali cells where safe dismantling is technically complex, but those exceptions are shrinking. National programs such as Latvia's 2024 pilot demonstrate that remediation demand often outstrips fiscal capacity, suggesting a long tail of asbestos service activity. These experiences feed innovation in alternative fiber-cement boards and membrane technologies that exporting firms now sell to Asia, Africa, and Latin America.
- BHARAT ASBESTOS & RUBBER CO.
- JSC Orenburg Minerals
- Kostanay Minerals JSC
- Ningbo Xinyan Friction Materials Co., Ltd.
- PJSC Uralasbest
- SAMA Mineracao de Amianto Ltda.
- Visaka Industries Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Infrastructure Growth in APAC and Africa Sustaining Low-Cost Asbestos Cement Demand
- 4.2.2 Rising Retrofit and Repair Activity in Legacy Asbestos-Built Stock (Roofing, Pipes)
- 4.2.3 Cost Advantage of Chrysotile Over Synthetic Substitutes for Chlor-Alkali Diaphragms
- 4.2.4 Weak Enforcement of Asbestos Bans in High-Growth Emerging Economies
- 4.2.5 Niche Demand from Specialised Gaskets in Chemical and Oil Processing
- 4.3 Market Restraints
- 4.3.1 Acceleration of National Bans (E.G., EPA 2024 US Chrysotile Phase-Out)
- 4.3.2 Escalating Litigation and Insurance Costs for Producers and Downstream Users
- 4.3.3 Rapid Commercialisation of Non-Asbestos Fibre-Cement and Brake Friction Materials
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Chrysotile
- 5.1.2 Amosite
- 5.1.3 Crocidolite
- 5.1.4 Tremolite
- 5.1.5 Actinolite
- 5.1.6 Anthophyllite
- 5.2 By Application
- 5.2.1 Building Materials
- 5.2.2 Electrical Insulation
- 5.2.3 Friction Products
- 5.2.4 Packaging
- 5.2.5 Gaskets
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Russia
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BHARAT ASBESTOS & RUBBER CO.
- 6.4.2 JSC Orenburg Minerals
- 6.4.3 Kostanay Minerals JSC
- 6.4.4 Ningbo Xinyan Friction Materials Co., Ltd.
- 6.4.5 PJSC Uralasbest
- 6.4.6 SAMA Mineracao de Amianto Ltda.
- 6.4.7 Visaka Industries Ltd
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

