PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119824

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119824
Asia-Pacific Automotive Plastics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, Asia-Pacific automotive plastics market size in 2026 is estimated at 10.22 Million tons, growing from 2025 value of 9.73 Million tons with 2031 projections showing 13.07 Million tons, growing at 5.04% CAGR over 2026-2031.
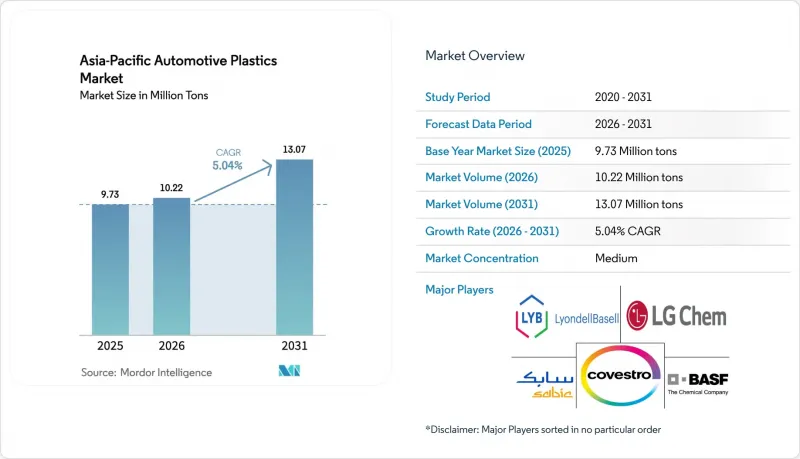
This report is Segmented by Material (Polypropylene, Polyurethane, Polyvinyl Chloride, and More), Vehicle Type (Conventional/Traditional Vehicles and Electric Vehicles), Application (Exterior, Interior, Under-Bonnet, and Other Applications), and Geography (China, India, Japan, South Korea, ASEAN, and Rest of Asia-Pacific). The Market Forecasts are Provided in Terms of Volume (Tons).
Asia-Pacific Automotive Plastics Market Trends and Insights
Lightweighting Mandate Compliance
Regulatory authorities across Asia-Pacific tie fleet-average emissions to weight reduction goals. Automakers respond by substituting metals with advanced polypropylene blends that deliver complex geometries at lower cost. Borealis Fibremod long-glass-fiber polypropylene helped reduce the weight of Volkswagen's Multivan by 200 kg and met stiffness targets. Gigacasting adoption, first popularised by Tesla, is reshaping body-in-white strategies and puts pressure on plastics suppliers to justify structural roles. To keep pace, compounders introduce chemical foaming agents such as Avient Hydrocerol that cut door-panel weight by 20% while lowering carbon dioxide emissions. In China, where battery-electric vehicles are forecast to command 52.9% of total light-vehicle sales by 2036, lightweight plastic modules that also manage heat are becoming indispensable.
Growing Polypropylene Penetration in Interiors and Exteriors
Polypropylene's noise-dampening and processing advantages are driving adoption in high-performance components. Rochling Automotive intake manifolds trimmed cabin noise by 10-15 dB compared with polyamide alternatives and saved 15% on material cost. Research teams in Japan blend cellulose nanofibres into polypropylene, boosting impact strength while preserving full recyclability, a feature attractive under extended-producer-responsibility laws. Compounds with 30% post-consumer resin from Sirmax now appear in door panels, cutting lifecycle carbon footprints by 21% and meeting odor thresholds. Exterior cladding benefits from ultraviolet-stable grades such as LyondellBasell CirculenRecover that retain dimensional integrity while offering 20% recycled content. Process optimisation studies confirm that higher packing pressure mitigates shrinkage, reinforcing polypropylene's appeal for visible Class-A surfaces.
Recycling Infrastructure Gaps and Regulatory Pressure
Extended-producer-responsibility rules proliferate, yet collection and sorting capacity lag vehicle scrappage rates in several markets. India's End-of-Life Vehicles Rules 2025 introduce comprehensive online tracking but omit detailed plastic quotas, limiting immediate circularity gains. Vietnam mandates a 22% recycling rate for rigid PET packaging, signaling future obligations for automotive plastic modules that raise compliance costs. Japan's mature stewardship programmes still focus on packaging, so automotive parts fall outside current take-back streams. Technical studies show that bumper regrind loses impact resistance if primer removal is incomplete, underscoring the need for chemical recycling to complement mechanical routes. Supply-chain collaborations such as Yanfeng-Trinseo aim to bridge the gap by scaling dissolution and advanced-sorting technologies that meet 2030 targets.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Electric-Vehicle Production Volumes
- Cost Reduction via High-throughput Injection Moulding
- Volatility in Raw-material (Naphtha / Propylene) Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polypropylene commands the largest slice of the automotive plastics market at 41.10% volume share. ExxonMobil Achieve Advanced grades lift impact strength above legacy copolymers, allowing thinner structures that lower mass and support a USD 55 per-ton margin squeeze. Polycarbonate delivers the fastest 7.12% CAGR as processors embrace Covestro mechanically recycled content for glazing and lighting housings. Thermoplastic polyurethane supply is set to tighten once BASF's Zhanjiang mega-line ramps up, responding to electrification needs that require flexible cable jacketing in 800 V architectures.
The automotive plastics market size for engineering resins is climbing with acrylonitrile-butadiene-styrene shifting toward biomass styrene monomer and polyamide 66 seeing 40 000-ton capacity increments in Shanghai. Polyethylene still supports packaging and lightweight exterior trims, whereas PVC faces image pressure under circularity pledges. Specialty families like ASA, PBT, and PMMA supply niche roles such as weather-resistant grilles and scooter battery packs. As Asia-Pacific refineries convert crude to chemicals, upstream integration provides cost buffers that safeguard polypropylene's foothold against the surging engineering-resin cohort.
Complete Report Scope:
- By Material
- Polypropylene (PP)
- Polyurethane (PU)
- Polyvinyl Chloride (PVC)
- Polyethylene (PE)
- Acrylonitrile-Butadiene-Styrene (ABS)
- Polyamides (PA)
- Polycarbonate (PC)
- Other Materials (ASA, PET, PBT, PMMA, etc.)
- By Vehicle Type
- Conventional/Traditional Vehicles
- Electric Vehicles
- By Application
- Exterior
- Interior
- Under-bonnet
- Other Applications (Instrument Panel, Door Systems, etc.)
- By Geography
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Arkema
- Asahi Kasei Advance Corporation
- BASF SE
- Borealis AG
- Celanese Corporation
- Covestro AG
- dsm-firmenich
- Evonik Industries AG
- Exxon Mobil Corporation
- Kingfa Science and Technology (India) Limited
- LG Chem
- LyondellBasell Industries Holdings B.V.
- Polyplastics Co., Ltd
- SABIC
- Toray Industries Inc
- Trinseo
- Victrex plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Lightweighting Mandate Compliance
- 4.2.2 Growing Polypropylene Penetration in Interiors and Exteriors
- 4.2.3 Surge in Electric-Vehicle Production Volumes
- 4.2.4 Cost Reduction via High-throughput Injection Moulding
- 4.2.5 OEM Score-card Targets for Bio-based/Recycled Plastics
- 4.3 Market Restraints
- 4.3.1 Recycling Infrastructure Gaps and Regulatory Pressure
- 4.3.2 Volatility in Raw-material (Naphtha/Propylene) Pricing
- 4.3.3 Emerging Alloy-Aluminium Substitution in Structural Parts
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Material
- 5.1.1 Polypropylene (PP)
- 5.1.2 Polyurethane (PU)
- 5.1.3 Polyvinyl Chloride (PVC)
- 5.1.4 Polyethylene (PE)
- 5.1.5 Acrylonitrile-Butadiene-Styrene (ABS)
- 5.1.6 Polyamides (PA)
- 5.1.7 Polycarbonate (PC)
- 5.1.8 Other Materials (ASA, PET, PBT, PMMA, etc.)
- 5.2 By Vehicle Type
- 5.2.1 Conventional/Traditional Vehicles
- 5.2.2 Electric Vehicles
- 5.3 By Application
- 5.3.1 Exterior
- 5.3.2 Interior
- 5.3.3 Under-bonnet
- 5.3.4 Other Applications (Instrument Panel, Door Systems, etc.)
- 5.4 By Geography
- 5.4.1 China
- 5.4.2 India
- 5.4.3 Japan
- 5.4.4 South Korea
- 5.4.5 ASEAN
- 5.4.6 Rest of Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Arkema
- 6.4.2 Asahi Kasei Advance Corporation
- 6.4.3 BASF SE
- 6.4.4 Borealis AG
- 6.4.5 Celanese Corporation
- 6.4.6 Covestro AG
- 6.4.7 dsm-firmenich
- 6.4.8 Evonik Industries AG
- 6.4.9 Exxon Mobil Corporation
- 6.4.10 Kingfa Science and Technology (India) Limited
- 6.4.11 LG Chem
- 6.4.12 LyondellBasell Industries Holdings B.V.
- 6.4.13 Polyplastics Co., Ltd
- 6.4.14 SABIC
- 6.4.15 Toray Industries Inc
- 6.4.16 Trinseo
- 6.4.17 Victrex plc
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

