PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119880

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119880
Acrylic Resin - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the acrylic resin market size is expected to grow from 6.86 million tons in 2025 to 7.13 million tons in 2026 and is forecast to reach 8.67 million tons by 2031 at 3.99% CAGR over 2026-2031.
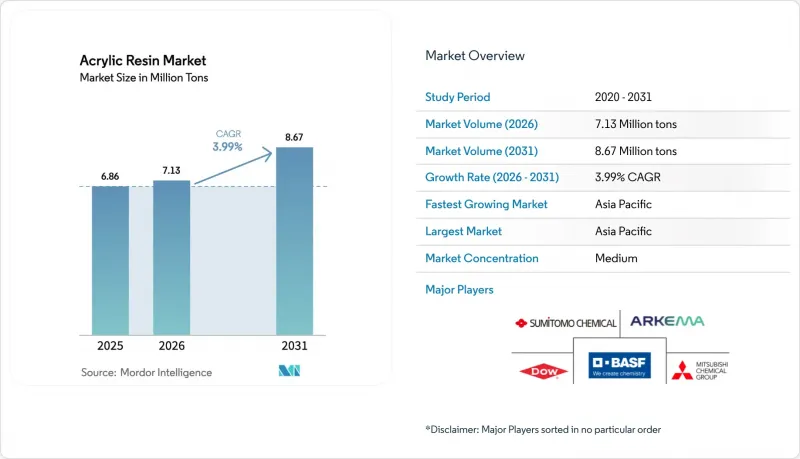
This report is Segmented by Product Type (Acrylates, Methacrylates, and Hybrids), Application (Paints and Coatings, Adhesives and Sealants, and Other Applications), End-User Industry (Building and Construction, Automotive, Electrical and Electronics, Plastics, Textile and Fibers, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa).
Global Acrylic Resin Market Trends and Insights
Expansion in Construction and Infrastructure Activities
Global construction recovery underpins consistent acrylic resin market growth, with multi-year infrastructure programs in China, India, and the United States translating into rising coatings and panel demand. Project developers increasingly specify waterborne acrylics to meet green-building criteria, elevating consumption across exterior and interior applications. Formaldehyde-free binder technologies such as BASF's Acrodur systems further strengthen market pull by aligning with indoor-air-quality standards. Overall, infrastructure spending assures a visible demand pipeline that anchors the acrylic resin market amid cyclical end-uses.
Rising Demand for Lightweight Automotive Components
Electrification accelerates lightweighting imperatives, and acrylic resins enable mass reduction across glazing, body panels, and battery enclosures. Collaborative product development, for example, Honda and Mitsubishi Chemical's pre-colored PMMA parts, removes paint steps while lowering lifecycle CO2 emissions by 50%. Regulatory fuel-economy targets in Europe and the United States guarantee long-run demand for high-strength, low-density polymers. Electric-vehicle battery housings further require thermal stability and dimensional accuracy, properties well served by methacrylate grades. Coupled with autonomous-vehicle sensor needs for optical clarity, these factors sustain premium volumes within the acrylic resin market.
Environmental and Health Hazards of Acrylates
Regulators continue to evaluate exposure risks, tightening permissible monomer concentrations in manufacturing and consumer products. Enhanced ventilation, monitoring, and personal protective equipment raise compliance costs across the acrylic resin industry. Consumer awareness of VOC and odor profiles influences purchasing choices, particularly in residential coatings. Safety-driven brand differentiation is, therefore, necessary but costly for producers. Ongoing toxicology studies aim to substantiate safe-use thresholds, yet lingering perception risks cap adoption where substitute resins exist.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Consumption of Low-VOC Water-Borne Coatings
- Rapid Adoption of 3D-Printing Photopolymer Resins
- Volatile Propylene and MMA Feed-Stock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Methacrylates retained a 51.62% acrylic resin market share in 2025 thanks to their optical clarity and weatherability, but acrylates are on track for a 5.18% CAGR through 2031 as bio-based chemistries broaden their usage window. In volume terms, methacrylate grades serve glazing, signage, and premium coatings, anchoring the upper tier of the acrylic resin market. Acrylate polymers, propelled by adhesive and flexible-coating demand, capitalize on lower cost and easier processability, gaining ground in emerging applications. LG Chem's roll-out of fully plant-derived acrylic acid illustrates how sustainability attributes are pulling customers toward acrylate variants.
Industry initiatives around chemical recycling are narrowing the performance gap between virgin and recovered methacrylates. Mitsubishi Chemical's microwave-assisted depolymerization of post-consumer PMMA back to MMA monomer promises circular-economy compliance without sacrificing material quality. Advancements in catalyst architectures and reactor design further enhance throughput and property control across both product families, sharpening competitive differentiation.
Complete Report Scope:
- By Product Type
- Acrylates
- Methacrylates
- Hybrids
- By Application
- Paints and Coatings
- Adhesives and Sealants
- Other Applications (Pigment Dispersion, Elastomers, etc.)
- By End-User Industry
- Building and Construction
- Automotive
- Electrical and Electronics
- Plastics
- Textile and Fibers
- Paper and Paperboard
- Other Applications (Packaging and Consumer Goods)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordic Countries
- Turkey
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Nigeria
- Egypt
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 50.96% of global volume in 2025 and is positioned for a 5.57% CAGR through 2031, reflecting the region's dual role as a manufacturing hub and rising consumption center. China continues to prioritize megainfrastructure investment, stimulating coatings and sealants uptake across transport, energy, and residential projects. Japan's advanced automotive and electronics clusters carve out demand for premium methacrylate grades with tight optical and mechanical tolerances.
North America and Europe operate as technology and regulation leaders. The EPA's revised aerosol-coating VOC rule grants a compliance grace period to 2027, yet still locks in a trajectory toward low-emission acrylic chemistries. European industry is channeling capital into chemical-recycling pilots and ISCC+ certified supply chains, reinforcing a premium on traceable low-PCF resins. Both regions lean heavily on lightweight automotive programs, adding high-margin outlets for specialty grades.
South America, the Middle East, and Africa are nascent but gathering pace. Industrialization, logistics corridors, and petrochemical joint ventures in the Gulf are fostering regional acrylic resin capacity additions. Although currency swings and regulatory heterogeneity pose hurdles, local market proximity cuts freight and import tariffs, improving cost-to-serve metrics.
- Allnex GMBH
- Arkema
- BASF
- Covestro AG
- DIC Corporation
- Dow
- Evonik Industries AG
- Henkel AG & Co. KGaA
- Mitsubishi Chemical Group Corporation
- Nippon Shokubai Co., Ltd.
- Resonac Holdings Corporation
- Rohm GmbH
- Sumitomo Chemical Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion in Construction and Infrastructure Activities
- 4.2.2 Rising Demand for Lightweight Automotive Components
- 4.2.3 Increasing Consumption of Low-VOC Water-Borne Coatings
- 4.2.4 Rapid Adoption of 3-D-Printing Photopolymer Resins
- 4.2.5 Growth of Smart/Self-Healing Coating Technologies
- 4.3 Market Restraints
- 4.3.1 Environmental and Health Hazards of Acrylates
- 4.3.2 Volatile Propylene and MMA Feed-Stock Prices
- 4.3.3 Competition From Bio-Based Polymer Alternatives
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Acrylates
- 5.1.2 Methacrylates
- 5.1.3 Hybrids
- 5.2 By Application
- 5.2.1 Paints and Coatings
- 5.2.2 Adhesives and Sealants
- 5.2.3 Other Applications (Pigment Dispersion, Elastomers, etc.)
- 5.3 By End-User Industry
- 5.3.1 Building and Construction
- 5.3.2 Automotive
- 5.3.3 Electrical and Electronics
- 5.3.4 Plastics
- 5.3.5 Textile and Fibers
- 5.3.6 Paper and Paperboard
- 5.3.7 Other Applications (Packaging and Consumer Goods)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Malaysia
- 5.4.1.6 Thailand
- 5.4.1.7 Indonesia
- 5.4.1.8 Vietnam
- 5.4.1.9 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Nordic Countries
- 5.4.3.7 Turkey
- 5.4.3.8 Russia
- 5.4.3.9 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Nigeria
- 5.4.5.6 Egypt
- 5.4.5.7 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Allnex GMBH
- 6.4.2 Arkema
- 6.4.3 BASF
- 6.4.4 Covestro AG
- 6.4.5 DIC Corporation
- 6.4.6 Dow
- 6.4.7 Evonik Industries AG
- 6.4.8 Henkel AG & Co. KGaA
- 6.4.9 Mitsubishi Chemical Group Corporation
- 6.4.10 Nippon Shokubai Co., Ltd.
- 6.4.11 Resonac Holdings Corporation
- 6.4.12 Rohm GmbH
- 6.4.13 Sumitomo Chemical Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

