PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119899

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119899
Home Security Camera - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the home security camera market size is expected to grow from USD 23.79 billion in 2025 to USD 27.37 billion in 2026 and is forecast to reach USD 55.17 billion by 2031 at 15.04% CAGR over 2026-2031.
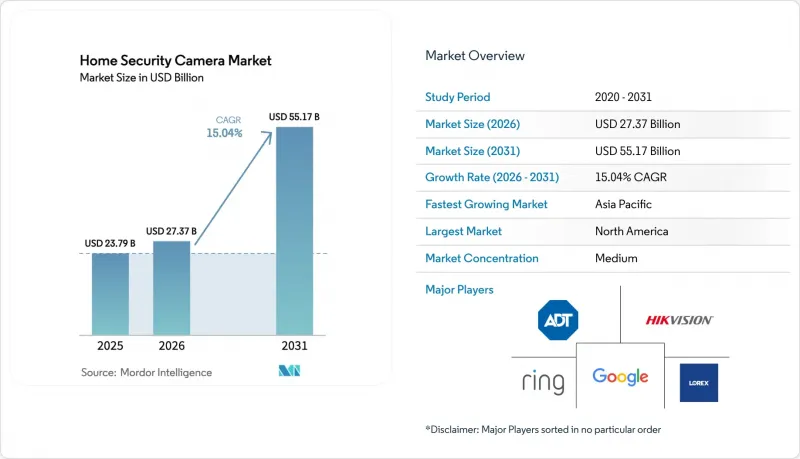
This report is Segmented by Product Type (Bullet, Dome, PTZ, and More), Connectivity (Wired, and Wireless), Power Source (AC-Powered, and Battery/Solar-Powered), Resolution (HD <=1080p, Full-HD 1080p, and More), Application (Indoor, Outdoor, and Doorbell), and by Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Home Security Camera Market Trends and Insights
Integration with Smart-Home Ecosystems and Voice Assistants
The convergence of security cameras, smart displays, and voice control creates a network effect that raises switching costs for consumers and cements platform loyalty. Apple's planned AI Home Display underscores how major tech firms embed surveillance at the center of broader automation suites. Amazon's Ring pushes the envelope with AI-generated motion summaries that transform raw video into actionable insights, reinforcing the strategic value of proprietary cloud analytics. As ecosystems mature, hardware margins compress while recurring service revenues expand, redefining competitive dynamics in the home security camera market.
Declining ASP of HD and 4K IP Cameras from Chinese OEM Overcapacity
Overcapacity among Chinese original-equipment manufacturers triggers a price deflation cycle that democratizes 4K resolution, yet forces Western suppliers to pivot toward differentiated software and privacy features. Hikvision's 2024 price list shows mainstream 4K models trending below prior HD price points, eroding the entry barrier for high-resolution adoption. Simultaneously, the US replacement program for restricted vendors channels USD 247 million into domestic alternatives, accelerating a bifurcated market where price-sensitive households gravitate to Chinese brands, while security-critical users favor Western vendors despite higher costs.
Data-Privacy Regulations Limiting Continuous Cloud Recording
European GDPR rules mandate data-protection impact assessments and curtail always-on recording, compelling manufacturers to invest in privacy-by-design architectures and local storage options. Compliance adds bill-of-materials cost and limits subscription revenue from cloud retention, dampening uptake among privacy-sensitive consumers.
Other drivers and restraints analyzed in the detailed report include:
- Insurance Premium Discounts for Homes with Verified Video Monitoring
- Rapid FTTH Roll-outs Enabling 24/7 Cloud Uploads in ASEAN
- CMOS Image-Sensor Supply Volatility Creating Price Spikes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bullet cameras retained 37.55% share of the home security camera market in 2025, a position anchored in versatile indoor-outdoor use and cost-effectiveness. Doorbell units, while smaller in base, post the fastest 15.86% CAGR as households prioritize package-delivery verification and seamless smart-home integration. Dome and PTZ cameras occupy stable commercial niches, whereas box cameras remain specialized.
The 15.86% growth rate in doorbells reflects rising urban parcel theft and ecosystem incentives such as AI motion summaries from Ring that push adoption beyond early adopters. Insurance discounts accelerate demand, reinforcing the home security camera market trend toward entry-point visibility.
Wireless devices captured 60.45% of the home security camera market share in 2025 and head toward a 15.62% CAGR to 2031. DIY-friendly installation and relocation agility improve the adoption curve, while proprietary long-range hubs such as Blink Sync Module XR extend coverage to 400 feet.
Wired systems maintain relevance for mission-critical commercial settings, yet slower growth reflects labor and cabling costs. As battery longevity improves, wireless penetration is expected to exceed two-thirds of the home security camera market by 2031.
Complete Report Scope:
- By Product Type
- Bullet Security Camera
- Dome Security Camera
- PTZ Security Camera
- Box Security Camera
- Doorbell (Video Doorbell) Camera
- By Connectivity
- Wired
- Wireless
- By Power Source
- AC-Powered
- Battery / Solar-Powered
- By Resolution
- HD (<=1080p)
- Full-HD (1080p)
- 2K QHD
- 4K UHD and Above
- By Application
- Indoor Camera
- Outdoor Camera
- Doorbell Camera
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- GCC
- Turkey
- Israel
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America commanded 37.60% of the home security camera market in 2025. High disposable income, suburban housing density, and insurer incentives sustain stable annual upgrades. The United States champions ecosystem lock-in through companies such as Amazon, while Canada's colder climate elevates demand for energy-efficient models.
Asia Pacific posts the highest 16.34% CAGR through 2031. Regional FTTH expansion and smart-city grants in markets such as Singapore, Malaysia, and Thailand underpin cloud-centric adoption. China remains sizable despite external trade restrictions, driven by domestic demand and municipal safety initiatives. India's rise of middle-class homeowners and e-commerce volumes fuels incremental unit sales. Japan and South Korea emphasize premium 4K and privacy-enhanced solutions, whereas Australia and New Zealand adopt high-end offerings supported by government rebates.
Europe records steady growth but at a moderated pace due to GDPR compliance costs. Germany and the United Kingdom show strong uptake of privacy-compliant hybrid storage models, while France, Italy, and Spain benefit from municipal subsidies that offset hardware prices. Manufacturers that localize data and offer on-premises video processing gain a competitive edge in the regional home security camera market.
- Hangzhou Hikvision Digital Technology Co. Ltd
- Ring LLC (Amazon)
- Google LLC (Nest)
- ADT Inc.
- Lorex Technology Inc. (Flir)
- Arlo Technologies Inc.
- Wyze Labs Inc.
- Dahua Technology Co., Ltd.
- Blink LLC (Amazon)
- SimpliSafe Inc.
- Canary Connect Inc.
- Swann Communications
- Axis Communications AB
- Vivint Smart Home Inc.
- Eufy Security (Anker Innovations)
- Logitech International S.A.
- Swann Communications
- TP-Link Technologies Co., Ltd. (Tapo)
- Yi Technology
- Netatmo (SA Legrand)
- CP PLUS (Gunnebo Group)
- Xiaomi
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Integration with Smart-Home Ecosystems and Voice Assistants in North America and Europe
- 4.2.2 Declining ASP of HD and 4K IP Cameras due to Chinese OEM Overcapacity
- 4.2.3 Insurance Premium Discounts for Homes with Verified Video Monitoring
- 4.2.4 Rapid FTTH Roll-outs Enabling 24/7 Cloud Uploads in ASEAN
- 4.2.5 Urban Middle-Class Demand after Rise in Parcel Theft
- 4.2.6 Government Smart-City Safety Grants Subsidising Residential CCTV
- 4.3 Market Restraints
- 4.3.1 Data-Privacy Regulations Limiting Continuous Cloud Recording
- 4.3.2 Saturation of Early-Adopter Segments in Developed Markets
- 4.3.3 CMOS Image-Sensor Supply Volatility Creating Price Spikes
- 4.3.4 Rising Geopolitical Scrutiny on Chinese Brands
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory or Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Bullet Security Camera
- 5.1.2 Dome Security Camera
- 5.1.3 PTZ Security Camera
- 5.1.4 Box Security Camera
- 5.1.5 Doorbell (Video Doorbell) Camera
- 5.2 By Connectivity
- 5.2.1 Wired
- 5.2.2 Wireless
- 5.3 By Power Source
- 5.3.1 AC-Powered
- 5.3.2 Battery / Solar-Powered
- 5.4 By Resolution
- 5.4.1 HD (<=1080p)
- 5.4.2 Full-HD (1080p)
- 5.4.3 2K QHD
- 5.4.4 4K UHD and Above
- 5.5 By Application
- 5.5.1 Indoor Camera
- 5.5.2 Outdoor Camera
- 5.5.3 Doorbell Camera
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Australia
- 5.6.4.7 New Zealand
- 5.6.4.8 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 GCC
- 5.6.5.1.2 Turkey
- 5.6.5.1.3 Israel
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Hangzhou Hikvision Digital Technology Co. Ltd
- 6.4.2 Ring LLC (Amazon)
- 6.4.3 Google LLC (Nest)
- 6.4.4 ADT Inc.
- 6.4.5 Lorex Technology Inc. (Flir)
- 6.4.6 Arlo Technologies Inc.
- 6.4.7 Wyze Labs Inc.
- 6.4.8 Dahua Technology Co., Ltd.
- 6.4.9 Blink LLC (Amazon)
- 6.4.10 SimpliSafe Inc.
- 6.4.11 Canary Connect Inc.
- 6.4.12 Swann Communications
- 6.4.13 Axis Communications AB
- 6.4.14 Vivint Smart Home Inc.
- 6.4.15 Eufy Security (Anker Innovations)
- 6.4.16 Logitech International S.A.
- 6.4.17 Swann Communications
- 6.4.18 TP-Link Technologies Co., Ltd. (Tapo)
- 6.4.19 Yi Technology
- 6.4.20 Netatmo (SA Legrand)
- 6.4.21 CP PLUS (Gunnebo Group)
- 6.4.22 Xiaomi
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

