PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120291

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120291
Particle Size Analysis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the particle size analysis market size reached USD 489.26 million in 2026 and is projected to increase to USD 661.56 million by 2031, representing a 6.22% CAGR across the forecast period.
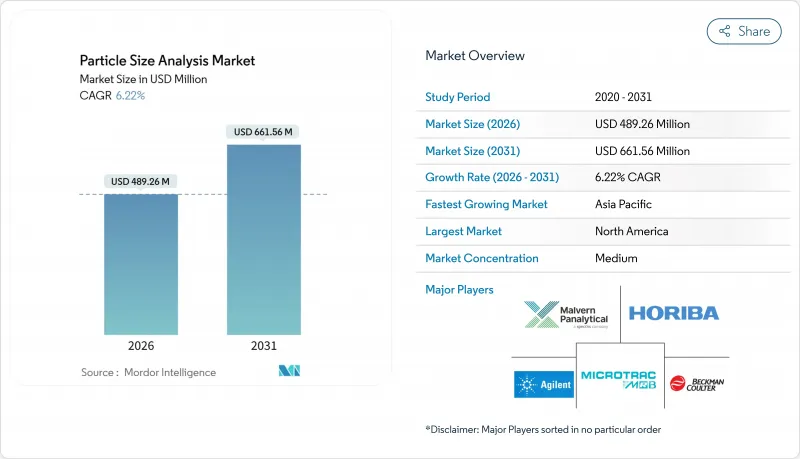
This report is Segmented by Technology (Laser Diffraction, Imaging Analysis, and More), Dispersion Type (Wet Particle Analyzers, Dry Particle Analyzers, and More), Mode of Analysis (Offline/Laboratory Systems, Online/At-Line Systems, and More), End-User Industry (Agriculture and Forestry, Environmental and Regulatory Labs, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Global Particle Size Analysis Market Trends and Insights
Rising Research Activity in Nanotechnology
Harmonized testing guidelines for manufactured nanomaterials now specify particle-size distribution as a core element of the dossier, creating an immediate demand for sub-50 nm instrumentation. Universities and national labs deploy nanoparticle tracking analysis and dynamic light scattering to validate quantum dots, lipid nanoparticles, and oxide catalysts. Laser-diffraction vendors retrofit modules for finer ranges, but face competition from microfluidic devices that consolidate size, zeta potential, and concentration in single cartridges. This convergence is widening the supplier base while accelerating innovation cycles, ultimately enlarging the particle size analysis market footprint.
Growing Pharmaceutical Quality-Control Needs
The FDA's 2024 revision of analytical validation guidance explicitly requires robustness studies for particle-size methods in solid and parenteral dosage forms, turning optional characterization into a legal mandate. Complementary ICH Q14 rules embed particle-size analysis within process-validation frameworks, prompting generics, biosimilars, and contract manufacturers to install redundant laser-diffraction and dynamic light-scattering systems to pass sponsor audits. Orthogonal techniques, such as nanoparticle tracking analysis or field-flow fractionation, gain traction in profiling sub-micron protein aggregates. The spending wave effectively doubles mid-tier equipment demand, reinforcing the particle size analysis market.
High Capital and Maintenance Costs
Flagship laser-diffraction systems list above USD 100,000 and require annual service contracts priced at 15-20% of hardware value, pressuring budgets at contract manufacturers and academic labs. Import tariffs and currency fluctuations in emerging regions can increase entry costs by 20-30%, steering buyers toward refurbished gear. Vendors respond with leasing and instrument-as-a-service models, but they must carry inventory risk, which keeps margins thin and lengthens payback, softening near-term uptake within the particle size analysis market.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Online and Inline Real-Time Analysis
- AI-Enabled Multi-Technique Integration
- Shortage of Skilled Operators and Data Scientists
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Laser diffraction accounted for 32.74% of 2025 revenue, maintaining the largest particle size analysis market share due to a 10 nm-3,500 µm dynamic range that suits both fine APIs and coarse clinker. Validation against ISO 13320 enables laboratories to file data without lengthy method justification, and software plugins now overlay zeta potential and concentration, allowing users to diagnose root-cause failures on a single screen. Suppliers defend the franchise by bundling imaging add-ons, cloud libraries, and CFR Part 11 audit trails, which shorten the installation qualification process for pharmaceutical buyers. Competitive noise centers on resolution; vendors advertise sub-100 nm sensitivity, but diffraction physics limits precision once particles approach the laser wavelength, pushing buyers to consider orthogonal tools for biologics and solid-state battery tasks.
Nanoparticle tracking analysis, forecast to advance at a 7.69% CAGR to 2031, solves that blind spot with single-particle visualization below 100 nm, making it the fastest-moving slice of the particle size analysis market. Biologic drug makers use this method to quantify protein aggregates that trigger immunogenicity, while battery developers check sulfide electrolytes for uniformity at sub-5 µm levels that prevent dendrite formation. Dynamic light scattering maintains a strong presence in academia for hydrodynamic radius studies, but batch mode and dilution artifacts hinder industrial adoption. Imaging analyzers fill morphology-sensitive niches, such as abrasives and metal powders, whereas the Coulter principle is resurfacing in graphite slurries because electrical impedance can ignore refractive-index swings. Ultra-specialized Taylor dispersion and resonant mass instruments command premium prices in R&D environments where absolute precision outweighs throughput.
Wet dispersion instruments captured 53.89% of 2025 revenue by underpinning slurry-heavy verticals, such as mining, ceramics, and pharmaceutical suspensions, where inline density adjustments rely on rapid feedback loops. Closed-loop recirculation cells reduce solvent use, and anti-settling impellers prevent coarse tails from skewing the D50, thereby reinforcing the technology's hold on the particle size analysis market share. Dry analyzers remain staples for cement, toner, and metal powders; however, combustible-dust standards require inert-gas purges, which increase operating costs, prompting some users to adopt wet methods using volatile solvents that evaporate after testing.
Spray analyzers are projected to grow at a 6.81% CAGR, driven by stricter aerodynamic particle-size distribution limits in inhaler and nasal spray dossiers. Optical spectrometers built into formulation booths now alert operators when droplet medians drift beyond cascade-impactor guardrails, slashing rework. Pesticide formulators in Brazil and Argentina are adopting laser-based spray profilers to curb off-target drift and meet environmental caps, creating a new market opportunity within particle size analysis. Barriers remain: calibrating spray optics to reference impactors demands meticulous alignment, and closed-loop solvent capture can add USD 15,000-25,000 to capital outlay, a hurdle for mid-tier producers.
Complete Report Scope:
- By Technology
- Laser Diffraction
- Dynamic Light Scattering
- Nanoparticle Tracking Analysis
- Imaging Analysis
- Coulter Principle
- Taylor Dispersion Analysis
- Resonant Mass Measurement
- By Dispersion Type
- Wet Particle Analyzers
- Dry Particle Analyzers
- Spray Particle Analyzers
- By Mode of Analysis
- Offline / Laboratory Systems
- Online / At-Line Systems
- Inline / Real-Time Process Systems
- By End-User Industry
- Pharmaceuticals and Biopharmaceuticals
- Chemicals and Petrochemicals
- Food, Beverage and Nutrition
- Mining, Minerals and Cement
- Agriculture and Forestry
- Energy and Battery Materials
- Environmental and Regulatory Labs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 37.79% of the 2025 revenue. Intensive FDA inspection schedules have made particle-size validation a non-negotiable dossier element, and the region's biopharma clusters continue to drive demand for replacement systems. Midwest and Southeastern battery gigafactories integrate dozens of inline probes to monitor cathode slurries, while Canada's potash and critical-mineral assets sustain steady wet-analysis sales. Installed-base maturity means that replacement rather than greenfield projects dominate, so vendors pivot to service contracts and software upgrades.
Asia-Pacific is projected to post a 7.27% CAGR through 2031, led by China's dominance in lithium-ion technology and subsidies for domestic instrumentation. Local producers, Bettersize Instruments and Winner Particle, expand within mid-tier price bands, eroding market share from imported systems. Japan's quality-obsessed pharmaceutical and ceramics sectors continue to buy premium analyzers, and South Korea's display and semiconductor fabs deploy particle-size checks to qualify CMP slurries. India's generics industry upgrades its labs to meet US and EU data-integrity requirements, while Australia leverages inline analyzers in mineral processing.
Europe balances mature adoption with continuous manufacturing directives. German chemical and automotive plants embed particle-size sensors into digital twin platforms, and the United Kingdom's dual regulatory landscape drives duplicate instrumentation to satisfy both domestic and EU authorities. France deploys particle-size analyzers in nuclear fuel and aerospace composites where traceability over decades is essential. The Middle East and Africa are gaining traction through mining, and South America is showing a budding uptake in agricultural spray analysis, with Brazil and Argentina leading the adoption.
- Malvern Panalytical Ltd
- Horiba Ltd
- Beckman Coulter Inc.
- Agilent Technologies Inc.
- Microtrac MRB
- Micromeritics Instruments Corporation
- IZON Science Limited
- Sympatec GmbH
- Shimadzu Corporation
- Anton Paar GmbH
- Brookhaven Instruments Corporation
- Bettersize Instruments Ltd
- Particle Sizing Systems, LLC
- Jinan Winner Particle Instrument Stock Co., Ltd.
- Retsch GmbH
- Otsuka Electronics Co. Ltd
- LS Instruments AG
- CORDOUAN Technologies SAS
- Metso Outotec
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Research Activity in Nanotechnology
- 4.2.2 Growing Pharmaceutical Quality-Control Needs
- 4.2.3 Shift Toward Online and Inline Real-Time Analysis
- 4.2.4 AI-Enabled Multi-Technique Integration
- 4.2.5 Soaring Demand for Battery and Energy-Storage Materials Testing
- 4.2.6 Expansion of Microfluidic Lab-on-Chip PSA Devices
- 4.3 Market Restraints
- 4.3.1 High Capital and Maintenance Costs
- 4.3.2 Shortage of Skilled Operators and Data Scientists
- 4.3.3 Sample Preparation Complexity for Agglomerated Particles
- 4.3.4 Competition from Alternative Characterisation Methods
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Laser Diffraction
- 5.1.2 Dynamic Light Scattering
- 5.1.3 Nanoparticle Tracking Analysis
- 5.1.4 Imaging Analysis
- 5.1.5 Coulter Principle
- 5.1.6 Taylor Dispersion Analysis
- 5.1.7 Resonant Mass Measurement
- 5.2 By Dispersion Type
- 5.2.1 Wet Particle Analyzers
- 5.2.2 Dry Particle Analyzers
- 5.2.3 Spray Particle Analyzers
- 5.3 By Mode of Analysis
- 5.3.1 Offline / Laboratory Systems
- 5.3.2 Online / At-Line Systems
- 5.3.3 Inline / Real-Time Process Systems
- 5.4 By End-User Industry
- 5.4.1 Pharmaceuticals and Biopharmaceuticals
- 5.4.2 Chemicals and Petrochemicals
- 5.4.3 Food, Beverage and Nutrition
- 5.4.4 Mining, Minerals and Cement
- 5.4.5 Agriculture and Forestry
- 5.4.6 Energy and Battery Materials
- 5.4.7 Environmental and Regulatory Labs
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Malvern Panalytical Ltd
- 6.4.2 Horiba Ltd
- 6.4.3 Beckman Coulter Inc.
- 6.4.4 Agilent Technologies Inc.
- 6.4.5 Microtrac MRB
- 6.4.6 Micromeritics Instruments Corporation
- 6.4.7 IZON Science Limited
- 6.4.8 Sympatec GmbH
- 6.4.9 Shimadzu Corporation
- 6.4.10 Anton Paar GmbH
- 6.4.11 Brookhaven Instruments Corporation
- 6.4.12 Bettersize Instruments Ltd
- 6.4.13 Particle Sizing Systems, LLC
- 6.4.14 Jinan Winner Particle Instrument Stock Co., Ltd.
- 6.4.15 Retsch GmbH
- 6.4.16 Otsuka Electronics Co. Ltd
- 6.4.17 LS Instruments AG
- 6.4.18 CORDOUAN Technologies SAS
- 6.4.19 Metso Outotec
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

