PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120682

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120682
Civil Aerospace Training And Simulation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the civil aerospace simulation and training market size is expected to grow from USD 1.93 billion in 2025 to USD 2.07 billion in 2026 and is forecasted to reach USD 2.9 billion by 2031 at a 6.98% CAGR over 2026-2031.
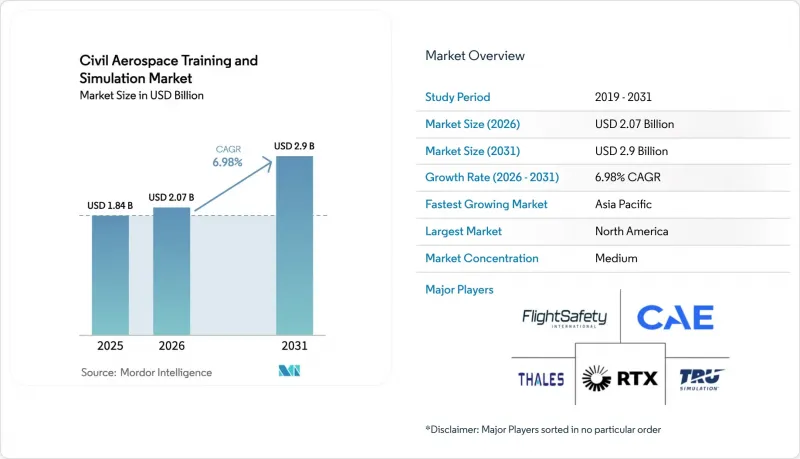
This report is Segmented by Simulator Type (Full Flight Simulator, Flight Training Devices, and Other Simulator Types), Application (Commercial Aviation and Space), End User (Commercial Airlines, Flight Training Organizations, Space Agencies, and Others), and Geography (North America, South America, and More). Market Forecasts are Provided in Terms of Value (USD).
Global Civil Aerospace Training And Simulation Market Trends and Insights
Rising Global Demand for Trained Pilots, Technicians, and Cabin Crew
The worldwide fleet expansion has outpaced the talent pipelines. Boeing's 2025 outlook indicated a need for 649,000 new commercial pilots by 2043, with 42% of them located in the Asia-Pacific region. China aims to recruit an additional 100,000 pilots by 2035 to operate nearly 4,930 transport aircraft. India's airlines ordered more than 1,000 narrowbody jets between 2023 and 2025, forcing carriers to reserve simulator slots years in advance. Maintenance technicians also require recurrent composite repair and avionics updates for new-generation airframes, while cabin crews must certify in high-density evacuation procedures. These combined needs funnel students into the civil aerospace simulation and training market far more quickly than legacy training centers can scale, fueling demand for both fixed-site Level-D devices and mobile VR units that alleviate peak load.
Growing Adoption of VR- and AR-Based Portable Simulators for Early Stage Training
Head-mounted displays are shifting ab-initio curricula from brick-and-mortar schools to modular spaces. Loft Dynamics gained EASA approval in 2024 for an untethered VR helicopter simulator that operators can deploy aboard offshore platforms or in temporary classrooms. CAE's 2025 rollout of the CAE Rise augmented-reality suite overlays checklists onto cockpit mock-ups, thereby reducing cognitive load during the first 50 hours of training. The US Air Force's Pilot Training Next project cut time-to-wings by 30%, a metric that civilian schools emulate to accelerate throughput. VR devices cost barely 2% of a Level-D simulator, enabling smaller academies to tap into the civil aerospace simulation and training market without incurring heavy debt. Airlines in secondary cities now lease such equipment to pre-screen cadets, freeing full-motion bays for high-stakes checks.
High Capital Costs Associated with Full-Flight and Level-D Simulators
A Level-D simulator for aircraft such as the B737 MAX or A320neo involves significant capital investment and recurring maintenance costs, reflecting the advanced technical requirements of these aircraft. Banks in Southeast Asia and Africa demand pre-sold hours as collateral, yet airlines hesitate to sign lengthy contracts without proof of availability, trapping small schools in a financing loop. Leasing eases capital expenditures but carries rate premiums that erode thin margins. For widebody simulators, utilization below 4,000 hours turns the asset uneconomic, concentrating capacity in megahubs and leaving outlying regions underserved.
Other drivers and restraints analyzed in the detailed report include:
- Use of Digital Twin Technologies to Personalize and Optimize Training Outcomes
- Expansion of Airline Fleets and Introduction of New Aircraft Types Increasing Transition Training Needs
- Limited Availability of Qualified Simulator Instructors and Examiners
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Full-flight simulators accounted for 75.47% of the civil aerospace simulation and training market in 2025. Regulatory frameworks, such as FAA 14 CFR Part 60, compel their use for type ratings and recurrent checks, ensuring baseline demand even during traffic downturns. Yet, the civil aerospace simulation and training market size for other simulator types is projected to expand at a 7.24% CAGR, reflecting airlines' shifting of ab-initio and refresher tasks to VR headsets and fixed-base devices.
Growth in portable systems reduces capital intensity while widening geographic reach. Loft Dynamics' untethered platform eliminates hydraulic motion and fits inside shipping containers for pop-up classrooms. Redbird Flight Simulations logged a 40% rise in fixed-training-device orders among US Part 141 schools in 2025. As regulators gradually credit more synthetic hours, the civil aerospace simulation and training market gains a two-tier structure: high-fidelity bays for high-stakes checks and scalable VR labs for volume throughput.
Complete Report Scope:
- By Simulator Type
- Full Flight Simulator (FFS)
- Flight Training Devices (FTDs)
- Other Simulator Types
- By Application
- Commercial Aviation
- Space
- By End User
- Commercial Airlines
- Flight Training Organizations
- Space Agencies
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 47.17% of the 2025 revenue, driven by OEM clusters, a dense network of over 200 training centers, and FAA rules that allow up to 50% of recurrent checks to be credited to simulators. Utilization frequently exceeds 5,000 hours per device per year, ensuring swift payback and steady aftermarket demand for software refreshes. Growth moderates toward replacement of aging bays rather than greenfield builds, with incremental upside tied to 777X and eVTOL simulator launches.
The Asia-Pacific is the locomotive of the civil aerospace simulation and training market, forecasted to grow at a 7.75% annual rate to 2031, as China, India, Indonesia, and Vietnam embark on historic fleet expansions. Beijing funds concessional loans that cut interest costs for training academies, while India's 100% FDI allowance spurred a CAE-InterGlobe joint venture in 2024 with eight simulators online in Delhi and Bangalore. Indonesia's Lion Air ordered six 737 MAX devices in 2025, citing the logistical advantage of localizing type-rating capacity.
Europe, under EASA, exhibits lower headline growth but steady revenue from the five-year revalidation cycle, which compels upgrades to match aircraft software baselines. Middle East mega-carriers operate captive centers that also serve as third-party hubs for African and South Asian pilots, leveraging geographic centrality to achieve high-yield utilization. Africa remains under-penetrated after South African Airways shuttered its Johannesburg center, forcing trainees to travel abroad, an expense that dampens demand. South America is concentrated in Brazil, where Azul sustains a small but profitable cluster of A320 and 737 simulators in Sao Paulo.
- CAE Inc.
- FlightSafety International Inc.
- Thales Group
- RTX Corporation
- The Boeing Company
- TRU Simulation + Training Inc.
- Indra Sistemas S.A.
- FRASCA International, Inc.
- ALSIM EMEA
- Redbird Flight Simulations, Inc.
- Loft Dynamics AG
- REISER Simulation and Training GmbH
- Entrenadores Olarte, S.L.
- Elite Simulation Solutions AG
- Havelsan Inc.
- AXIS Flight Training Systems GmbH
- Airbus SE
- Pan Am Flight Academy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising global demand for trained pilots, technicians, and cabin crew
- 4.2.2 Increasingly stringent safety and regulatory training requirements
- 4.2.3 Cost advantages of simulation-based training compared to live aircraft operations
- 4.2.4 Growing adoption of VR- and AR-based portable simulators for early stage training
- 4.2.5 Use of digital twin technologies to personalize and optimize training outcomes
- 4.2.6 Expansion of airline fleets and introduction of new aircraft types increasing transition training needs
- 4.3 Market Restraints
- 4.3.1 High capital costs associated with full flight and Level-D simulators
- 4.3.2 Regulatory certification and approval backlogs delaying simulator deployment
- 4.3.3 Rising cybersecurity and data-protection costs for cloud-connected training systems
- 4.3.4 Limited availability of qualified simulator instructors and examiners constraining training capacity
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Simulator Type
- 5.1.1 Full Flight Simulator (FFS)
- 5.1.2 Flight Training Devices (FTDs)
- 5.1.3 Other Simulator Types
- 5.2 By Application
- 5.2.1 Commercial Aviation
- 5.2.2 Space
- 5.3 By End User
- 5.3.1 Commercial Airlines
- 5.3.2 Flight Training Organizations
- 5.3.3 Space Agencies
- 5.3.4 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 CAE Inc.
- 6.4.2 FlightSafety International Inc.
- 6.4.3 Thales Group
- 6.4.4 RTX Corporation
- 6.4.5 The Boeing Company
- 6.4.6 TRU Simulation + Training Inc.
- 6.4.7 Indra Sistemas S.A.
- 6.4.8 FRASCA International, Inc.
- 6.4.9 ALSIM EMEA
- 6.4.10 Redbird Flight Simulations, Inc.
- 6.4.11 Loft Dynamics AG
- 6.4.12 REISER Simulation and Training GmbH
- 6.4.13 Entrenadores Olarte, S.L.
- 6.4.14 Elite Simulation Solutions AG
- 6.4.15 Havelsan Inc.
- 6.4.16 AXIS Flight Training Systems GmbH
- 6.4.17 Airbus SE
- 6.4.18 Pan Am Flight Academy
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

